In emerging markets, pricing — not reputation — drives the partnership between underwriter and IPO. Photo via business.rice.edu

Many investors assume they can judge the strength of an IPO based on the reputation of the underwriter supporting it.

However, a recent study by Rice Business professors Anthea Zhang and Haiyang Li, along with Jin Chen (Nottingham University) and Jing Jin (University of International Business and Economics), proves this is only sometimes true — depending on how mature the stock exchange is.

Getting your company listed on the stock market is a big step. It opens new opportunities to raise money and grow the business. But it also means facing increased regulations, reporting requirements and public scrutiny.

To successfully launch an initial public offering (IPO), most companies hire “underwriters” — financial services firms — to guide them through the complex process. Because underwriters have expertise in valuations, filing paperwork and promoting to investors, they play a crucial role in ushering companies onto the market.

In well-established markets like the New York Stock Exchange (NYSE), an underwriter’s reputation carries immense weight with investors. Top-tier banks like Goldman Sachs have built their reputations by rigorously vetting and partnering with only the most promising companies. When Goldman Sachs takes on the role of underwriter, it sends a strong signal to potential investors that the IPO has met stringent standards. After all, a firm of Goldman’s caliber would not risk tarnishing its hard-earned reputation by associating with subpar companies.

Conversely, IPO firms recognize the value of having a prestigious underwriter. Such an association lends credibility and prestige, enhancing the company’s appeal. In a mature market environment, the underwriter’s reputation correlates to the IPO’s potential, benefiting both the investors who seek opportunities and the companies wanting to make a strong public debut.

However, assumptions about an underwriter’s reputation only hold true if the stock exchange is mature. In emerging or less developed markets, the reputation of an underwriter has no bearing on the quality or potential of the IPO it pairs with.

In an emerging market, the study finds, investors should pay attention to how much the underwriter charges a given IPO for their services. The higher the fee, the riskier it would be to invest in the IPO firm.

To arrive at their findings, the researchers leveraged a unique opportunity in China’s ChiNext Exchange. When ChiNext opened in 2009, regulations were low. Banks faced little consequence for underwriting a substandard IPO. Numerous IPOs on ChiNext were discovered to have engaged in accounting malpractice and inaccurate reporting, resulting in financial losses for investors and eroding confidence in the capital markets. So, for 18 months during 2012-2013, ChiNext closed. When it reopened, exchange reforms were stricter. And suddenly, underwriter reputation became a more reliable marker of IPO quality.

“Our research shows how priorities evolve as markets mature,” Zhang says. “In a new or developing exchange without established regulations, underwriter fees paid by IPO firms dictate the underwriter-company partnership. But as markets reform and mature, reputation and quality become the driving factors.”

The study makes a critical intervention in the understanding of market mechanisms. The findings matter for companies, investors and regulators across societies, highlighting how incentives shift, markets evolve and economic systems work.

The research opens the door to other areas of inquiry. For example, future studies could track relationships between underwriters and companies to reveal the long-term impacts of reputation, fees and rule changes. Research along these lines could help identify best practices benefiting all market participants.

“In the future, researchers could explore how cultural norms, regulations and investor behaviors influence IPO success,” says Li. “Long-term studies on specific underwriter-firm pairs could reveal insights into investor confidence and market stability. Understanding these dynamics can benefit companies, investors and policymakers alike.”

------

This article originally ran on Rice Business Wisdom and was based on research from Yan “Anthea” Zhang, the Fayez Sarofim Vanguard Professor of Management – Strategic Management at Rice Business, and Haiyang Li, the H. Joe Nelson III Professor of Management – Strategic Management at Rice Business.

A patent is an asset — one with a price associated with it when it comes to procuring a loan for your business. Photo via Getty Images

Rice research: What innovations can be used to borrow against?

Houston voices

For companies and leaders, patents represent important assets. They’re a marker of innovation and tech development. But patents do so much more than protect intellectual property. Firms increasingly deploy them as collateral to secure loans. Between 1995 and 2013, the number of patents pledged as loan collateral increased from about 10,000 to nearly 50,000. Forty percent of U.S. patenting firms have used patents as collateral.

However, patents are intangible assets, and their liquidity and liquidation value are difficult to assess. To evaluate an individual patent, lenders must consider the invention space to which the patent belongs. A patent’s linkage to prior inventions can provide important information for lenders, as the linkage affects the extent to which the patent under consideration may be redeployed and potentially purchased by other firms in the case of loan default.

Rice Business professor Yan Anthea Zhang examined more closely how this market operates and how both lenders and borrowers can make more informed decisions on which patents make appealing collateral. In their paper, “Which patents to use as loan collateral? The role of newness of patents' external technology linkage,” Zhang, who specializes in strategic management, and her co-authors studied the data on 107,180 U.S. semiconductor patents owned by 436 U.S. firms. The team focused on semiconductor patents because the semiconductor industry involves intensive innovation, which leads to many patent applications and grants. The market for semiconductor patents is an active and well-functioning market, given specialization in different stages of the innovation process and the growing technological market. Information on whether a patent was used as loan collateral came from the USPTO Patent Assignments Database.

Zhang and her colleagues argue that lenders prefer patents linked to prior inventions that are relatively new because these patents are riding on recent technology waves and are less likely to become obsolete. As a result, such patents are likely to remain deployable to other firms in the future. However, patents that are based upon too new prior inventions might not prove to be commercially viable and carry higher risk for lenders.

As a result of this research, Zhang and her colleagues found an inverted U-shape relationship to demonstrate the likelihood that a patent will be used as loan collateral. On one end, patents based upon the newest prior inventions, on the other, patents based upon mature prior inventions. The curve of the U-shape represents the sweet spot for patent collateral—the patents’ technological base is new enough to be relevant and competitive with other firms in its invention space, but not so new that it has yet to prove market success.

Zhang’s team also found that the impact of external linkage also varies depending on borrower attributes, especially the borrowers’ expertise in the invention space. If a borrower is a technological leader in the invention space, the market tends to give the borrower credit, and as a result, even if its patents are based upon very new prior inventions, its patents are still likely to be accepted as collateral.

------

This article originally ran on Rice Business Wisdom and was based on research from Yan Anthea Zhang, the Fayez Sarofim Vanguard Professor of Management at Rice Business.

Expanding into foreign markets is tempting, but strategic fit can determine success or disaster. Photo via Getty Images

To expand or not to expand? Houston researcher weighs in on global growth

houston voices

You built your business from the ground up, patiently finding techniques and products that work, carefully crafting solid bonds with your clients. Then one day a new project, opportunity or simple request poses a question: Is it time to branch out overseas?

Of the welter of questions to consider, the first and most important involves location: not just the physical location of the prospective expansion site, but the cultural differences between a firm's home country and its new destination. Secondly, key company traits need to be considered in choosing the investment locations. Is your firm large or small? Young or old? Finally, of pivotal importance to companies outside the United States: Is your company privately held or state-owned?

In a recent paper, Rice Business professor Yan Anthea Zhang looked closely at these three variables with Yu Li of the University of International Business and Economics Business School in Beijing, China and Wei Shi of the Miami Business School at the University of Miami. What, the researchers wanted to know, was the relation of these three features and firms' location choices for their overseas investments?

To find out, Zhang and her colleagues analyzed 7,491 Chinese firms that had recently ventured into foreign markets with 9,558 overseas subsidiaries. Because China now has become the world's leading source of foreign direct investments, the sample promised to be instructive. Thanks to the large sample size, researchers could test hypotheses relating to firm size, age, ownership and the impact of geographical and cultural distance on their location choices.

After studying the elements of geographic distance and cultural distance, Zhang and her colleagues uncovered a paradox. Companies that had an advantage in tackling one dimension of distance were actually disadvantaged — because of the same characteristic — in another dimension.

How, exactly, did this paradox work? Larger firms, with access to more resources, can "experiment with new strategies, new products, and new markets," the researchers wrote. This large size makes geographic distance less of a concern, but it comes with a ponderous burden of its own. Company culture is directly influenced by the country of origin, Zhang wrote. Transferring that culture into a completely different environment can cause the kind of shock that could lead to failure, even with financial and physical resources to ease the geographical distance. Conversely, smaller firms may be more nimble and able to adapt to needed cultural changes — but lack the resources to make true inroads in a foreign market.

A similar paradox exists for older and younger firms, Zhang wrote. A younger firm is more likely to adapt to a culturally distant country than an older firm might, even if that youth means that geographical distance is a greater logistical challenge.

State-owned firms face a similar paradox, one that comes down to the balance of resources against cultural flexibility. A company with state-generated resources may be better equipped to move a caravan people, machinery and materials to a distant new location. However, state-owned companies often typically lack the internal cultural flexibility to handle expansion to a different environment.

What does this mean for the average manager? Simply that going global demands meticulous weighing of factors. Does your firm have the practical resources to expand overseas? Does your staff have the personal flexibility and willingness to meld company culture with that of a different milieu? It's a truism that major overseas expansions require money and heavy lifting. Less obviously, managers of successful companies must thread a very fine needle: ensuring they have the material resources to get their business overseas physically, while confirming that company culture is light enough on its feet to thrive in day-to-day life in a new place.

------

This article originally ran on Rice Business Wisdom and is based on research from Yan Anthea Zhang, a professor and the Fayez Sarofim Vanguard Chair of Strategy in the Jones Graduate School of Business at Rice University.

Ad Placement 300x100
Ad Placement 300x600

CultureMap Emails are Awesome

UH expands Medical Center footprint with $77M research facility

breaking ground

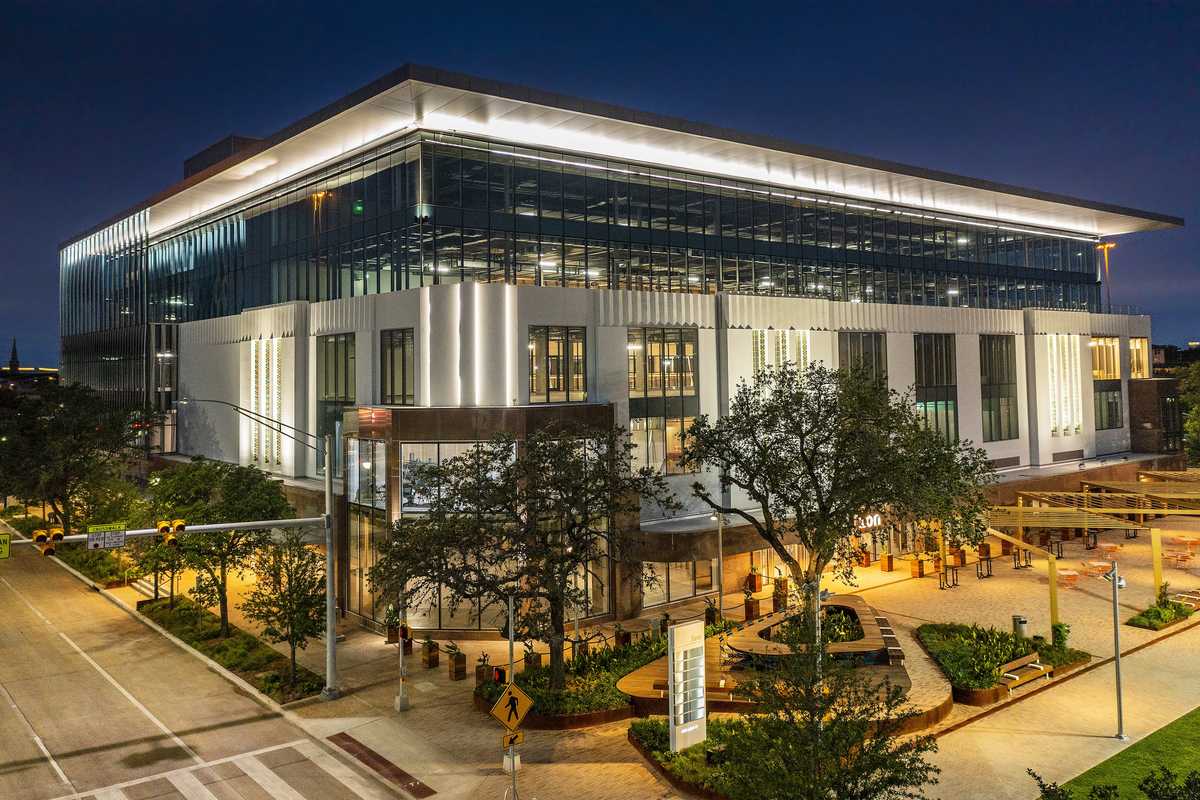
The University of Houston broke ground on a brand new $77.5 million Medical Research Building last week that will host clinical trials and a virtual reality behavioral health suite, among other laboratories. Designed by SmithGroup, it will be the second building on the UH Medical Center campus after the Fertitta College of Medicine opened in 2022.

“The Medical Research Building was designed to foster collaboration and discovery while creating a welcoming environment for students, researchers and the community,” Kalman Nagy, higher education studio design leader for SmithGroup, said in a news release. “As the second building on the University of Houston’s medical campus, we wanted to create a strong connection to the College of Medicine and the surrounding woodlands, with outdoor terraces, shared learning spaces and natural views that inspire interaction and innovation.”

Located just behind the Fertitta building at 5150 Medical Service Drive, the 57,000-square-foot building will house wet laboratories, computational research spaces and specialized facilities for clinical research. The virtual reality behavioral health suite will use immersive technology to deliver care through manufactured audio and visual environments. It’s part of the college’s vision for developing new medical advancements in the heart of Houston’s medical community. The groundbreaking comes on the heels of the launch of the university's cross-disciplinary academic venture, UH Health, this summer.

“This groundbreaking marks an important next step in the growth of the Fertitta College of Medicine and UH Health,” Dr. Jonathan McCullers, vice president for health affairs at UH, added in the release. “We are building the research capacity to match our ambitions—bringing together scientists, physicians and experts from across the University to accelerate discovery and turn promising ideas into solutions that improve people’s lives.”

UH’s journey to establish a significant presence alongside the University of Texas and Baylor in the Medical Center started in 2009 when it became an official full institutional member. The university launched its plans for the Fertitta building in 2013, and is pursuing Health Science Center designation from the Texas Legislature in the next year’s session.

“The research that will take place here will directly benefit our community,” UH President Renu Khator added. “Diseases do not recognize disciplinary silos, and neither should our research. This building will bring together experts from across UH to break down those barriers, work across disciplines and tackle some of our most complex health challenges.”

The building is slated to open in 2028.

Houston ranks among 15 U.S. hot spots for women in tech

Ranking It

Houston is soaring among the best places in the U.S. for women in tech, a new report says. Houston ranked No. 15 nationwide in SmartAsset's new report, "Best and Worst Cities for Women in Tech — 2026 Study," which compared the 50 biggest U.S. cities across four metrics:

  • Gender pay gap — women's median earnings as a percentage of men’s median earnings in tech
  • The share of all tech workers that are women
  • The overall concentration of employment for tech workers, defined as "tech workers as a share of the local workforce"
  • Women tech workers’ median earnings, adjusted for regional price parity
For the purpose of the study, tech workers are defined as "city residents employed in computer and mathematical occupations." The study's findings show that fewer than 9,500 tech workers in Houston are women, or 25.6 percent of the total tech workforce in the city. In total, tech workers in general make up less than 3 percent of the Houston workforce.Despite the high ranking, women tech workers in Houston have a sizeable gap to cross to receive equal pay compared to their male counterparts in the same industry. Women tech workers make just over $97,000 in median earnings after adjusting for regional price parity, which is only 93 percent of what male tech workers make, SmartAsset found.

There are only two U.S. cities where women in tech earn more than what their male counterparts: Miami and Memphis, Tennessee. Women tech workers in Miami make an adjusted $88,650 in median earnings, or 101.7 percent of what men in tech make. In Memphis, women make $84,718 in adjusted earnings, or 101.5 percent of what men in tech earn.

The findings also assert that women remain underrepresented in the nation's overall tech sector, despite making up nearly half of the total workforce. Only 22.6 percent of the country's tech labor force is made up of women, according to the Equal Employment Opportunity Commission."Opportunities for women in tech can vary considerably by location, and these differences shape access to jobs, career advancement and earning potential," the report's author wrote. "In some places, women account for a larger share of tech workers, face narrower pay gaps and enjoy a stronger local labor market. In others, they may encounter a more challenging career environmentThe six other Texas cities that earned spots in the report are Austin (No. 6), Fort Worth (No. 26), Dallas (No. 32), Arlington (No. 38), San Antonio (No. 42), and El Paso (No. 49).

The top 10 best U.S. cities for women in tech are:

  • No. 1 – San Jose, California
  • No. 2 – Seattle, Washington
  • No. 3 – San Francisco, California
  • No. 4 – Atlanta, Georgia
  • No. 5 – Baltimore, Maryland
  • No. 6 – Austin, Texas
  • No. 7 – Oakland, California
  • No. 8 – Portland, Oregon
  • No. 9 – Boston, Massachusetts
  • No. 10 – Minneapolis, Minnesota
---

This article first appeared on CultureMap.com.