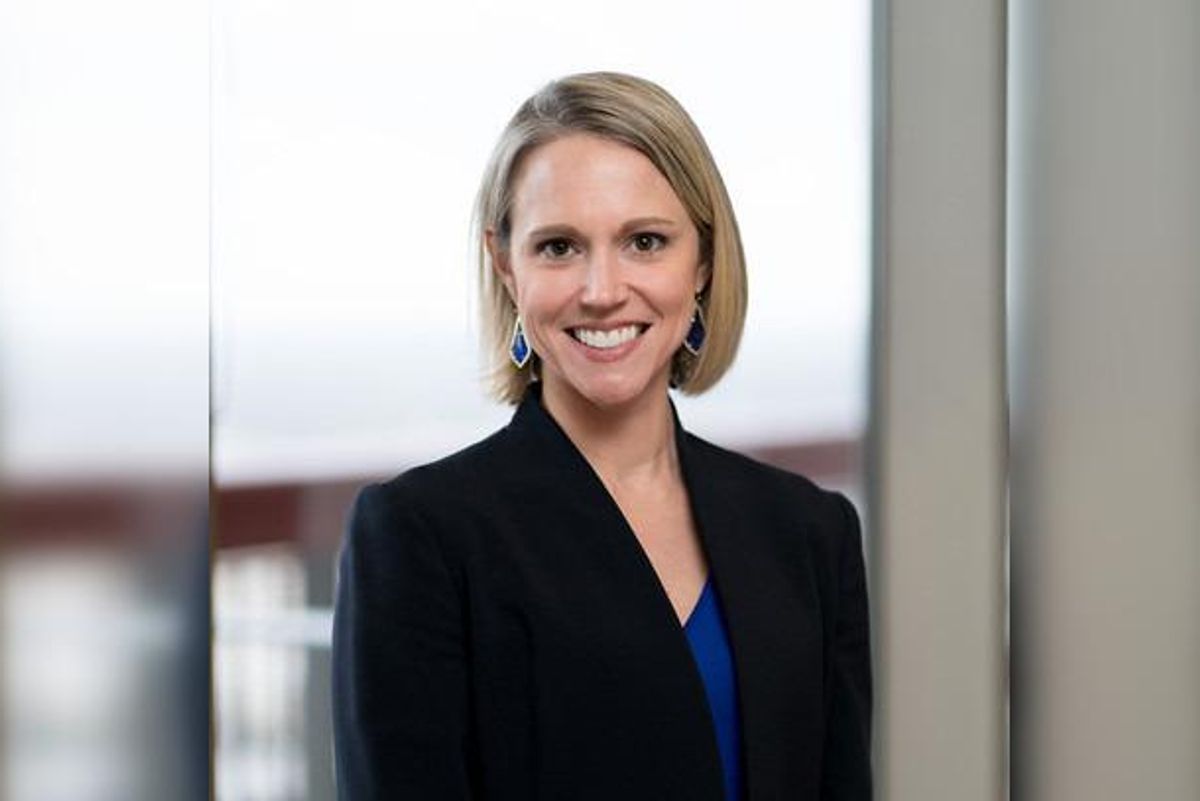
This week's roundup of Houston innovators includes Tim Crain of Intuitive Machines, Chelsea Williams of Northwestern Mutual, and Nicolaus Radford of Nauticus Robotics. Photos courtesy

Editor's note: In this week's roundup of Houston innovators to know, I'm introducing you to three local innovators across industries — from space tech to robotics — recently making headlines in Houston innovation.

Tim Crain, co-founder and CTO of Intuitive Machines
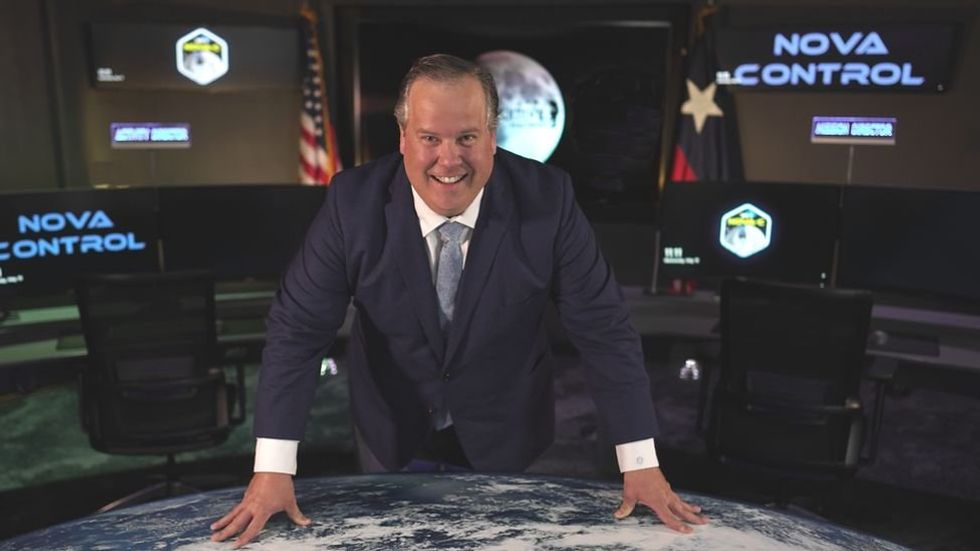
Tim Crain joins the Houston Innovators Podcast. Photo via intuitivemachines.com

It might surprise many to learn that publicly traded, NASA-backed Intuitive Machines, which has emerged as a commercial leader within lunar access technology development, had several pivots before finding its niche within space innovation.

In fact, as Co-Founder and CTO Tim Crain explains on this week's episode of the Houston Innovators Podcast, the company was founded as a space-focused think tank. Crain, along with his co-founders CEO Steve Altemus and Chairman Kamal Ghaffarian, came together in 2013 to start Intuitive Machines, which recently moved into a $40 million headquarters in the Houston Spaceport.

"At the time, our thought was, 'let's take the best of human space flight engineering processes, disciplines, and know how, and look at how we might commercially deploy that for biomedical, energy, big data, and aerospace,'" Crain says on the show. "We wanted to look at how we use great engineering for some of the hard problems outside of NASA's aerospace sphere." Read more.

Chelsea Williams, financial adviser at Northwestern Mutual
Houston-based financial adviser Chelsea Williams helps clients overcome their unique generational financial uncertainties by equipping them with tips and resources to get them on the path to financial wellness. Photo courtesy

In a guest column for InnovationMap, Chelsea Williams, financial adviser at Northwestern Mutual, shared tips on overcoming financial uncertainty across different generations.

"While the types of financial stressors might vary across generations and cities, the most important step to managing financial uncertainty is initiating a conversation with an adviser," she writes in her column. "Just like going to the doctor regularly, routine financial check-ups are incredibly important to catch financial headaches early on and stay ahead of long-term financial health." Read more.

Nicolaus Radford, founder and CEO of Nauticus Robotics
Houston-based Nauticus Robotics founder, Nicolaus Radford, celebrated an acquisition for his company. Image via LinkedIn

A Houston company that harnesses the power of robotics hardware and programing for underwater use has made an acquisition.

Nauticus Robotics Inc. (NASDAQ: KITT) announced it has acquired 3D at Depth Inc., a Colorado-based company with a subsea light detection and range, LiDAR, technology for inspection and data services. The deal closed for approximately $34 million in stock, before certain purchase price adjustments and the assumption of debt, per the news release.

“The future of subsea services lies in autonomy, data gathering, and analytics,” Nicolaus Radford, Nauticus’ founder and CEO, says in the release. “LiDAR has long since been core to terrestrial autonomy and by adding 3D’s capabilities to the Nauticus Fleet, we enhance autonomous vehicles in the offshore market. This acquisition increases the value of Nauticus’ fleet services and positions the Company to capitalize on data acquisition and analytics for subsea operations.” Read more.
Houstonians in particular expressed more stress than other communities in terms of household finances and physical and mental health. Photo via Getty Images

Houston expert on tips on overcoming financial uncertainty across different generations

guest column

Whether you’re a millennial or baby boomer, financial uncertainty is not limited by age, with new data from Northwestern Mutual’s 2023 Planning & Progress Study revealing that most Americans are losing sleep at night because of it. Houstonians in particular expressed more stress than other communities in terms of household finances and physical and mental health, according to a recent survey.

While the types of financial stressors might vary across generations and cities, the most important step to managing financial uncertainty is initiating a conversation with an adviser. Just like going to the doctor regularly, routine financial check-ups are incredibly important to catch financial headaches early on and stay ahead of long-term financial health.

As a Houston-based financial adviser, I help my clients overcome their unique generational financial uncertainties by equipping them with tips and resources to get them on the path to financial wellness.

Understanding where financial uncertainty comes from generationally

  • Gen Z: Studies have shown that even while Gen Z is the most confident that they’ll be prepared for retirement when the time comes, they still struggle with feelings of uncertainty on how to achieve their specific financial goals. In my experience, I have found that uncertainty among this age group often stems from a lack of financial literacy surrounding their finances. A recent financial literacy study revealed that Gen Z respondents averaged the lowest at 43 percent in answering finance-related questions correctly.
  • Millennials: Millennials equally suffer from feelings of anxiety about money, with 54 percent of millennial respondents in the P&P study indicating that financial anxiety causes them to feel depressed compared to just 20 percent of baby boomers. Millennials have lived through a pandemic, The Great Recession and slow economic growth, making their mental health and financial wellness a top priority.
  • Gen X: Even while financial uncertainty typically starts to recede later in life at this age, Gen X is facing a turning point as they get closer and closer to retirement. Studies have shown that most Americans believe they will need about $1.27 million to retire comfortably and yet, I see many individuals only recognizing the importance of retirement planning between the ages of 40 and 50. With Gen X holding about six times more debt than their parents did at that age, it’s important for this age group to consider some proactive debt and retirement strategies.
  • Baby boomers: This group has the lowest amount of financial uncertainty, but that doesn’t mean it is nonexistent. I hear a lot of baby boomers state that they wish they had started investing sooner or they wish they had conversations about their finances sooner. As such, this group is typically the most concerned about managing their existing assets and living comfortably for the rest of their lives.

Overcoming financial uncertainty

  • Increase financial literacy: Both millennials and Gen Z grew up in the digital age and expect their financial experiences to be reflective of that. For employers with Gen Z employees, working with a Northwestern Mutual financial adviser on resources to increase financial literacy can be a helpful first step. This could include on-demand webinars, digital toolkits and interactive online portals to access and view their finances.
  • Ensure every dollar has a job: Across all generations, it’s important to ensure no dollar is wasted. In other words, understanding how much of your income should be allocated toward expenses, retirement, savings, etc. is crucial. I typically recommend a budgeting rule that no more than half of an individual’s income goes toward expenses.
  • Initiate financial planning discussions early on: While it may seem daunting, results from the P&P study show that an average of 76 percent of individuals who work with a financial adviser have an overall boost to confidence. With Gen Z often heavily relying on family members for money management, it is important that family members from older generations encourage them to start saving or to consult with a financial adviser at a young age.
  • Take proactive steps toward your finances: No matter what age you are, there are always active steps you can be taking with your finances. Consider increasing the contribution amount to your 401(k) savings plan or working with a financial adviser to diversify your existing investments – or talk to your financial adviser about refinancing opportunities or debt strategies that tackle higher interest loans you may have.

Whether you’re in your 20s or your 50s, financial advisers are uniquely prepared to help you at any stage of your life – and overcome whatever uncertainties you may be facing.


------

Chelsea Williams is a financial adviser at Northwestern Mutual. She's based in Houston and has clients across the country.

Small businesses need to factor in employee benefit options from day one — and this Houston expert has some tips. Photo via Getty Images

Houston wealth management adviser weighs in on benefit options as key for small business success

guest column

While Small Business Appreciation month has come to an end, my work in aiding small businesses achieve financial success is continuous.

In 2009, I began my career as a financial adviser recently co-founded Volante Integrated Planning, a Houston-based office of Northwestern Mutual focused on comprehensive financial planning and helping clients achieve financial freedom.

After years of working with business owners, and as a small business owner myself, I have learned the importance of offering benefits that help attract and retain talent, foster improved work habits and provide a foundation for growth. According to the annual SHRM employee benefit survey, health-related benefits and retirement plans were ranked the two most important benefits for employees. Whether you are a new small business owner or an established one, it is important to be aware of the benefit options available to you and the considerations that go into mapping out a benefits strategy.

1. Retirement plan options

The most common retirement plans available to small business owners are 401(k), simplified employee pension (SEP) IRA and savings incentive match plan for employees (SIMPLE) IRA. The SEP IRA and SIMPLE IRA provide employers the ability to save on a pre-tax basis. While there are some required contributions on behalf of any full-time employees, the SEP and SIMPLE IRA’s are often recommended for the self-employed or businesses with part-time or contract employees. The 401(k) also provides employers with a pre-tax savings opportunity and the ability to save on a Roth basis. Because a 401(k) requires additional administration and ongoing requirements, it is often a valuable tool for business owners who have more full-time employees.

2. Health care benefit options

According to the Affordable Care Act, companies with fewer than 50 employees are not required to provide health insurance. However, offering a competitive health insurance benefits package is an increasingly important strategy to help boost both new employee acquisition and retention. Following the global pandemic, health benefits have become increasingly important. According to a study by McKinsey & Company, 51 percent of employers now offer health care benefits to attract new employees with dental, vision, and short-term disability as the most important for job-seekers.

Not only are these benefits of importance to employees, they provide protection for business owners by ensuring good health and protection from illness-related lost productivity. Some health care benefits available to small business owners include health reimbursement accounts, where you make contributions to an account that can be used by employees to pay for individual health insurance policies acquired on their own. Consider hiring a broker, benefits consultant or financial adviser to help compare your options.

3. Life and disability insurance options

As a small business owner, you have a duty to your family, employees and business partners. It is often the unexpected that can derail the success of a business. To that extent, taking the steps to ensure you and your business are protected if you are unable to work is important. Disability insurance is a versatile product that can be used to protect you, as the owner, and your employees against loss of income due to the inability to work. Additionally, disability overhead coverage and disability buy-out insurance can protect the business and any business partners from an owner’s disability, ensuring that the business can still run smoothly. Life insurance is also important, and often required if seeking a business-related loan, to provide income replacement for your family and any business partners in the event of an owner’s death.

4. Get creative with your benefit options

The small business world is ever changing, which is why it is essential — and sometimes difficult — to keep up with benefit options. I encourage small business owners to get creative with their benefit options by exploring a professional employer organization (PEO) and a multiple employer welfare arrangement (MEWA). PEO is designed to help small businesses manage their administrative overhead, benefits and compliance duties. Through MEWA, small businesses are able to collaborate on group insurance benefits for a low cost. Lastly, if your family members contribute to your small business, make sure they are on the payroll and eligible for various benefits. This may allow you to increase the benefits your household takes home.

While creating a small business employee benefits plan can be tedious, it will take your small business to the next level. Consult in a CPA, business attorney, and financial adviser to help navigate what benefits are a good fit for you and your small business.

----

Jennifer Steil is principal and wealth management adviser at Volante Integrated Planning, a private client group at Northwestern Mutual.

This week's roundup of Houston innovators includes Stuart Corr of Pumps & Pipes, Trevor Best of Syzygy, and Jennifer Steil of Northwestern Mutual. Photos courtesy

3 Houston innovators to know this week

who's who

Editor's note: In this week's roundup of Houston innovators to know, I'm introducing you to three local innovators across industries — from clean energy technology to financial planning — recently making headlines in Houston innovation.

Stuart Corr, executive director of Pumps & Pipes

What do Houston's three key industries — aerospace, medicine, and energy — have in common? Pumps and pipes, Stuart Corr explains. Photo via pumpsandpipes.org

Stuart Corr, executive director of Pumps & Pipes, and his team are gearing up for the organization's big annual event — which is returning to its in-person capacity. Though most people would not connect the dots on what all the health care, energy, and aerospace industries have in common, but for Stuart Corr, the connection is clear. It's all a bunch of pumps and pipes.

The Houston organization was founded in 2007 to strengthen the collaboration across Houston's three key industries. The city has NASA down the street, the world's largest medical center, and is regarded as the "energy capital of the world." Through the Pumps & Pipes network, innovators across these entities can share resources and collaborate.

"Pumps & Pipes is all about our network — about innovation on demand. It's the idea that we understand what's in other people's toolkits and innovation and technology portfolios," Corr says on this week's episode of the Houston Innovator Podcast. "Ideally, we want to use these new technologies to solve our own problems."

The event is on December 5 at the Ion. Tickets are on sale now. Read more.Read more.

Trevor Best, co-founder and CEO of Syzygy Plasmonics

Syzygy Plasmonics has raised a series C round of funding. Photo courtesy of Syzygy

Houston-based Syzygy Plasmonics closed a $76 million series C financing round led by New York-based Carbon Direct Capital.

The investment funding raised will help the company to "further development and delivery of all-electric reactor systems that eliminate fossil-based combustion from chemical manufacturing and reduce the carbon intensity of hydrogen, methanol, and fuel," per a news release.

"Closing this fundraising round with such strong support from financial and strategic investors and with commercial agreements in hand is a signal to the market," Syzygy Plasmonics CEO and Co-Founder Trevor Best says in the release. "Forward-thinking companies have moved beyond setting decarbonization goals to executing on them. Syzygy is unique in that we are developing low-cost, low-carbon solutions to offer across multiple industries." Read more.

Jennifer Steil, wealth management adviser for Northwestern Mutual

In observance of Women’s Entrepreneurship Day on November 19, a Houstonian shares her four key considerations for women who want to start their own businesses. Photo courtesy

Saturday was Women’s Entrepreneurship Day, and one Houston-based financial planner shared some tips and considerations for aspiring female founders.

In her guest column for InnovationMap, Jennifer Steil, financial planner for Northwestern Mutual, explained the importance of authenticity and advice on building the right team and support network.

"Being a female business owner has its challenges, but it is also extremely rewarding. If you’re considering starting your own business, it’s important to remember to stay true to yourself and do your due diligence to prepare for whatever unique challenges may be thrown your way," she writes. Read more.

In observance of Women’s Entrepreneurship Day on November 19, here are four key considerations for women who want to start their own businesses. Photo via Getty Images

Houston expert: 4 things female founders should know before starting a business

guest column

Almost four years ago my business partner and I started Volante Integrated Planning, a Houston-based office of Northwestern Mutual focused on comprehensive financial planning. I always aspired to run a business; however, I knew there were many factors to consider before making that leap.

According to the 2022 Northwestern Mutual Great Realization survey, 24 percent of respondents say they want to start a new business in the next two years. While starting your own business sounds appealing, leaving your current job and becoming an entrepreneur can be a difficult transition — and it’s no secret that women have to approach our career paths differently than men.

As I recognize there is no one-size-fits-all approach to starting and managing your own business, I wanted to share a few valuable lessons and key takeaways that I learned from my own experience:

1. Seek advice and counsel

When it comes to starting your own business, it’s important to go through the proper financial and legal steps. In order to do this, there are three people you should consider developing a relationship with. The first is a financial planner who can assist you in growing your business by creating a budget and finding ways to leverage your current assets to set you up for long-term success. The second is a Certified Public Accountant who has experience in your industry to help you navigate the unique intricacies of being a business owner. Lastly, an attorney who can help you draw up the necessary documents and think through what needs to be included to protect you and your family.

2. Build your team

You will always need a support system and business team to lean on no matter how much experience you have in your industry or in running a business. I knew early on that I wanted to partner with someone to make it more fun and add higher value to our clients. Before launching our business partnership, we went through varying business cycles together to ensure we would mesh well, from a value standpoint, both financially and personally. This business “courtship” is critical to ensure you build the kind of trust needed. It is also important to develop the culture and values you want for your business first and choose partners or team members that align with those values.

3. Don’t be afraid to be authentic

People are drawn to authenticity rather than if you try to fit into a box, which is why it’s important to stay true to yourself in all aspects of your business. By being your true, authentic self, you can put a plan in place to start a business that is a reflection of your values and morals. If being a working mom is a part of your identity, don’t be afraid to make that known to the team. There is nothing that says you have to start a business a certain way, so make it yours and own it.

4. Give yourself grace

As women, we have a tendency to want to do it all, but it’s important to give yourself grace and be intentional with how you prioritize your time. There are certain life factors and considerations that ultimately influence how women prepare for their financial futures, especially when it comes to running a business. If starting or managing your business is the priority at the time, it’s OK to let your social life or fitness routine, for example, take the back burner for a period of time.

Being a female business owner has its challenges, but it is also extremely rewarding. If you’re considering starting your own business, it’s important to remember to stay true to yourself and do your due diligence to prepare for whatever unique challenges may be thrown your way.

------

Jennifer Steil is a Houston-based Northwestern Mutual wealth management adviser.

One in two Houstonians say they have a great business idea — and two-thirds have gotten the ball rolling on making their idea a reality. Getty Images

New data shows over half of Houston has an idea for a business

City of innovation

If you're sitting on a game-changing business idea, you're not alone. According to data from Northwestern Mutual, over half of Houstonians surveyed said they they've got something up their sleeves for a startup — and a third of that group said their idea has the capability to change the industry.

Of the respondents who said they had a business idea, almost 60 percent have already taken first steps to making their idea a reality. But for those yet to take a plunge, the factors holding these aspiring entrepreneurs back were primarily financial. More than 60 percent said not having enough finances were what's stopped them from taking the next step, while over a third indicated that they weren't sure what their next step would be. About 30 percent identified the fear of failure as what's held them back.

Similarly, when asked what the biggest hurdle in starting a company for their business idea, almost half of those surveyed said financial support, followed by "making money" with 17 percent. Of course, that's what Carrie Neumann, director of Multicultural Market Strategy at Northwestern Mutual, expected. Enter: Northwestern Mutual's financial advising services.

"A personalized, holistic plan sets business owners on track to achieve their goals, and it also puts protections — for the business, the owner and current or future employees — in place for the expected and unexpected," says Neumann in a release.

"For entrepreneurs, a trusted financial adviser is not only a great resource for the many questions that come up when starting a business, but an adviser can also help plan for the longterm."

Northwestern Mutual conducted a survey in partnership with OnePoll with a sample of 8,000 individuals in the United States. Houston was one of the 12 major metros included in the survey — and the lone Texas city. The other cities included in the survey were Chicago; Cincinnati; Denver; Miami; New York; Los Angeles; Omaha, Nebraska; Raleigh, North Carolina; Richmond, Virginia; San Francisco, and Washington D.C.

Houston skewed a tad more ambitious than the other metros surveyed. Across the sample, 41 percent of survey respondents said they have an idea for a business compared to Houston's 51.4 percent. Miami, New York City, and Los Angeles all had a higher percentage of respondents that said they had a great business idea. Los Angeles had over 60 percent of its surveyed participants respond affirmatively to that question.

The city of Houston has its advantages for entrepreneurs. A recent study shows that salaries stretch further in Houston, with the Bayou City ranking as No. 7 nationally. The study conducted by BusinessStudent.com factored in average pay of common jobs and the cost of living.

Ad Placement 300x100
Ad Placement 300x600

CultureMap Emails are Awesome

5 Houston deep tech startups pushing the boundaries of their industries

meet the finalists

Houston has long been at the forefront of innovation, from NASA’s Johnson Space Center to its startup ecosystem using technology to disrupt industries.

As part of the 2026 Houston Innovation Awards, our Deep Tech Business category will honor an innovative startup providing technology solutions based on substantial scientific or engineering challenges, including those in the AI, robotics and space sectors.

Five deep tech companies have been named finalists for the 2026 award.

Read more about these businesses, their founders and their breakthrough technologies below. The 2026 winners will be announced on InnovationMap.com in mid-November.

Casimir

Battery tech startup Casimir develops semiconductor chips that produce continuous electrical power straight from the quantum vacuum, without the need for a battery, cord or external charge source. The company is targeting commercialization for its first-generation MicroSparc chip by 2028.

Harold “Sonny” White founded Casimir in 2023 after nearly two decades at NASA. The company emerged from stealth with a $12 million seed round in 2026. It was also awarded an STTR Phase I contract from the U.S. Space Force's SpaceWERX to support the development of the company's solid-state generator for potential use by the Department of the Air Force earlier this year.

FocisAI

Artificial intelligence startup FocisAI helps refinery owner-operators unlock actionable insights from 3D scans and images.

FocisAI was founded by CEO Tyler Wooten, COO Colin Snell and CTO Kyle Snell in 2026. It is a member of Greentown Labs and launched a seed round in September, which is expected to close by the end of the year, according to the company's application. It has rolled out 10 pilot programs and is looking to move into recurring, facility-scale deployments and scale its team in Houston this year.

Machine Saver Inc.

Industrial tech startup Machine Saver Inc. builds wireless and wired vibration and proximity sensors to tell heavy industry when a machine is about to fail. The company's technology runs on an 8-plus-year battery life and helps operators reduce downtime, improve maintenance and extend equipment life.

Machine Saver was founded by CEO Colton Bach and Quentin Bach in 2013. Its customers and partners include Houston Methodist, Blue Bell, Genemco, as well as energy and heavy industry, food and beverage, and cold chain companies, according to its application. The company is raising a Series A.

Square Robot

Energytech startup Square Robot develops and operates submersible inspection robotics that inspect aboveground storage tanks while they remain in service. The robots reduce downtime and costs, improve worker safety and limit hydrocarbon emissions.

Square Robot launched its Houston office in 2019 and closed a Series B in 2025. It plans to complete its first U.S. Navy demonstrator tank in November and is also developing real-time inspection software.

Venus Aerospace

Spacetech company Venus Aerospace is developing a high-thrust rotating detonation rocket engine (RDRE) that replaces the subsonic combustion used in conventional rocket engines. The RDRE is a compact, simpler engine that can deliver up to 15 percent greater efficiency for defense and space applications. It completed its first U.S. flight test of the engine last summer.

Venus Aerospace was founded in 2020 by CEO Cassie Duggleby and CTO Andrew Duggleby. It raised a $20 million Series A in 2022 and $42 million Series A2 in 2025. It closed a $91 million Series B earlier this year and expanded its leadership team. The company is working toward longer-duration and higher-thrust testing and advancing its flight program.

Houston leads U.S. with the biggest surge in millionaire renters

Rent Report

The number of millionaire renters and homeowners in the U.S. has surged over the last five years, and Houston has soared ahead of the rest with the largest growth rate among these affluent renter households.

Houston leads the nation with the No. 1 increase in millionaire renters from 2020 to 2024, a new RentCafe study found. The number of these wealthy households increased from 18 to 232 over the last five years, representing a 1,189 percent growth rate.

"The pandemic accelerated the shift as remote work pushed the wealthy to relocate to lower-tax metros like Houston, where millionaire renters grew 13-fold, versus 3.9-fold for owners," the report said. "Granted, 232 households is still a tiny fraction of the Houston metro’s roughly 2.7 million households, but the growth rate far outpaces any other major metro."

Nationwide, the number of millionaire renter households grew 229 percent from 2020 to 2024, outpacing the 193 percent growth rate among millionaire homeowners.

Dallas was the only other Texas metro to crack the top 10. The number of millionaire renter households in North Texas has more than quintupled, from just 30 in 2020 to 165 in 2024. That represents a growth rate of 450 percent, which — surprisingly — is only the eighth highest nationwide.

But when it comes to the largest populations of millionaire renters, New York City and San Francisco still lead the way. New York claimed the No. 1 spot with nearly 7,300 millionaire renters living in the city in 2024. Houston ranked 12th on that list.

Elsewhere in Texas, Austin and Dallas ranked as the 16th and 17th, respectively, for the largest population of millionaire renters. There were 206 millionaire renters living in Austin in 2024, and 165 in Dallas.

This is who the typical millionaire renter is
The report also revealed a surprising statistic about the typical millionaire renter in the U.S. — a lot of them are millennials working in "white-collar, high-earning fields."

"Nearly half (49 percent) of millionaire renters are Millennials, and the number of affluent Millennial renter households surged 392 percent during the five-year period," the report said. "Gen X follows with 33 percent of millionaire Gen X households renting after increasing by 147 percent."

The report continued, "Although Gen Z still represents a small share of millionaire renters (just 2 percent of the total), no generation has expanded faster: Gen Z millionaire renter households leaped from fewer than a dozen to more than 400 — a tiny cohort today, but one that was virtually nonexistent five years ago."

The top three most common professions for millionaire renters are chief executives, software developers, and managers, the report additionally found. In Houston, the surge of wealthy newcomers are mostly executives, professional athletes, and entertainers.

"These roles tend to generate steady, substantial income without necessarily tying workers to one location, making renting a practical fit, rather than a financial necessity," the report said.

Hotspots for millionaire homeowners
In RentCafe's separate list comparing the top 10 most popular U.S. metros for millionaire homeowners, Houston ranked 12th nationally with 4,374 millioniare homeowners living in the metro as of 2024. These wealthy Houstonians are most likely working as chief executives, physicians, managers, and lawyers and judges.

Houston has already proven to be a hotspot for millennial homebuyers, and the latest RentCafe data says millennials make up 19 percent of all millionaire homeowners in the U.S. Gen Xers and Baby Boomers still maintain the largest shares of millionaire homeowners nationwide, at 45 and 33 percent, respectively.

Dallas (No. 10) and Austin (No. 20) also appeared among the hottest metros for millionaire homeowners.

Only one Texas city appeared among RentCafe's list of the 20 fastest-growing metros for millionaire homeowners: College Station ranked 13th nationwide with a growth rate of 1,329 percent. From 2020-2024, the number of millionaire homeowners residing in College Station grew from 14 to 200.

---

This article originally appeared on CultureMap.com.

Houston ranks high on best cities for small-business expansion report

business growth

For small businesses looking to expand, Houston might be the right place.

Among 56 major U.S. metros, Houston grabbed the No. 6 spot on a new list of the metros boasting the strongest environments for small-business expansion.

A 2025 report from the state comptroller’s office showed roughly 970,000 small businesses operate in the 13-county Gulf Coast region. The region includes the majority of the Houston metro area.

“Whether it’s a family-owned shop on Main Street or a fast-growing startup, small businesses power our state’s economic engine, create opportunity, and strengthen the character of every Texas community,” Kelly Hancock, who was interim state comptroller when the report was released, said in a press release.

Business lending platform Clarify Capital analyzed five factors to develop the list: job growth, business entry and exit, net job creation, and unemployment.

Overall, the Nashville area claimed the No. 1 spot on the list. Other major Texas metros also cracked the top 10, including Austin at No. 3 and Dallas-Fort Worth at No. 7.

“The highest-ranking metros combine labor-market momentum with steady business formation and relatively favorable local employment conditions,” Clarity Capital says.

The Houston metro ranked sixth for job growth, 11th for business entry rate, 38th for business exit rate, second for net job creation rate, and 50th for unemployment rate.

“For business owners, the ranking is a starting point rather than a guarantee,” Clarify Capital says. “Local demand, competition, operating costs, and access to capital still shape whether an expansion works.”

“Building enough cash-flow room for hiring, equipment, and unexpected expenses can help small and midsize business owners take advantage of a strong market without stretching the business too thin,” the company adds.

Of course, money fuels small-business expansion in the Houston area or anywhere else.

According to an analysis of SBA loan data by feasibility consulting firm MMCG, the Houston metro area saw 1,685 approvals for 7(a) loans and 101 approvals of 504 loans in the federal government’s 2025 budget year. The approval numbers for both loan categories increased from the previous year.

Altogether, the 7(a) and 505 loans exceeded $1 billion.

The data from the U.S. Small Business Administration suggests small-business expansion may be on the rise in the Houston area.

Further potential evidence of small-business expansion in the Houston area: The region experienced a 92 percent rise in account applications from 2024 to 2025 submitted to Bluevine, a small-business banking platform. The Houston metro ranked fifth for the number of Bluevine small-business applications in 2025.