From oil and gas deals to finance-focused initiatives, this week's innovators are ones to watch. Courtesy photos

As Houstonians head back to work or school following a fun summer break, we know two things for sure.

The first is that traffic will get back to its headache inducing craziness and that Houston startup news will only get more frequent. This week's innovators to know include oil and gas entrepreneurs with big deals on the line plus a finance-savvy woman who wants to encourage others to take control of their personal finance.

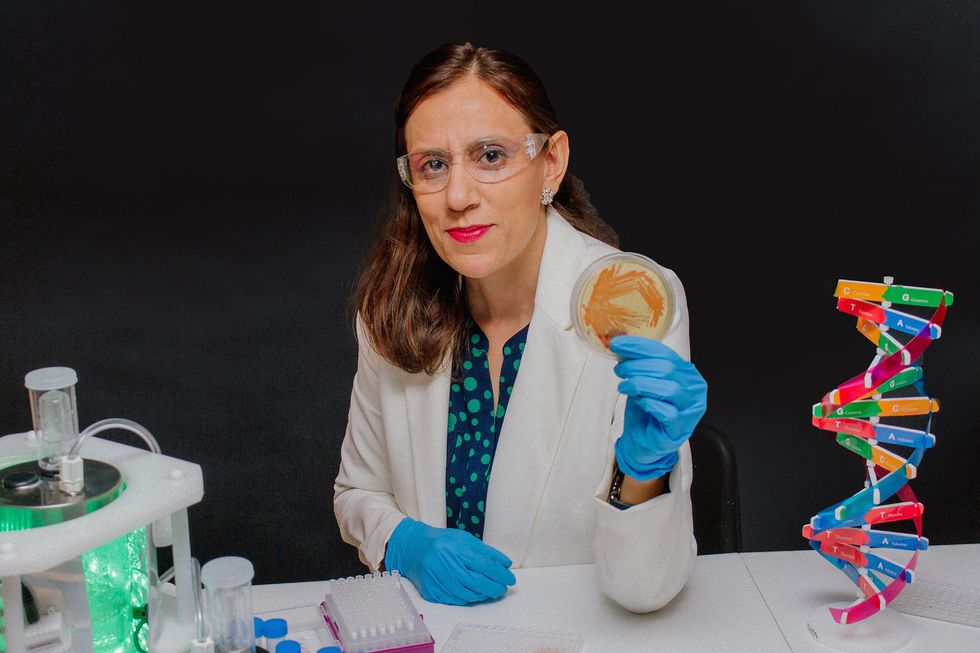
Tara Karimi, co-founder and chief scientist at Cemvita Factory
Cemvita Factory

Courtesy of Cemvita Factory

A brother-sister team has taken a huge step forward with their biotech startup, Cemvita Factory. Moji Karimi, who has a background in the oil and gas industry, and his sister, Tara, who has a background in biotech, teamed up a few years ago to create a technology that can mimic photosynthesis, turning carbon dioxide into glucose. It was Tara who figured out the technique and then the two worked backward to identify the industries — oil and gas and space — to work within.

Now, Cemvita is celebrating an investment from an Occidental Petroleum subsidiary — Oxy Low Carbon Ventures LLC.

"We have an ambitious goal to take one gigaton of CO2 out of the carbon cycle in the next decade and are very excited about being a part of Occidental's journey to become a carbon-neutral company," says Tara, co-founder and chief scientist, in a release.

Read more about Cemvita Factory here.

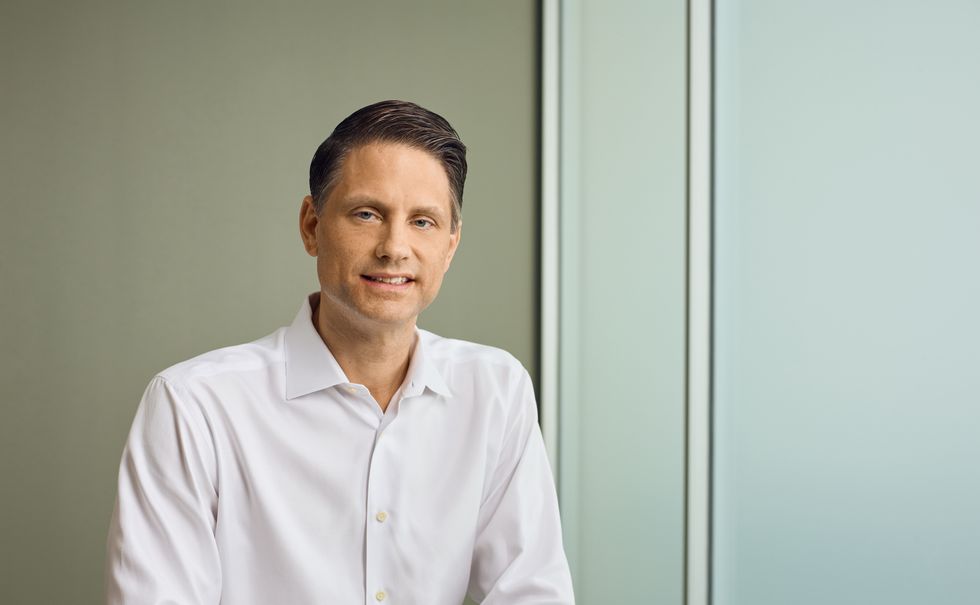
Travis Parigi, founder and CEO of LiquidFrameworks
Courtesy of LiquidFrameworks

Travis Parigi has built his software company from the ground up. Now, for the first time, he's thinking strategically about growth, thanks to a new financial partner.

Parigi's company, LiquidFrameworks, is an enterprise software company with applications in the upstream and downstream services industry. While the software focuses on automation and AI applications, Parigi tells InnovationMap that he has his eyes on emerging technology all the time. I keep a keen watch on a lot of the different technologies that are emerging out there.

"Blockchain is certainly one of them that we're looking at," Parigi says. "I think there's some interesting things that we might be able to do with that as it relates to price book management, which is complex and varied. It could be that blockchain could end up providing a nice mechanism for both parties to independently have pricing data verified."

Read more about Parigi and LiquidFrameworks here.

Eryn Schultz, co-founder of pHERsonal Finance Day
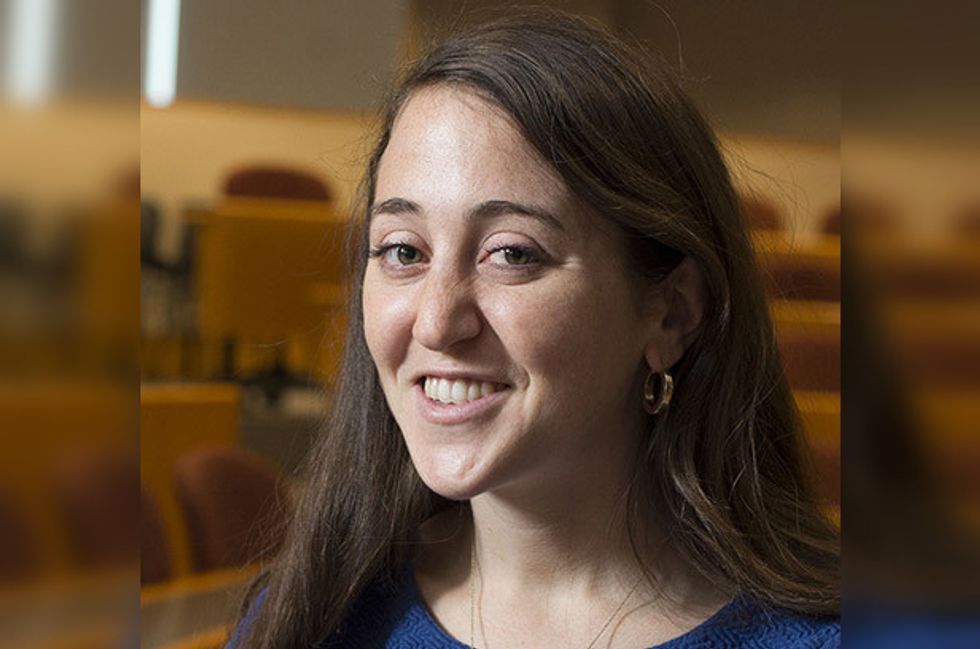
Courtesy of pHERsonal Finance Day.

Eryn Schultz wanted to encourage women to take control of their finances. So she created her own holiday for it called pHERsonal Finance Day. She hosted Houston panels and talks on the day — Friday, August 23 — and motivated women everywhere to take a moment and make a smart financial plan.

"In a world of women's marches and the 'Future is Female' t-shirts, women should be stepping up to shape their financial futures," Schultz writes in a guest column for InnovationMap. "For that reason, women should take a financial health day."

Schultz had a great turnout and reception for the Houston event, and she's already planning for next year.
Read more about pHERsonal Finance Day here.

August 23 is pHERsonal Finance Day — a day dedicated to education about financial practices for women. Getty Images

Why women should take a personal finance day from this Houston founder

Guest column

You've seen the statistics on Americans' financial health. The average American is not in great shape: $6,000 per person in credit card debt, $4,900 per person in student loan debt, and 51 percent of all workers who feel they aren't saving enough for retirement.

You also probably know about two other trends: women are living longer than men and divorcing at higher rates. What you may not know is that in 2019, most married women still say their husbands manage their finances. Even more surprisingly, millennial women have their husbands manage their financial futures at higher rates than their mothers. According to a 2017 UBS survey, 61 percent of millennial married women say their husbands manage their finances versus 54 percent of boomers. How do these trends come together?

Each year, there are two million American women who get divorced or widowed. These women grapple with a traumatic life event while trying to figure out the passwords to their investment accounts. In addition, married women are waking up to discover their retirement savings are short of their expectations. In a world of women's marches and the "Future is Female" t-shirts, women should be stepping up to shape their financial futures. For that reason, women should take a financial health day.

What's a financial health day? It's 24-hours where you take the day off work or dedicate a Sunday to writing down the balances of your investment accounts, renegotiating your auto insurance, and deciding if you should roll over that old 401K. A financial health day is not going to magically wipe away your student loans or solve your spending problem, but it can give you a plan for paying off debt or your mortgage three years early.

There is growing consensus on what being financially healthy means: you should maintain a four to six-month emergency fund, carry zero credit card debt, and contribute 10 to 20 percent of your monthly income to a retirement fund. Additional goals, like buying a house or paying for your kids' college, don't come until you have achieved a stable foundation.

Along with knowing what "financial health" means, there is also general agreement among financial experts on the best ways to achieve it:

  • Know your money situation. Physically write out your loans (credit cards, auto loans) with their interest rates, and all of your savings (including retirement). Seeing it all in one place will help you figure out your priorities.
  • Create money goals. Set multiple goals and prioritize them (you can also fund more than one goal at once). Is it saving for the down payment on a house or becoming debt free?
  • Track your spending. Where is your money going? There are budgeting apps from Mint or YNAB to help you keep track. Are there places where you can tweak your spending habits to fund your savings goal? Can you cancel a recurring expense you aren't using? Could you negotiate a better rate on your phone bill?
  • Automate to achieve your goals. Set up recurring payments to your debt and savings. Automated monthly transfers from your checking account to your savings goals make sure you aren't as tempted to spend that money. Schedule monthly and yearly calendar alerts to check your spending, rebalance your portfolio, etc. One advanced tip is to enroll in your 401K plan's "save more later" option. This will increase the percentage of your paycheck you put into your 401K annually.

These items seem simple. Yet, why are so few people doing them? It takes a LOT of work to get this money infrastructure set up. At the end of a long day of client meetings, chasing a toddler, or some combo of the two, it's difficult to muster the mental energy to address your finances – especially if you have the option of outsourcing this responsibility to a capable partner. That's where a day dedicated to your financial to-dos will help. You don't need to be solely in charge of your money, but you definitely need to understand the plan.

While we feel that everyone can benefit from a financial health day, the first pHERsonal Finance Day targeted to millennial women is scheduled for August 23. Check out our schedule if you want to get started. If taking a whole day off feels like a long-shot, take this quiz here to help you prioritize your financial to-dos. Whether it's a daily money minute or an appointment with a financial adviser (pick one who is a fiduciary), what are you doing to own your financial future?

------

Eryn Schultz is the co-founder of pHERsonal Finance Day.

Ad Placement 300x100
Ad Placement 300x600

CultureMap Emails are Awesome

University of Houston med school secures full accreditation

med school milestone

The University of Houston’s Tilman J. Fertitta Family College of Medicine has officially earned full accreditation after launching six years ago.

The designation comes from the Liaison Committee on Medical Education, which granted UH the maximum five-year review period available to a new medical school. To achieve the status, the committee reviewed the Fertitta College of Medicine's facilities, faculty and student outcomes, and curriculum to ensure the college met the highest standards in medical education.

“Full accreditation is not the finish line — it’s the foundation for everything we hope to accomplish in the years ahead,” Dr. Jonathan McCullers, vice president for health affairs at UH and dean of the Fertitta College of Medicine, said in a news release. “It strengthens our ability to attract outstanding students and faculty, expand our partnerships and prepare the next generation of physicians.”

Fertitta College of Medicine has graduated three classes of physicians, and every graduate from its most recent class secured a residency position. Enrollment has expanded from 30 students in its inaugural class to 65 students in its current class.

According to UH, about 70 percent of graduates have chosen to remain in Texas for further training, which is key to addressing the estimated 10,000 doctors needed to meet growing needs.

Fertitta College of Medicine opened for its first students in 2020, and now joins 14 other Texas schools as a fully LCME-accredited medical school. It also joins UTHealth Houston's McGovern Medical School and Baylor College of Medicine as one of three Houston-based LCME-accredited campuses.

The news comes after UH launched its health enterprise initiative, UH Health, in July and broke ground on its $77.5 million Medical Research Building next to the Fertitta College of Medicine last month.

“Building a medical school from the ground up is an extraordinary undertaking, and this milestone reflects the dedication of everyone who helped make it happen,” Dr. Stephen Scott, vice dean for education at the Fertitta College of Medicine, added in the release. “From developing an innovative curriculum to establishing the systems and partnerships that support our students, this has been a true team effort.”

Woodlands startup Mavria raises $130M to mass-produce AI data centers

seed funding

The Woodlands-based Mavria, which mass-produces factory-built modular AI data centers, just emerged from stealth mode with $130 million in funding at a $1 billion valuation.

Mavria raised the money in pre-seed and seed rounds led by Paradigm, an investment firm that concentrates on early-stage startups developing “pioneer” technology. Participants in the funding rounds include AMP PBC, Critical Frontier, Dream Ventures and Liquid 2 Ventures, co-founded by former NFL quarterback Joe Montana.

The company’s inaugural product, Terrain, is a prefabricated data center designed for AI labs, cloud computing providers and data center developers. Mavria says its platform avoids ground-up construction, delivering infrastructure more quickly and at a lower cost.

Mavria tells the Wall Street Journal that the first Terrain unit is being built at a Houston-area factory. The 5-megawatt Terrain system features power distribution, direct liquid cooling, controls and server racks.

“America sets the pace at the intelligence frontier. But the race is moving from the lab into the physical world,” Adam Blake, co-founder and CEO of Mavria, wrote in a blog post.

“Intelligence needs data centers. Data centers need power. Power needs factories, equipment, supply chains, and skilled workers, but much of that infrastructure is still built one custom project at a time, on timelines measured in years.”

Blake and Mavria’s two other co-founders, Nick Poradek and Seth Cohen, most recently worked at the U.S. Department of Energy. There, they focused on reforming the nuclear power sector.

From start to finish, it can take roughly three to six years to build a data center at an estimated cost of $10 million to $37 million per megawatt. Based on those figures, a 100-megawatt data center might cost as much as $3.7 billion.

Here are brief bios of Blake, Poradek and Cohen, who co-founded Mavria in May.

Adam Blake

Blake most recently was a senior advisor to U.S. Energy Secretary Chris Wright. He is co-founder and former CEO of Zego, a provider of energy management technology for property managers. Zego spun out from Brightergy, a commercial solar company. Blake is founder and former CEO of Brightergy.

Nick Poradek

Poradek, chief operating officer at Mavria, was also an advisor to the U.S. energy secretary. He is founder and former CEO of Spring-based Edera Energy, co-founder of The Woodlands-based craft-ice brand Clarity Ice, and founder and former CEO of The Woodlands-based Edera Capital. Poradek sold Edera Energy, a manufacturer of oilfield equipment, to Liberty Energy, a fracking company. Wright is Liberty’s founder and former chairman and CEO.

Seth Cohen

Cohen, chief strategy officer and chief legal officer at Mavria, was head of nuclear law and policy at the Department of Energy. He is also a former NASA advisor and a former attorney at Kirkland & Ellis.

“We believe in rapidly deploying infrastructure as a product, rather than custom-building every project,” Blake said. “We’re bringing together engineering, manufacturing, supply chains and capital so that every project makes us better at delivering the next.”