When companies plan to restructure, it makes a difference if the new CEO is hired from inside or outside. Pexels

Star Co. is a hot mess. The business is bloated and sprawling. Its stock is tanking. Profits are down. It's clearly time for a new CEO.

But where to look — inside the company or outside? It's a decision every restructuring company faces.

Cenovus Energy tapped an outsider in 2017. General Electric, the same year, went with a longtime insider. Though it's too soon to know yet for sure, which one likely made the right choice?

Rice Business emeritus professor Robert E. Hoskisson, with coauthors Shih-chi Chiu, then at Nanyang Technological University (now at the University of Houston), Richard A. Johnson of University of Missouri, Columbia and Seemantini Pathak of University of Missouri-St. Louis, set out for an answer: Where is the best place for a restructuring company to get its next CEO?

According to conventional wisdom and some past research, change is more likely under an outside CEO. He or she can start fresh, armed with a greater mandate to shake things up.

Recent evidence, though, suggests that outsiders may actually have more trouble succeeding. That's because they lack the institutional knowledge to make the most informed choices, and the existing relationships needed to ease change with minimal pain. Insiders, this research shows, have the advantage of key "firm-specific" knowledge on everything from customers to suppliers to workforce composition.

To pin down an answer on whether it's better to stay inside or go outside, Hoskisson's team decided to look at corporate divestiture — asset sales, spinoffs, equity carve-outs — as a proxy for overall strategic change. (It's already well documented that a new CEO makes organizational changes such as personnel changes and culture shifts.)

Next, they distinguished between scale and scope. The scale of a divestiture reflects magnitude: How many units were sold? The scope reflects diversification portfolio adjustment: Does the company have fewer business lines?

Focusing on 234 divestitures at U.S. firms that voluntarily restructured between 1986 and 2009, the authors defined a new inside CEO as having been in that role two or fewer years, and with the company previously for more than two years. They defined a new outside CEO as someone who had been at the company for a maximum of two years in any role.

Heading into the analysis, the researchers expected they would reach different conclusions for scale vs. scope. And the results were just that.

New inside CEOs, they found, did carry out more divesture activities than new outside CEOs. Not having as much inside knowledge, the outside CEO was more likely to prefer a simpler divesture plan, one that didn't require evaluating each unit or asset. Instead, the professors hypothesized, an outsider was more likely to follow investors' general preferences about firm strategy.

"When a higher magnitude of corporate divestures is required, internal successors are more astute than external successors in accomplishing this objective," the researchers write. On the other hand, when a company wants to shrink the diversified scope of a business portfolio, "external successors are more likely to bring their firms to a more focused position."

The researchers also suggested future lines of study about new CEOs and strategic change. What happens when firms want to buy and sell at the same time? Does the CEO selection process itself affect restructuring scale and scope? And does an inside chief executive who won a power struggle against a predecessor perform differently than an inside CEO named in orderly succession planning?

In the meantime, the findings are clear. If your corporate board is hunting for a new CEO, it may pay to go for the fresh face. But depending on your goals, your best option may also be a top executive sitting at a desk a few steps away.

------

This story originally ran on Rice Business Wisdom.

Robert E. Hoskisson is the George R. Brown Emeritus Professor of Management at Jones Graduate School of Business at Rice University.
Does your brain have the right components to be an entrepreneur? Getty Images

Rice University research finds certain cognitive factors appear in the minds of entrepreneurs

Houston Voices

The entrepreneur strides into a room of potential backers. Swathed in understated grey, she walks with assurance and chats in the cool, easy-going cadences of the leaders she plans to woo. But will an approach like this really affect the fate of her startup? And if not, what will?

A literature review by Rice Business professor Robert E. Hoskisson and colleagues Jeffry Covin of Indiana University, Henk W. Volberda of Erasmus University and Richard A. Johnson of Arnold & Porter offers clues to a vast range of questions about the entrepreneurs' trade. It also outlines where research still falls short. What, for example, most influences a startup founder's success? Is entrepreneurial triumph driven by innate ability or acquired skill? What's the role of factors such as regulatory structures or an entrepreneur's own work environment?

Traditional research, Hoskisson and his associates note, makes it clear that certain cognitive factors really do differentiate people who start new ventures from their more staid counterparts. And recent scholarship has traced how individual entrepreneurs decide to launch their startups and how they spot entrepreneurial opportunities. Still unclear, though, is whether entrepreneurs think differently overall, possess innate qualities that lend themselves to entrepreneurship or somehow become catalyzed by the entrepreneurial role itself.

More research could help answer those questions. Research is also needed to pinpoint exactly how the best entrepreneurs express their plans in order to sound legitimate enough to earn funding and support, Hoskisson's group says. What the scholarship does show is that that the grey-clad entrepreneur with the easygoing patter knows what she's doing: symbolic language, gestures and visual symbols all help create professional identity, emphasize control and regulate the emotions of a viewer. Setting, props, style of dress and expressiveness all count, and the more experienced the entrepreneur the more props she uses.

At the same time, no unified model fully explains how successful entrepreneurs gain their funding. Models range from the hyper-rational analysis offered by game theory to a stimulus-response model in which people react as if they're marionettes. Other mysteries include how the entrepreneurship impulse arises, how it shapes innovation and competitive advantage and how it is translated in individual actions and interactions. More research in these areas, says Hoskisson, would help not only entrepreneurs in the eternal quest for funding, but also the understanding of how to nurture human potential.

Examining institutional differences among countries and how that affects entrepreneurship is also ripe for study. So far, entrepreneurship research has focused on individual attributes. But there's a need, Hoskisson and his colleagues say, for scholars to connect the dots between startup success and political environments, rule of law, regulation and entrepreneurship.

The same goes for work on diverse contexts in emerging economies. In transition economies, China being one example, networks create political and social capital that allows special access and legitimacy. On the other hand, in those same countries ponderous bureaucracies and basic resource limitations can hamper entrepreneurial projects. Detailed understanding of such cultures will only get more urgent as ventures in emerging economies increase and companies that are "born global" proliferate.

Also on the research to-do list about entrepreneurs: the chances of securing funding in given emerging economies and the power — or frailty — of their intellectual property laws. Regulation, especially, plays a pivotal role in these countries, Hoskisson writes. The lighter the regulation, the more entrepreneurship flourishes, according to one study of 54 countries. On the other hand, countries blessed with a strong rule of law offer entrepreneurs more opportunities for strategic entry.

Understanding the entrepreneurial mind, and its interaction with the material world, isn't simple. Consider the late Texas billionaire H. Ross Perot's plan to send gifts to all POWs in Vietnam during the height of the Vietnam War. Unsurprisingly, the Vietnamese government announced that a gift delivery was impossible while Americans were bombing the country. Undeterred, Perot offered to rebuild anything the Americans had bombed. Rebuffed again, Perot chartered a plane to Moscow, instructing aides to deposit the Christmas presents, one by one, at Moscow post offices, addressed to Hanoi.

Amusing as it can be to hear about such entrepreneurial gumption, it may be even more useful to study entrepreneurship systematically. Not everyone can have an entrepreneur's brain, Hoskisson's review of research suggests, but good scholarship might be able to teach people how to walk the walk.

------

This story originally ran on Rice Business Wisdom.

Robert E. Hoskisson is the George R. Brown Emeritus Professor of Management at Jones Graduate School of Business at Rice University.
Family firms aren't investing in research and development — but why? Getty Images

Rice University research sheds light on what family office investors are looking for

Houston Voices

Family firms are publicly traded companies in which family members own at least 20 percent of the voting stock, and at least two board members belong to the family. For obvious reasons, the central principals in these firms tend to have a longer view than principals in non-family firms. Yet family firms invest less in research and development (R&D) in technology firms than their non-family counterparts. Since investments in R&D are stakes in the future, why this disparity?

Robert E. Hoskisson, a management professor at Rice Business, joined several colleagues to answer this question. Refining a sociological theory called the behavioral agency model (BAM), the researchers defined family-firm decisions as "mixed gambles" — that is, decisions that could result in either gains or losses.

Because success in high technology relies so much on innovation, it's especially puzzling when such a family owned business underinvests in R&D. So Hoskisson and his colleagues focused on the paradox of family firms in high tech.

According to previous research, family owners weigh both economic and non-economic factors when making business decisions. Hoskisson and his team labeled these non-economic factors socioemotional wealth (SEW). SEW can include family prestige through identifying with and controlling a business, emotional attachment to the firm or the legacy of a multigenerational link to the firm.

That intangible wealth (SEW) explained some of the families' R&D choices. While investment in R&D may lower future financial risk, it can threaten other resources the family holds dear. Expanded R&D spending, for instance, is linked with competitiveness. At the same time, it is associated with less family control. That's because to invest more in R&D, businesses typically need more external capital and expertise. So when a family firm underinvests in R&D, it may in fact be protecting its socioemotional wealth.

To further understand these dynamics, the researchers looked at three factors that they expected would raise families' R&D spending to levels more like non-family counterparts.

The first factor was corporate governance. As predicted, the researchers found that family firms with a higher percentage of institutional investors invested in R&D at levels more like those of non-family firms. The institutional investors naturally prioritized economic benefits far more than the founding family's legacy wealth (SEW).

The researchers also analyzed corporate strategy. Family firms, they found, invested more in R&D when it might be applied to related products or markets. Even families bent on preserving non-economic wealth could be lured by a big economic payoff, and related business are easier to control because they are closer to the family legacy business expertise.

Finally, Hoskisson and his colleagues looked at performance. When a family firm's performance lagged behind that of competitors, they reasoned, the owners would spend more on R&D. A higher percentage of institutional investors, the team theorized, would magnify this effect. Interestingly, the primary data (from 2004 to 2009) failed to support this hypothesis, while an alternative data set (from 1994 to 2002) confirmed it.

Further research, the investigators wrote, could shed useful light on this puzzle. They also encouraged study of how family firms conduct mergers and acquisitions. After all, while families can seem inscrutable from the outside, most run on some kind of economic system. The currency just includes more than money.

------

This story originally ran on Rice Business Wisdom.

Robert E. Hoskisson is the George R. Brown Emeritus Professor of Management at Jones Graduate School of Business at Rice University.
Ad Placement 300x100
Ad Placement 300x600

CultureMap Emails are Awesome

Rice University breaks ground on new innovation hub, The Arc

breaking ground

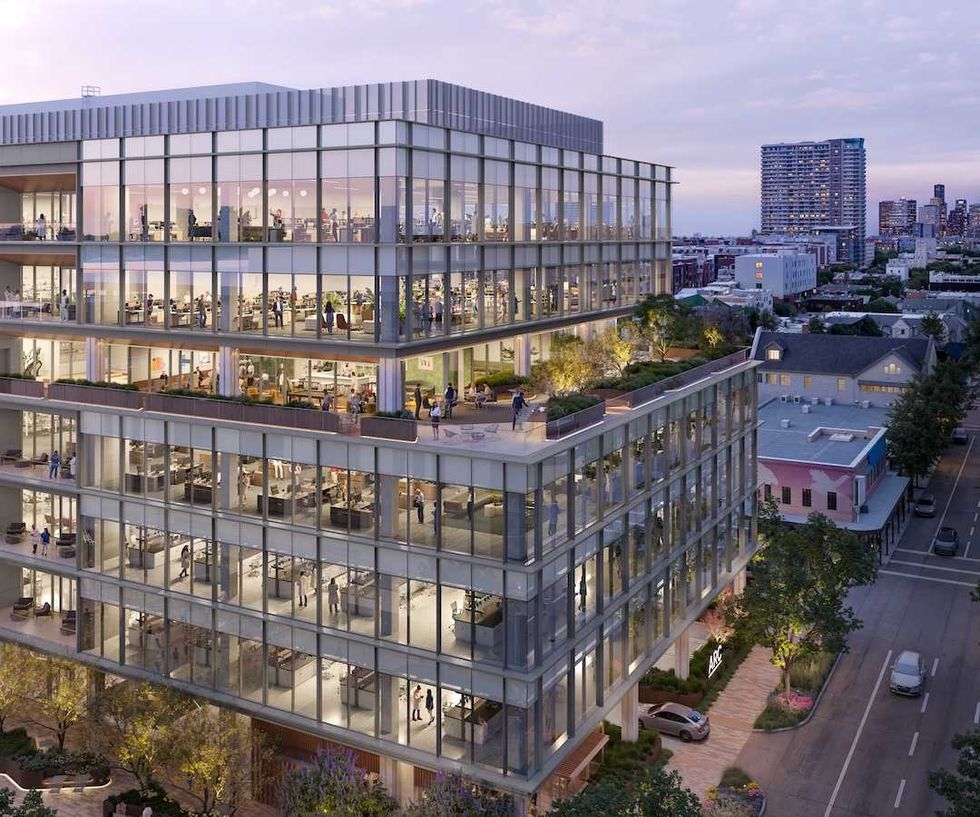
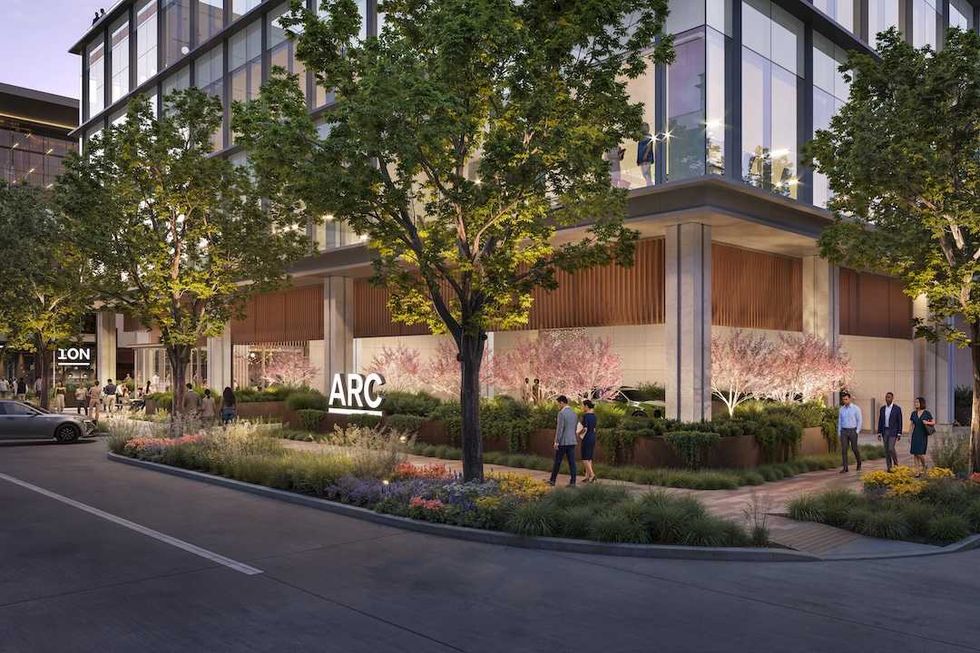
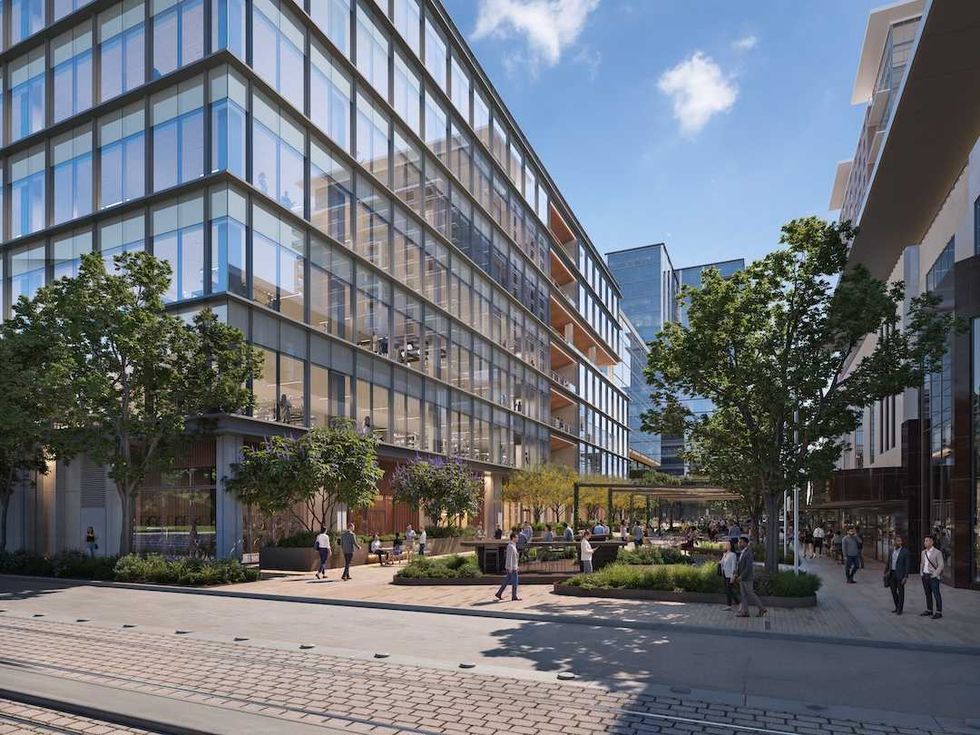
Construction is officially underway on Rice University's The Arc in Houston’s Ion District.

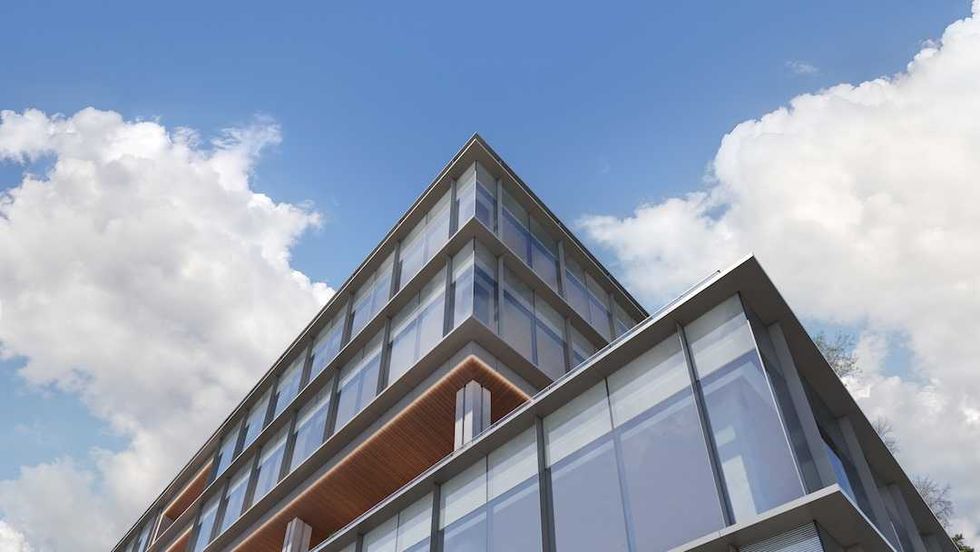
The university broke ground on the 200,000-square-foot research, corporate innovation and office building on Nov. 4. The facility will share a plaza with the existing Ion building, fostering collaboration within the innovation space, according to Rice.

“The Arc will bring Rice’s extraordinary research and talent and Houston’s impactful innovation ecosystem into even closer connection with the industries and innovators working to solve some of the world’s most consequential challenges,” Rice President Reginald DesRoches said in an announcement. “That constant exchange of ideas and expertise will help move discoveries more rapidly from the laboratory to real-world impact.”

Construction is scheduled to be completed by Q2 2028. Rice Real Estate Co. is developing the project, and Rice University will occupy about 80,000 square feet in the building (about 40 percent). Preleasing has begun, with floor plans ranging from 28,000 to 31,000 square feet.

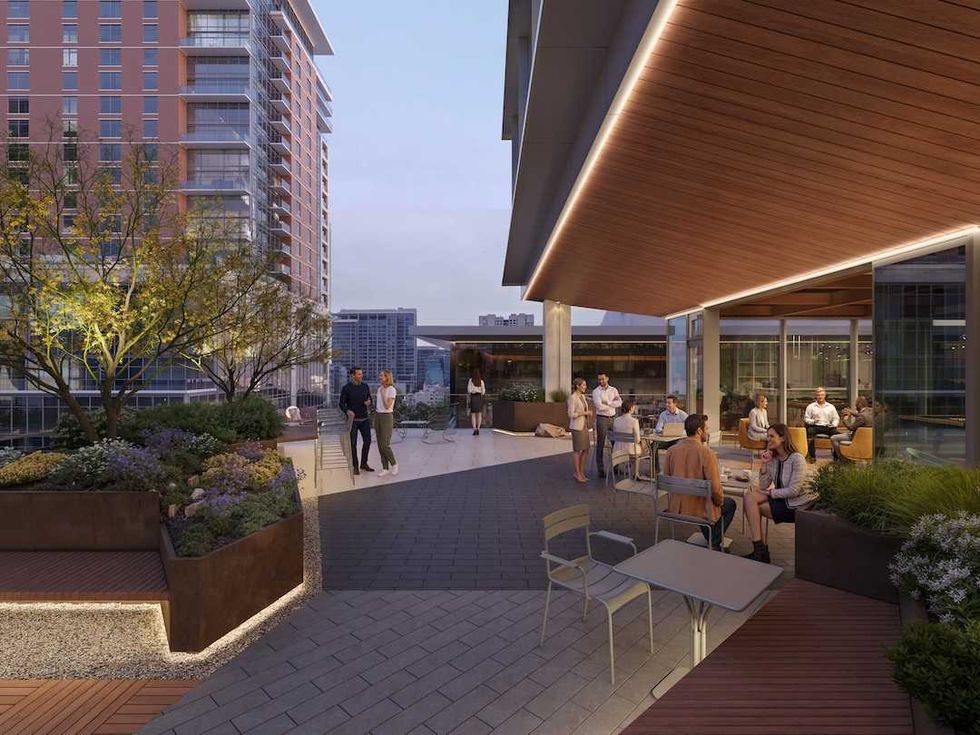
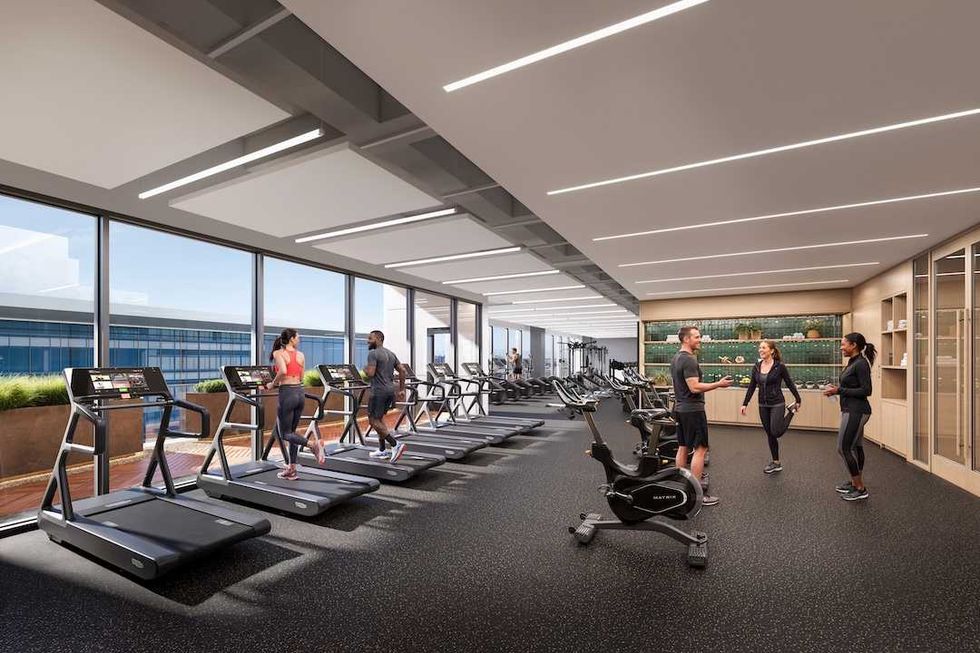
The Arc will feature conference and meeting spaces, an amenity lounge, fitness center, outdoor plazas, underground parking, and on-site retail and dining, according to the release.

It aims to host tenants focused on artificial intelligence and machine learning, data science, robotics, quantum science and engineering and energy, including Rice's new AI Foundry.

Rice says the AI Foundry will be a space where university experts and partners can support organizations with AI challenges. Rice recently committed to hiring 75 new AI-focused faculty and announced plans to launch a new Master of Artificial Intelligence (MAI) next fall.

“The AI Foundry is exactly the kind of collaboration the Arc is designed to enable,” Amy Dittmar, the Howard R. Hughes Provost and executive vice president for academic affairs at Rice, added in the release. “By bringing Rice researchers together with industry partners in a shared environment, we can accelerate the movement of ideas from research into practical applications while helping organizations build the capabilities they need to succeed as AI continues to evolve.

Developers of The Arc are targeting LEED Gold certification by incorporating smart building automation and energy-saving features into the project's design. Rice first announced the project in September 2025.

Rendering courtesy Bogza

Houston battery tech startup FlowCellutions acquired by Katy energy co.

M&A

Katy-based TerraFlow Energy, an energy storage and infrastructure company, has acquired Houston-based battery technology startup FlowCellutions. Financial terms weren’t disclosed.

FlowCellutions still operates under its established name, but with the tagline “A TerraFlow Energy Company.” Becca Segel, founder and CEO of FlowCellutions, now runs the business as its president.

FlowCellutions specializes in electrochemical sensing, diagnostics, analytics, and testing that offer insights into battery chemistry, charging capabilities, and system performance.

“FlowCellutions has always been focused on developing better ways to understand what is happening inside a flow battery and using that information to improve how these systems perform,” Segal said in a press release. “Joining TerraFlow gives us the opportunity to apply that work at a much larger scale while continuing to build the capabilities and expertise that make FlowCellutions unique.”

The FlowCellutions platform supports data centers and other heavy users of power. It’s designed to help reduce operating costs, prevent failures and costly downtime, and extend battery lifetime from about seven years to more than 30 years.

Segel founded the company in 2022. A member of Greentown Labs, the company raised more than $2 million in non-dilutive funding and received $1.5 million in National Science Foundation funding earlier this year.

FlowCellutions is one of five finalists in the Energy Transition Business category of InnovationMap’s 2026 Houston Innovation Awards.

“FlowCellutions brings a depth of scientific and technical expertise that fits naturally with where TerraFlow is going,” Jon Parrella, CEO of TerraFlow, said in the release.

“As we move from developing these systems to deploying them at commercial scale, understanding performance at a deeper level matters,” he said. “Bringing FlowCellutions into TerraFlow strengthens that capability and gives both teams more opportunity to advance the technology.”TerraFlow, founded in 2024, develops long-duration energy storage and power infrastructure for data centers, industrial facilities, utilities and other large power consumers.

---

This article originally appeared on EnergyCapitalHTX.com.

3 fast-growing Houston scaleups named Innovation Awards finalists

meet the finalists

From IPOs to groundbreakings, some of Houston's most innovative companies reached major milestones this year.

As part of the 2026 Houston Innovation Awards, our Scaleup of the Year category honors innovative later-stage startups that have recently reached a significant milestone in company growth. Three scaleups have been named finalists for the 2026 award.

Read more about these businesses, their founders and their breakthrough technologies below. The 2026 winners will be announced on InnovationMap.com in mid-November.

Erock

Energy infrastructure company Erock, previously known as Enchanted Rock, develops dual-purpose microgrids that rely on natural gas and renewable natural gas to produce lower carbon emissions and air pollutants than diesel generators. Its products can provide bridge power before grid interconnection, backup power during outages and dispatchable capacity that supports long-term grid reliability. The company has more than 1,100 megawatts of installed capacity and over 20 years of experience serving commercial, municipal and large-scale technology customers.

Erock completed its initial public offering this year, raising approximately $600 million in gross proceeds. It also grew its contracted power system sales backlog to approximately $1.7 billion, up tenfold year-over-year, with production sold out through 2028, according to the company's application. The company secured a major equipment order from Anthropic, began construction of the 366-megawatt El Paso Electric project supporting Meta's data center campus, and started assembly operations at its Hyperion facility in Cypress, Texas.

Hertha Metals

Hertha Metals produces lower-cost, lower-emission steel and high-purity iron. The company has developed a single-step process that uses natural gas as a direct reductant instead of metallurgical coal, which cuts production costs by more than 25 percent and emissions by up to 50 percent, according to the company. The same process produces high-purity iron needed for high-purity steels and rare earth magnets. The company says it aims to "re-industrialize America’s production of critical materials."

Hertha Metals was founded by CEO Laureen Meroueh in 2022 and emerged from stealth last year with more than $17 million in venture capital funding. The company closed a $133.65 million Series A this month and also broke ground on its $100M high-purity iron factory known as Chalyx in Conroe.

Venus Aerospace

Spacetech company Venus Aerospace is developing a high-thrust rotating detonation rocket engine (RDRE) that replaces the subsonic combustion used in conventional rocket engines. The RDRE is a compact, simpler engine that can deliver up to 15 percent greater efficiency for defense and space applications. It completed its first U.S. flight test of the engine last summer.

Venus Aerospace was founded in 2020 by CEO Cassie Duggleby and CTO Andrew Duggleby. It raised a $20 million Series A in 2022 and $42 million Series A2 in 2025. It closed a $91 million Series B earlier this year and expanded its leadership team. The company is working toward longer-duration and higher-thrust testing and advancing its flight program.