Everyday data like grocery store receipts can help expand access to credit and support upward mobility. Photo by Boxed Water Is Better on Unsplash

More than a billion people worldwide can’t access credit cards or loans because they lack a traditional credit score. Without a formal borrowing history, banks often view them as unreliable and risky. To reach these borrowers, lenders have begun experimenting with alternative signals of financial reliability, such as consistent utility or mobile phone payments.

New research from Rice Business builds on that approach. Previous work by assistant professor of marketing Jung Youn Lee showed that everyday data like grocery store receipts can help expand access to credit and support upward mobility. Her latest study extends this insight, using broader consumer spending patterns to explore how alternative credit scores could be created for people with no credit history.

Forthcoming in the Journal of Marketing Research, the study finds that when lenders use data from daily purchases — at grocery, pharmacy, and home improvement stores — credit card approval rates rise. The findings give lenders a powerful new tool to connect the unbanked to credit, laying the foundation for long-term financial security and stronger local economies.

Turning Shopping Habits into Credit Data

To test the impact of retail transaction data on credit card approval rates, the researchers partnered with a Peruvian company that owns both retail businesses and a credit card issuer. In Peru, only 22% of people report borrowing money from a formal financial institution or using a mobile money account.

The team combined three sets of data: credit card applications from the company, loyalty card transactions, and individuals’ credit histories from Peru’s financial regulatory authority. The company’s point-of-sale data included the types of items purchased, how customers paid, and whether they bought sale items.

“The key takeaway is that we can create a new kind of credit score for people who lack traditional credit histories, using their retail shopping behavior to expand access to credit,” Lee says.

The final sample included 46,039 credit card applicants who had received a single credit decision, had no delinquent loans, and made at least one purchase between January 2021 and May 2022. Of these, 62% had a credit history and 38% did not.

Using this data, the researchers built an algorithm that generated credit scores based on retail purchases and predicted repayment behavior in the six months following the application. They then simulated credit card approval decisions.

Retail Scores Boost Approvals, Reduce Defaults

The researchers found that using retail purchase data to build credit scores for people without traditional credit histories significantly increased their chances of approval. Certain shopping behaviors — such as seeking out sale items — were linked to greater reliability as borrowers.

For lenders using a fixed credit score threshold, approval rates rose from 15.5% to 47.8%. Lenders basing decisions on a target loan default rate also saw approvals rise, from 15.6% to 31.3%.

“The key takeaway is that we can create a new kind of credit score for people who lack traditional credit histories, using their retail shopping behavior to expand access to credit,” Lee says. “This approach benefits unbanked applicants regardless of a lender’s specific goals — though the size of the benefit may vary.”

Applicants without credit histories who were approved using the retail-based credit score were also more likely to repay their loans, indicating genuine creditworthiness. Among first-time borrowers, the default rate dropped from 4.74% to 3.31% when lenders incorporated retail data into their decisions and kept approval rates constant.

For applicants with existing credit histories, the opposite was true: approval rates fell slightly, from 87.5% to 84.5%, as the new model more effectively screened out high-risk applicants.

Expanding Access, Managing Risk

The study offers clear takeaways for banks and credit card companies. Lenders who want to approve more applications without taking on too much risk can use parts of the researchers’ model to design their own credit scoring tools based on customers’ shopping habits.

Still, Lee says, the process must be transparent. Consumers should know how their spending data might be used and decide for themselves whether the potential benefits outweigh privacy concerns. That means lenders must clearly communicate how data is collected, stored, and protected—and ensure customers can opt in with informed consent.

Banks should also keep a close eye on first-time borrowers to make sure they’re using credit responsibly. “Proactive customer management is crucial,” Lee says. That might mean starting people off with lower credit limits and raising them gradually as they demonstrate good repayment behavior.

This approach can also discourage people from trying to “game the system” by changing their spending patterns temporarily to boost their retail-based credit score. Lenders can design their models to detect that kind of behavior, too.

The Future of Credit

One risk of using retail data is that lenders might unintentionally reject applicants who would have qualified under traditional criteria — say, because of one unusual purchase. Lee says banks can fine-tune their models to minimize those errors.

She also notes that the same approach could eventually be used for other types of loans, such as mortgages or auto loans. Combined with her earlier research showing that grocery purchase data can predict defaults, the findings strengthen the case that shopping behavior can reliably signal creditworthiness.

“If you tend to buy sale items, you’re more likely to be a good borrower. Or if you often buy healthy food, you’re probably more creditworthy,” Lee explains. “This idea can be applied broadly, but models should still be customized for different situations.”

---

This article originally appeared on Rice Business Wisdom. Written by Deborah Lynn Blumberg

Anderson, Lee, and Yang (2025). “Who Benefits from Alternative Data for Credit Scoring? Evidence from Peru,” Journal of Marketing Research.
Grocery purchase data can accurately predict credit risk for individuals without traditional credit scores, potentially broadening the pool of qualified loan applicants. Photo via Unsplash

Houston researchers find alternate data for loan qualification

houston voices

Millions of consumers who apply for a loan to buy a house or car or start a business can’t qualify — even if they’re likely to pay it back. That’s because many lack a key piece of financial information: a credit score.

The problem isn’t just isolated to emerging economies. Exclusion from the financial system is a major issue in the United States, too, where some 45 million adults may be denied access to loans because they don’t have a credit history and are “credit invisible.”

To improve access to loans and peoples’ economic mobility, lenders have started looking into alternative data sources to assess a loan applicant’s risk of defaulting. These include bank account transactions and on-time rental, utility and mobile phone payments.

A new article by Rice Business assistant professor of marketing Jung Youn Lee and colleagues from Notre Dame and Northwestern identifies an even more widespread data source that could broaden the pool of qualified applicants: grocery store receipts.

As metrics for predicting credit risk, the researchers found that the types of food, drinks and other products consumers buy, and how they buy them, are just as good as a traditional credit score.

“There could be privacy concerns when you think about it in practice,” Lee says, “so the consumer should really have the option and be empowered to do it.” One approach could be to let consumers opt in to a lender looking at their grocery data as a second chance at approval rather than automatically enrolling them and offering an opt-out.

To arrive at their findings, the researchers analyzed grocery transaction data from a multinational conglomerate headquartered in a Middle Eastern country that owns a credit card issuer and a large-scale supermarket chain. Many people in the country are unbanked. They merged the supermarket’s loyalty card data and issuer’s credit card spending and payment history numbers, resulting in data on 30,089 consumers from January 2017 to June 2019. About half had a credit score, 81% always paid their credit card bills on time, 12% missed payments periodically, and 7% defaulted.

The researchers first created a model to establish a connection between grocery purchasing behavior and credit risk. They found that people who bought healthy foods like fresh milk, yogurt and fruits and vegetables were more likely to pay their bills on time, while shoppers who purchased cigarettes, energy drinks and canned meat tended to miss payments. This held true for “observationally equivalent” individuals — those with similar income, occupation, employment status and number of dependents. In other words, when two people look demographically identical, the study still finds that they have different credit risks.

People’s grocery-buying behaviors play a factor in their likelihood to pay their bills on time, too. For example, cardholders who consistently paid their credit card bill on time were more likely to shop on the same day of the week, spend similar amounts across months and buy the same brands and product categories.

The researchers then built two credit-scoring predictive algorithms to simulate a lender’s decision of whether or not to approve a credit card applicant. One excludes grocery data inputs, and the other includes them (in addition to standard data). Incorporating grocery data into their decision-making process improved risk assessment of an applicant by a factor of 3.11% to 7.66%.

Furthermore, the lender in the simulation experienced a 1.46% profit increase when the researchers implemented a two-stage decision-making process — first, screening applicants using only standard data, then adding grocery data as an additional layer.

One caveat to these findings, Lee and her colleagues warn, is that the benefit of grocery data falls sharply as traditional credit scores or relationship-specific credit histories become available. This suggests the data could be most helpful for consumers new to credit.

Overall, however, this could be a win-win scenario for both consumers and lenders. “People excluded from the traditional credit system gain access to loans,” Lee says, “and lenders become more profitable by approving more creditworthy people.”

------

This article originally ran on Rice Business Wisdom based on research by Rice University's Jung Youn Lee, Joonhyuk Yang (Notre Dame) and Eric Anderson (Northwestern). “Using Grocery Data for Credit Decisions.” Forthcoming in Management Science. 2024: https://doi.org/10.1287/mnsc.2022.02364.


Attention small business owners: it's time for a financial wellness exam. And Hello Alice has just the tool for you to use. Photo by Hero Images

Houston fintech company launches new tool for startups and small businesses

wellness check

Much like the humans that run them, businesses need the occasional wellness exam. A fintech company founded in Houston has created a tool for conducting that health check.

Hello Alice announced that its new tool Business Health Score has launched today. The assessment tool can be used by startups and small businesses to navigate their financial and business health. The tool is the first product rolling out from the Equitable Access Program, a new initiative from Hello Alice and the Global Entrepreneurship Network with support from Wells Fargo, JPMorgan Chase, Mastercard, and the Kauffman Foundation.

Hello Alice was co-founded by Elizabeth Gore and Carolyn Rodz and has worked with over one million small businesses to help them access capital. The idea of the Score is to give business owners "a comprehensive overview of a business's financial health," according to the news release from Hello Alice. This information is critical for decision making and works hand-in-hand with all of Hello Alice's existing resources.

Operating as a self-assessment questionnaire, the Score will provide entrepreneurs with a composite number by evaluating three business aspects: financial and business management practices, financial performance and position, and credit history.

“Over the last two years, Americans have applied to start 10.5 million new businesses, leading to a surge in the small business economy and more entrepreneurs who need support to properly grow their businesses," say Gore and Rodz in the release. "We recognized data was missing from the market that would give enterprise partners and financial institutions a clearer picture of the potential that small business owners possess for massive growth and investment."

The Score will help Hello Alice and its partners, which includes financial institutions, navigate the business's unique needs and provide the appropriate financial services and resources.

“We are providing unparalleled visibility through the Business Health Score that will empower small business owners to make more strategic decisions and optimize their growth while giving partners and institutions the insight to best help them through personalized service and product recommendations," the co-founders continue. "The Score and the larger Equitable Access Program we have launched with GEN are a huge step forward in opening up more growth opportunities for small businesses and ecosystem partners.”

Hello Alice and GEN are on a mission of democratizing access to capital so that entrepreneurs from all communities have the ability to grow their businesses sustainably. Last year, Hello Alice launched an entrepreneur-focused credit card that helped businesses more easily set up a line of credit.

“Entrepreneurs are well-equipped to deal with disruption and changing dynamics, but while talent is plentiful, opportunity is not,” says Jonathan Ortmans, founder and president of the Global Entrepreneurship Network, in the release. “The Equitable Access Program and Business Health Score will open doors for small business owners to better manage and grow their businesses, which will lead to more strategic partnership and funding opportunities.”

Ad Placement 300x100
Ad Placement 300x600

CultureMap Emails are Awesome

Energy AI company opens first U.S. office at Houston’s the Ion

Building on its partnership with Houston-based oilfield services provider Halliburton, energy-sector AI company Shape Digital recently opened an office at The Ion. It’s the company’s first U.S. location.

Shape Digital’s workforce in Houston includes employees specializing in tech support, business development and client services. The company’s local hiring projections and headcount weren’t available. The new office will be located within Industrious at the Ion, according to Rice Alliance.

A key driver of the new Houston office: The company forecasts North America will account for more than 20 percent of its business in 2027.

“North America is a critical market for industrial innovation, and Houston sits at the center of companies driving that progress,” Caio Sene, vice president of client services at Shape Digital, said in a release. “Growing our presence here allows us to work alongside operators as they look for practical ways to turn existing operational data into clear recommendations for what to do next.”

Shape Digital, which also has offices in Singapore and Brazil, develops decision-making platforms for the oil and gas sector.

The Ion District office gives Shape Digital a presence close to Halliburton’s headquarters. In May, the two companies forged a partnership to combine Halliburton’s Digital Field Solverdecision-making system with Shape Digital’s AI portfolio.

Shape Digital layers AI software atop existing operations data rather than replacing legacy systems or adding new software.

The company’s suite of AI agents draws on more than 200 operations-monitoring algorithms, continually learning from company and industry data. The suite comprises four products: Shape Aura, Shape Lighthouse, Shape Lumen and Shape Reef.

Shape Digital says that by working with a customer’s existing operations data, it can deliver ROI in less than two months without any additional investment in equipment or infrastructure.

The company is a 2021 spinoff of Japan-based Modec. Modec builds, owns, and operates floating offshore oil and gas production facilities. Its Modec America subsidiary is based in Houston.

Meet the esteemed judges for the 2026 Houston Innovation Awards

Meet The Judges

Editor's note: Judging is now underway for the 2026 Houston Innovation Awards, and it's time to meet the decision makers.

Our 2026 judging panel comprises past award winners who represent a variety of industries and areas of expertise. They are joined by InnovationMap's interim editor. All are deeply engaged in the Houston innovation ecosystem.

Our judging panel will review all nominee applications submitted across 10 prestigious categories. They will determine the 2026 finalists in all categories, and they will select the winners in all but one category — our people's choice award for Startup of the Year.

The sixth annual Houston Innovation Awards program will be presented in an all-digital format in 2026. We will announce this year's finalists and feature their stories throughout our special editorial series this fall. Then, stay tuned as we reveal the 2026 Houston Innovation Awards winners on InnovationMap.com in mid-November.

Sagar Dalal, Fervo Energy, 2025 Scaleup of the Year

Sagar Dalal

Sagar Dalal serves as chief of staff at Fervo Energy, a company pioneering the commercialization of next-generation geothermal power. In this role, he helps translate the CEO’s vision and priorities into execution, leading cross-functional strategic initiatives that support the company’s growth and operations.

Dalal brings nearly eight years of experience in structural engineering and project management from his time at Thornton Tomasetti and Tesla, where he engineered and built a wide range of infrastructure projects ranging from stadiums to manufacturing facilities. He holds an MBA from Stanford University and an MS in Civil Engineering from Texas A&M University. He is also a licensed professional engineer.

Aaron Fitzgerald, Mars Materials, 2025 Minority-founded Business of the Year

Aaron Fitzgerald

Aaron Fitzgerald is a three-time founder and carbon removal entrepreneur focused on reimagining how we make things. As the CEO of Mars Materials, he leads a team working to commercialize technologies that sequester captured carbon into industrial supply chains.

His vision for a defossilized future is shaped by a unique path through both policy, including a tenure in the United States Senate, and deep carbontech, with fellowships at The Lewis Latimer program, Breakthrough Energy, Prime Coalition, and Carbon 180.

Tatiana Fofanova, Koda Health, 2025 Health Tech Business of the Year

Tatiana Fofonova

Tatiana Fofanova, PhD, is the co-founder and CEO of Koda Health, an AI-enhanced patient decision support platform designed to make advance care planning (ACP) scalable, accessible, and patient-centered for patients with serious illness.

After earning her PhD in Translational Medicine at Baylor College of Medicine, she joined Texas Medical Center (TMC) as a Founder-in-Residence. It was there that she and her co-founders identified one of the most overlooked yet critical gaps in healthcare: the lack of meaningful, accessible advance care planning. Under her leadership, Koda Health now supports over 1 million patients through partnerships with organizations like Cigna, Privia, and Houston Methodist.

Lawson Gow, Greentown Labs, 2025 Incubator/Accelerator of the Year

Lawson Gow currently serves as chief strategy officer for Greentown Labs, which was named Incubator/Accelerator of the Year in the 2025 Houston Innovation Awards. Prior to joining Greentown Labs as Head of Houston in 2025, Gow was as a managing partner at Helium Capital, an investment and advisory firm that aims to support founders across the entire lifecycle of entrepreneurship.

He is also the founder of The Cannon, an innovation-infrastructure provider that operates a growing network of innovation hubs for its community of startups, entrepreneurs, investors, and corporate innovators.

Sarah Hein, March Biosciences, 2025 Female-founded Business of the Year

Sarah Hein

Sarah Hein is the founding CEO of March Biosciences, a clinical-stage cell-therapy company targeting challenging malignancies. Prior to cofounding March Biosciences, she was the founding Entrepreneur in Residence for the Texas Medical Center Innovation Accelerator for Cancer Therapeutics (TMCi ACT).

Formerly, she was a cofounder and the vice president of operations at Courier Therapeutics, a cancer immunotherapy startup acquired by Valo Health. She was also director of research at Resonant Therapeutics, an antibody therapeutics platform technology company. She began at Mercury Fund as a Venture Fellow directly after graduating with her PhD in Molecular Biology from Baylor College of Medicine.

Tanu Jain, FlowCare, 2025 Startup of the Year

Tanu Jain

Tanu Jain is a product executive, entrepreneur, founder and CEO of FlowCare, and registered nurse with a track record of building products from zero to global scale. She previously led product at BioIQ before founding FlowCare, a Houston-based period care infrastructure platform making period care a standard in every restroom. In under 16 months, FlowCare has signed deployed across four enterprise customers and impacted more than 1.5 million women.

FlowCare was named Startup of the Year at the 2025 Houston Innovation Awards, and Jain has been recognized with additional honors including the SDG Super Changemaker – Pewter — at the Global Sustainability Awards 2026.

Prabhdeep "Prab" Sekhon, Eclipse Energy, 2025 Energy Transition Business of the Year

Prabhdeep Singh Sekhon

Prabhdeep Singh Sekhon is CEO of Eclipse Energy, an energy technology company transforming depleted oil fields into low-cost, sustainable hydrogen resources through subsurface biotechnology. He brings nearly two decades of global energy experience spanning climate technology, venture capital, private equity, and multi-billion-dollar energy projects across five continents.

Previously, he held leadership roles at NextEra Energy Resources and Hess Corporation. He is also a founder and managing director of GreenLite Resources and a founding member of Cotogna Sports Group. He holds an MBA from Wharton, a Masters in Engineering from Texas A&M, and a BS from the University of Calgary.

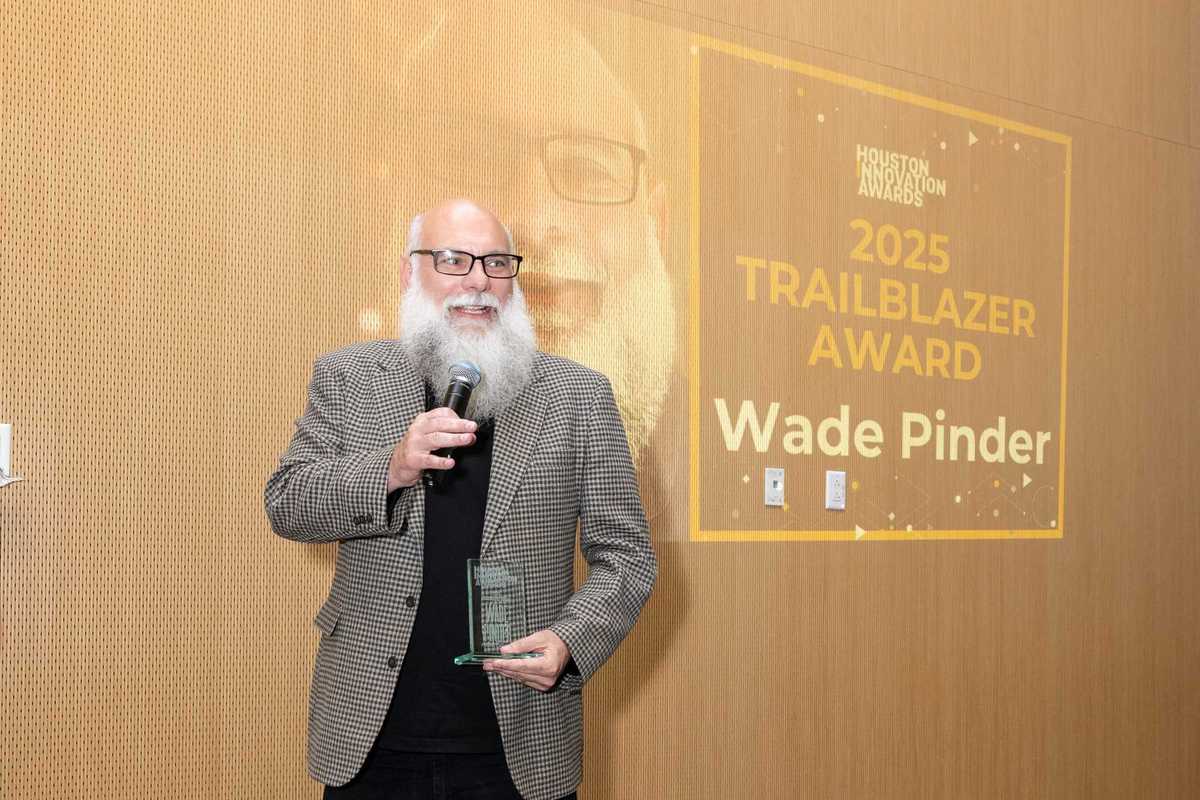
Wade Pinder, Product Houston, 2025 Trailblazer Award Winner

Wade Pinder thinks of himself as an "ecosystem wayseeker," helping founders and builders in and around Houston find their footing, understand the landscape, and move through uncertainty with more clarity. Through Product Houston, he works at the intersection of product strategy, founder support, ecosystem mapping, and community-building, with a particular focus on helping people show up in the right rooms before they feel fully ready.

His background includes years in product management at Blinds.com and Home Depot, along with founding and leading the Houston Product Community for six years. He was recognized by as Mentor of the Year in the 2023 Houston Innovation Awards and received the Trailblazer Award in 2025.

Laura Furr Mericas, Interim Editor, InnovationMap

Laura Furr Mericas is interim editor for InnovatonMap.com and EnergyCapitalHTX.com. She is a longtime contributor to both sites and has reported on Houston's innovation ecosystem for InnovationMap since 2020. Previously, she served as web editor and data reporter for Houston Business Journal.

Report: Income for top 1 percent earners in Texas has surged in 2026

money matters

In a state where local billionaires are wealthier than they've ever been, high-earning Texans need to make $73,000 more than they did a year ago if they want to be among the top 1 percent of earners, a new report has revealed.

SmartAsset's study analyzed income thresholds for the top 1, 5, and 10 percent of earners in all 50 states and the District of Columbia, using 2022 IRS data for individual tax return filers (the most recent year available), adjusted to 2026 dollars.

Texas has the 11th highest income threshold, with residents needing to make a minimum of $817,158 to be considered among the top 1 percent of earners statewide. In 2025, Texans needed to make about $744,000 to be among the top 1 percent.

For comparison, residents living in the nation's capital must make at least $1.16 million to qualify as top 1 percent earners. The District of Columbia led the nation with the highest income threshold to be a top earner.

To be considered among the top 5 percent of earners in Texas, a resident would need to make $312,671. The income threshold to be considered among the top 10 percent is $210,609.

SmartAsset additionally found that 128,130 Texas residents qualified as top 1 percent earners in 2022. Nationally, the report estimated that fewer than 2 million households earn enough to be considered among the top 1 percent of earners nationwide, but 23 million households rank among the top 10 percent.

"In some places, households can enter the top 1 percent at income levels that fall well below the threshold elsewhere, reflecting an uneven landscape of wages and wealth," the report said.

A separate SmartAsset study that tracked the upper and lower thresholds for middle class households found Houston residents need to make anywhere from $42,907 to $128,722 to maintain their middle class status.

The top 10 states with the highest thresholds to be considered in the top 1 percent of earners in the U.S. are:

  • No. 1 – District of Columbia ($1,156,664)
  • No. 2 – Connecticut ($1,147,898)
  • No. 3 – Massachusetts ($1,006,921)
  • No. 4 – California ($987,325)
  • No. 5– New Jersey ($969,976)
  • No. 6 – New York ($959,562)
  • No. 7 – Florida ($956,449)
  • No. 8 – Washington ($903,303)
  • No. 9 – Colorado ($828,772)
  • No. 10 – Wyoming ($819,014)
---

This article originally appeared on CultureMap.com.