Everyday data like grocery store receipts can help expand access to credit and support upward mobility. Photo by Boxed Water Is Better on Unsplash

More than a billion people worldwide can’t access credit cards or loans because they lack a traditional credit score. Without a formal borrowing history, banks often view them as unreliable and risky. To reach these borrowers, lenders have begun experimenting with alternative signals of financial reliability, such as consistent utility or mobile phone payments.

New research from Rice Business builds on that approach. Previous work by assistant professor of marketing Jung Youn Lee showed that everyday data like grocery store receipts can help expand access to credit and support upward mobility. Her latest study extends this insight, using broader consumer spending patterns to explore how alternative credit scores could be created for people with no credit history.

Forthcoming in the Journal of Marketing Research, the study finds that when lenders use data from daily purchases — at grocery, pharmacy, and home improvement stores — credit card approval rates rise. The findings give lenders a powerful new tool to connect the unbanked to credit, laying the foundation for long-term financial security and stronger local economies.

Turning Shopping Habits into Credit Data

To test the impact of retail transaction data on credit card approval rates, the researchers partnered with a Peruvian company that owns both retail businesses and a credit card issuer. In Peru, only 22% of people report borrowing money from a formal financial institution or using a mobile money account.

The team combined three sets of data: credit card applications from the company, loyalty card transactions, and individuals’ credit histories from Peru’s financial regulatory authority. The company’s point-of-sale data included the types of items purchased, how customers paid, and whether they bought sale items.

“The key takeaway is that we can create a new kind of credit score for people who lack traditional credit histories, using their retail shopping behavior to expand access to credit,” Lee says.

The final sample included 46,039 credit card applicants who had received a single credit decision, had no delinquent loans, and made at least one purchase between January 2021 and May 2022. Of these, 62% had a credit history and 38% did not.

Using this data, the researchers built an algorithm that generated credit scores based on retail purchases and predicted repayment behavior in the six months following the application. They then simulated credit card approval decisions.

Retail Scores Boost Approvals, Reduce Defaults

The researchers found that using retail purchase data to build credit scores for people without traditional credit histories significantly increased their chances of approval. Certain shopping behaviors — such as seeking out sale items — were linked to greater reliability as borrowers.

For lenders using a fixed credit score threshold, approval rates rose from 15.5% to 47.8%. Lenders basing decisions on a target loan default rate also saw approvals rise, from 15.6% to 31.3%.

“The key takeaway is that we can create a new kind of credit score for people who lack traditional credit histories, using their retail shopping behavior to expand access to credit,” Lee says. “This approach benefits unbanked applicants regardless of a lender’s specific goals — though the size of the benefit may vary.”

Applicants without credit histories who were approved using the retail-based credit score were also more likely to repay their loans, indicating genuine creditworthiness. Among first-time borrowers, the default rate dropped from 4.74% to 3.31% when lenders incorporated retail data into their decisions and kept approval rates constant.

For applicants with existing credit histories, the opposite was true: approval rates fell slightly, from 87.5% to 84.5%, as the new model more effectively screened out high-risk applicants.

Expanding Access, Managing Risk

The study offers clear takeaways for banks and credit card companies. Lenders who want to approve more applications without taking on too much risk can use parts of the researchers’ model to design their own credit scoring tools based on customers’ shopping habits.

Still, Lee says, the process must be transparent. Consumers should know how their spending data might be used and decide for themselves whether the potential benefits outweigh privacy concerns. That means lenders must clearly communicate how data is collected, stored, and protected—and ensure customers can opt in with informed consent.

Banks should also keep a close eye on first-time borrowers to make sure they’re using credit responsibly. “Proactive customer management is crucial,” Lee says. That might mean starting people off with lower credit limits and raising them gradually as they demonstrate good repayment behavior.

This approach can also discourage people from trying to “game the system” by changing their spending patterns temporarily to boost their retail-based credit score. Lenders can design their models to detect that kind of behavior, too.

The Future of Credit

One risk of using retail data is that lenders might unintentionally reject applicants who would have qualified under traditional criteria — say, because of one unusual purchase. Lee says banks can fine-tune their models to minimize those errors.

She also notes that the same approach could eventually be used for other types of loans, such as mortgages or auto loans. Combined with her earlier research showing that grocery purchase data can predict defaults, the findings strengthen the case that shopping behavior can reliably signal creditworthiness.

“If you tend to buy sale items, you’re more likely to be a good borrower. Or if you often buy healthy food, you’re probably more creditworthy,” Lee explains. “This idea can be applied broadly, but models should still be customized for different situations.”

---

This article originally appeared on Rice Business Wisdom. Written by Deborah Lynn Blumberg

Anderson, Lee, and Yang (2025). “Who Benefits from Alternative Data for Credit Scoring? Evidence from Peru,” Journal of Marketing Research.
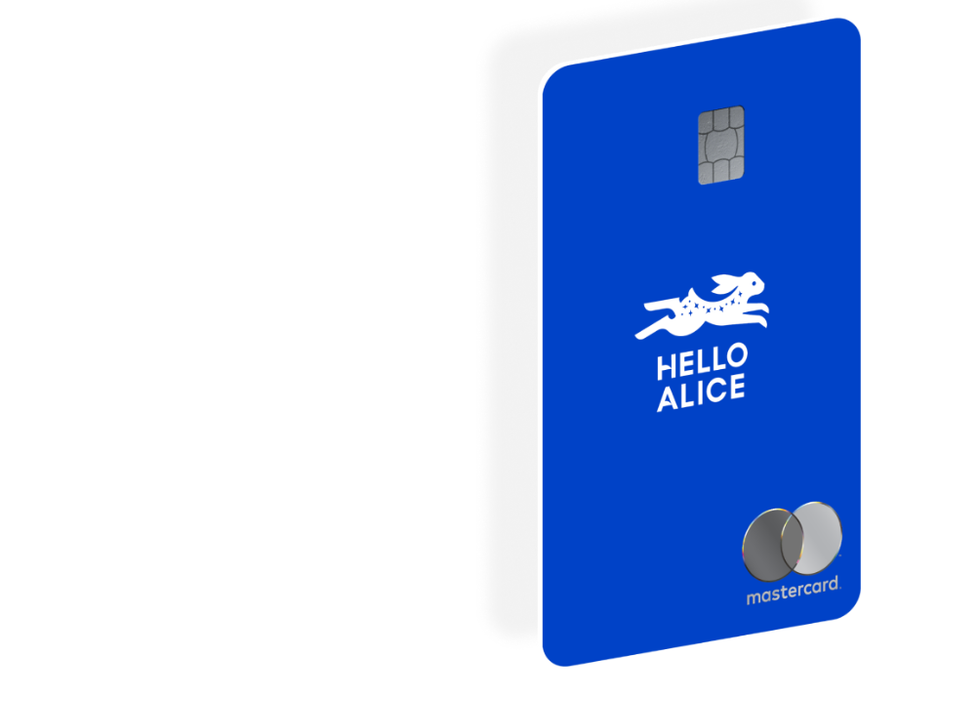
In an interview with InnovationMap, Carolyn Rodz, CEO and founder of Hello Alice, explains how the partnership came about and how the program will significantly move the needle on equitable access to capital for small business owners. Photo courtesy of Hello Alice

How this Houston innovator is providing small businesses unprecedented access to capital

Q&A

Last month, Hello Alice — now with 1 million members in its community — announced a new program with MasterCard that provides small business owners a simpler way to unlock access to capital.

The Hello Alice Small Business Mastercard offers users expert business advice, business insights, cash back, and a rewards program that gives entrepreneurs points for completing business-advancing activities on the Hello Alice platform.

"As a small business owner myself, I've created a card that I wish I would have had," Carolyn Rodz, CEO and founder of Hello Alice, tells InnovationMap. "We really looked at where are the gaps for these business owners and the things they don't already have or are unable to access."

In an interview with InnovationMap, Rodz explains how the partnership came about and how the program will significantly move the needle on equitable access to capital for small business owners.

InnovationMap: How did this partnership come about to provide this this unique credit card for small business owners?

Carolyn Rodz: We have been looking at ways to support business owners along their capital journeys for a long time. Since we started Hello Alice access to capital has been the number one barrier for small business owners, and that's only magnified when we look at business owners of color and our new majority business owners that we focus on. And so it made natural sense as we went down a path of conversations with MasterCard initially around how do we create something, particularly in a world where accessing capital, which would be daunting for business owners.

There's a lot of talk around venture capital and getting loans and what that growth journey looks like. But the reality is most business owners understand a credit card — they understand how it works. So, that was a great starting point for us. Then we looked at what are some of the issues with cards — all business cards particularly or commodities. They're typically an afterthought from a lot of the financial institutions that offer them. We're seeing a lot of these emerging fintech companies that are rolling out cards, but even for them, the small business audience is typically an afterthought. They're really focused on tech companies and very rapid growth businesses.

It felt like mainstream small businesses were really getting lost in this conversation, so that was where we really wanted to tackle. How do we solve some of these problems — how do we create benefits that are actually meaningful to small business owners? Things like one-on-one coaching and helping them get access to workshops that will help them along their growth journey. Things that they can redeem points for experiences and opportunities that that may not otherwise be accessible through a lot of these business owners.

The other piece that we wanted to support is the large group of businesses that don't qualify for a traditional credit card. And so we, in tandem with our unsecured credit card, also launched a secured card. And the idea for that was that we could actually roll out a credit quality tool. So, in conjunction with all the education and wraparound services that we're offering, there's a six- to nine-month process that a business owner — if they have poor credit history — can go through to build up that credit with a secured credit card and then seamlessly transition into an unsecured card. It's an opportunity to take that first step toward building and growing their business and accessing the capital that they need to grow.

IM: How does this initiative target the inequality in access to capital for small business owners?

CR: Well, nine out of 10 of business owners are relying on their personal credit card when they're applying for financing. When we look at entrepreneurs of color, the rate of low credit score for them is two to three times higher for Black and LatinX entrepreneurs specifically. So for us, this is the importance of building in conjunction with our creating equitable access to credit program that is much broader, frankly, than the card itself, but offering the wraparound services around it, making sure that we are providing the secured to unsecured seamless transition plan.

We're also working with the First National Bank of Omaha, and the reason we selected them at the bank, they're the largest privately held bank in the country. This also gave us the flexibility to really look at alternative underwriting models and the the opportunity to learn through all of the insights that we're gaining around these small business owners. We're trying to figure out how do we start to look at some of these alternative data points and identify not just the financial history of a business owner.

There are a lot of circumstances that lead to poor credit scores, whether it was for a health circumstance that they endured or veteran business owners who may have no credit history because they've been overseas for a long period of time. We're looking at what are some of the data points that are indicating that a business owner is more likely to succeed and more likely to repay the credit that they've taken on. We know already through a lot of research and data points that having a business plan automatically makes you more likely to repay your your debt. Or the fact that you are getting positive feedback from mentors is a strong indicator that you're going to be more likely to pay off some of those debts. And so we're really looking at what are some of these things that may be overlooked but are frankly more indicative of who the business owner is and the potential for their for their business and their opportunities to be able to repay credit that they take off.

IM: What type of small business owners do you feel like this is a really good solution for? What all can they expect from the program?

CR: As a small business owner myself, I've created a card that I wish I would have had. When I started this company, I really looked at what was available to the market. This credit card, like many cards, offers benefits that are pretty standard in the market right now. Things like cash back, extra points, and kickers for certain spends that are relevant to small business owners. But again, we really looked at where are the gaps for these business owners and the things they don't already have or are unable to access.

What we discovered was there are lots of accelerators, programs, and workshops and things — but they're expensive. So, there's an opportunity here. We work with our network of partners that we have for Hello Alice that are traditionally paid or have a cost to roll them out and offer business owners points and earnings that can be spent toward that.

Mentorship, as you know, is a huge, huge barrier, particularly when we look at our new majority entrepreneurs, so all of our cardholders get access to one-on-one coaching for this card. And we've really focused on areas that are primary interest to them, things like business strategy, operations, and financing for their businesses.

And then the other important piece of this is leveraging our partner network. We have so many partners that we work with at Hello Alice, companies that are offering products and tools and services to small business owners. With this card, we're opening up additional discounts beyond what we've already negotiated standards for all of our community, whether it's an extra discount on things like QuickBooks, Salesforce, or different tools that they might be using. We have over 70 affiliate partners that we've already brought into the program working with more every week right now, which is really exciting.

We're also trying to find new opportunities — where can we bring the most benefit these business owners in a way that grows with their company and that, as they're spending and creating traction with their company, our team is working behind the scenes to unlock more and more opportunities every stage of that journey.

IM: Do you feel like this program is a response to the growing challenges small businesses have been facing over the past few years?

CR: I mean, our business certainly had a hell of a couple of years, and 89 percent of small business owners in our community, which is now over a million business owners strong, claim the access to capital is limiting their growth potential. Where we focus a majority of our energy as a company is unlocking those barriers.

As we dig into that, what we're seeing is access to capital — whether that's early days as a credit card or a grant funding, or later stage with loans or even venture capital — is that we need to address this by helping to unlock that journey for business owners, but also making sure that we're supporting them with the opportunities that are relevant to their own stage of growth.

The other piece is revenue generation. We always want to focus on the core and sustainable business health of a company and making sure that they're bringing in revenue and that they've created a business model that actually works and is scalable. We're working a lot on providing them not just money into their business or outside capital, but how do we actually help them generate revenue and clear capital in all the stages unless they have that capital? How do we actually help them deploy that capital in meaningful ways will help them grow their business?

All of the wraparound services that come with the core of what Hello Alice offers — and certainly with this credit card we're getting a deeper layer of insight, because we know more about the businesses, we know how they're spending, what they're doing. We're really learning about how do we additionally support this cohort of business owners with the right wraparound services, making sure that they're getting the right thing at the right time.

What's interesting is that and the reason we really started with the credit card is that 50 percent of small business owners have a personal credit score of 680 or better, and that's strong enough to apply for most business credit cards. However, that score locks them out of getting a business loan, which typically requires a score of 720 or better to qualify. So we're able to tap into a cohort and help them grow this pool of capital in the earliest stages. But really making sure that we're giving them the growth tools that ultimately free them up to go get that loan, to go walk into a main street bank and have that power of choice along their capital journey.

In general, we focus a lot on access to capital. We deployed over $37 million in small business grants to date, and we're continuing to grow that pool. We're actually working right now on an equitable access to capital fund, which will allow us to utilize those grants to actually pay the security deposit for select business owners who may not qualify for additional credit.

Ultimately, this is a really tangible way to work with financial institutions, MasterCard, and our broader partner ecosystem. We haven't seen the statistics move in decades. How do we actually open up more capital to business owners that otherwise wouldn't qualify for it? And this is our our first of many steps toward towards putting a really tangible stake in the ground.

IM: What about the challenges of the pandemic — how do you see COVID-19 and its shutdown affect small businesses?

CR: For us, like many businesses, I think the pandemic was it shook everything up. I think we had a plan and a path forward that always entailed unlocking access to capital and unlocking opportunity — that has never changed for us. But it accelerated a lot of things. We had planned to deploy grant funding in 2020 independent of the pandemic. When COVID hit and we saw these businesses struggling, we quickly pivoted. We accelerated that plan significantly. We started deploying grants within weeks of shelter in place — even before PPP had been announced and before businesses were accessing any government support. We were among the first to offer emergency grants and put us in a really strong position to grow that program and again to accelerate the rollout of that, which is now turned into a much larger program.

That really was, I would say, the acceleration of our entire early stage access to capital continuum. And what we learned from that was how much capital these business owners actually need. The process gave us a lot of information that that has really helped roll out the broader continuum of capital for us. We launched our lending marketplace with over 92 small business lenders all focused on fair and equitable funding, which is available over all as well. And so these credit cards round out that early stage access to capital.

But when we look at our new majority cohort — and even many white male businesses — we have to get business owners of all types that are struggling with access to capital. Everybody's willing to give money to business owners that have traction, that are doing well with their business, that are on a growth path. But it's very hard to get the traction that big investors need, and that's always really struggle.

The pandemic accelerated a lot in this space. It made us realize that the opportunity here is actually much greater to support these businesses and also got a lot of attention from partners. We've been having these conversations for years, frankly, prior to the pandemic. And everybody recognized there was an issue, but I don't think they realized the impact of the issue until COVID hit, and small businesses were the ones that kept operating and made sure that we were getting the resources that we needed to continue to live in a time when everything was a little bit uncertain.

------

This conversation has been edited for brevity and clarity.

Small business owners now have a new option for their credit and financial support needs, thanks to Hello Alice and Mastercard. Image via Getty Images

Houston small biz tech platform launches entrepreneur-focused credit card

hello credit

When you're a small business owner, every service you sign up for or institution you open an account at should be a helpful partner on your business journey. At least, that's how Hello Alice sees it.

The Houston company has partnered up with Mastercard and First National Bank of Omaha to provide small business owners a suite of financial services with their line of credit. The Hello Alice Small Business Mastercard will offer users expert business advice, business insights, cashback, and a rewards program that gives entrepreneurs points for completing business-advancing activities on the Hello Alice platform.

“We designed the Hello Alice Small Business Mastercard to meet the needs of small business owners where they are, breaking longstanding barriers to mentorship, access to credit, and overall financial health for those who have traditionally been denied access,” says Elizabeth Gore and Carolyn Rodz, co-founders of Hello Alice, in a statement.

“In times of economic boom and bust, access to capital remains the leading challenge for all small business owners, and particularly for New Majority owners, which is why we continue to focus our efforts on expanding the capital continuum beyond our existing grants and loans programs,” the duo continued.

Offered as a traditional credit card, the Hello Alice Small Business Mastercard provides users with credit-building opportunities. Business owners with a limited or poor credit history also have the opportunity to a secured version of the credit card that still provides full benefits from the program.

“Small businesses are the backbone of our communities, yet too often face significant obstacles in securing the resources they deserve, particularly if the owners come from underserved communities,” says Linda Kirkpatrick, president for North America at Mastercard, in the release. “The launch of the Hello Alice Small Business Mastercard is an important step in our mission to build a more inclusive digital economy by providing small businesses with the financial tools and capital they need to thrive, while also advancing our half-billion-dollar commitment to help close the racial wealth and opportunity gap for Black communities.”

This initiative is the latest announcement from Hello Alice’s Equitable Access to Capital program, which is focused on increasing access to the capital — as well as financial products, tools, and education — small businesses need to grow sustainably and power the national economy. By 2025, according to Hello Alice, approximately $70 million in grants could fund credit enhancements for approximately 30,000 business owners, unlocking up to $1 billion in credit access.

“FNBO has been committed to helping small businesses succeed for 165 years, and we are proud to partner with Hello Alice and Mastercard in this vital initiative to elevate all small businesses,” says Jerry J. O’Flanagan, executive vice president of Partner Customer Segment at First National Bank of Omaha.


The new credit card will provide credit and financial advice, support, and education to small business owners. Image via helloalice.com
Houstonians are carrying sizable debt into the new year. Photo via LivingDice.com

This is how much credit card debt the average Houstonian carries, says report

MONETARY MISFORTUNE

Residents of Houston are nursing New Year's hangovers of another kind — credit card debt.

According to a LendingTree study of the 50 largest U.S. metro areas, Houston consumers rank fourth for the highest median amount of credit card debt to ring in the new year: $3,720. In second place is Austin ($3,911), with Dallas at No. 7 ($3,560). San Antonio holds down the No. 14 spot ($3,414).

Hartford, Connecticut, claims the dubious distinction of ranking first in this category, with median credit card debt of $3,994.

Matt Schulz, LendingTree's chief credit analyst, says people with good credit and high income typically are more inclined to carry bigger credit card balances, since they usually have access to higher credit limits. But he notes that a significant number of younger consumers carry a high amount of credit card debt.

"When you're young and don't have a lot of financial experience, that scary combination can lead to more debt, especially for those living in big, expensive cities," according to LendingTree.

By another yardstick, Texas' four major metros fare much better in the LendingTree study.

Houston ranks 38th for the share of credit card users with debt (81.1 percent). Austin ranks No. 21 (84.7 percent), followed by Dallas at No. 37 (81.2 percent), and San Antonio at No. 48 (75.7 percent).

LendingTree researchers used an anonymized sample of more than 40,000 My LendingTree users from the first 15 days of December 2020 to estimate the percentage of credit card users carrying debt into 2021. They also relied on that data to compile median credit card debts.

------

This article originally ran on CultureMap.

Ad Placement 300x100
Ad Placement 300x600

CultureMap Emails are Awesome

Axiom Space inks partnership to grow semiconductor crystals in orbit

space deal

Down in Webster, Texas, and high above the Earth, Axiom Space and Kansas-based Nitride Global Inc. will grow the next generation of semiconductor crystals in microgravity thanks to a new memorandum of understanding (MOU) signed earlier this month.

“Signing this MOU with Nitride Global reflects the growing commercial interest in producing advanced semiconductor materials in space,” Lucie Low, chief science officer for Axiom Space, said in a news release. “Their leadership in aluminium nitride (AlN) crystal growth and advanced packaging technologies, combined with Axiom Space’s capabilities in orbital infrastructure and mission integration, position us to demonstrate real commercial value in low-Earth orbit (LEO).”

This latest partnership builds on existing collaboration between Axiom and NitrideGlobal and NASA Ames Research Center.

Aluminium nitride crystals are part of the cutting-edge generation of semiconductors essential to emerging high-voltage transistors and also used in various medical technologies. Because of their high thermal stability, they can be used in a variety of environments and applications that have revolutionized everything from electric cars to the grids the cars run on.

However, the crystals are challenging to grow on Earth and face defects and size limitations due to gravity. Growing them in space can enhance their performance, according to NitrideGlobal. Microgravity allows them to grow more uniformly and with fewer defects, potentially resulting in larger, purer and more reliable crystals.

That’s where Axiom Space comes in. The company is developing Axiom Station, a successor to the International Space Station, where new research and manufacturing can be carried out.

“This MOU marks a pivotal milestone in our close partnership with Axiom Space that started as part of the NASA Small Business Innovation Research (SBIR) for AlN growth in space and is now expanding to usher the development of an innovation ecosystem,” Mahyar Khosravi, CEO of Nitride Global Inc., added in the release. “With Axiom Space’s leadership in the in-space manufacturing sector, this partnership will aim to deliver a platform for commercially viable manufacturing of [ultrawide bandgap materials] that will enable the next generation of semiconductor & microelectronics for terrestrial and planetary exploration uses.”

Houston's IAH lands on list of 15 most expensive U.S. airports

Travel Woes

Hold on to those carry-on bags: George Bush Intercontinental Airport is checking in as one of the 15 most expensive airports in the U.S., a new study has revealed.

The analysis from digital commerce and marketing platform ConsumerVoice.org compared the average domestic flight costs at the 50 largest U.S. airports, ranking them from highest to lowest. Flight price data was sourced from the U.S. Department of Transportation’s Bureau of Transportation Statistics (BTS) during the first and second quarters of 2026 and compared with the same period in 2025.

Washington Dulles International Airport in Virginia tops the list as the priciest major airport in the U.S, with domestic flights at IAD costing $534.34 on average. Charlotte Douglas International Airport in North Carolina comes in second place with an average fare cost of $527.79.

IAH lands at No. 13 nationwide, and it's the second most expensive in Texas, the findings show. The typical domestic flight from IAH costs $482.02, and they aren't getting any cheaper. Flights out of IAH are nine percent more expensive than they were a year ago, the report found. The average domestic flight cost $37.80 less in 2025.

Houstonians not only need to be prepared to spend a little extra money when booking their tickets; they'll also need to pack their patience, as IAH also ranks among the worst airports for flight delays and cancellations.

Travelers on a budget can save more on flights out of William P. Hobby Airport, if they're willing to make the drive. Travelers can save about 13 percent on their flights by flying through HOU instead of IAH, but there are other costs to take into consideration.

"Ground transportation, gas, and parking can eat into the difference, so factor these in when choosing the most economical departure airport," the report said.

HOU ranked as the No. 31 most expensive airport on the list with domestic flights coming in at $417.78 on average. Average fares at HOU are also nine percent more expensive than they were last year.

The top 10 priciest major airports in the U.S. are:

  • No. 1 – Washington Dulles International Airport
  • No. 2 – Charlotte Douglas International Airport
  • No. 3 – Detroit metro Wayne County Airport
  • No. 4 – Salt Lake City International
  • No. 5 – Minneapolis-St. Paul International
  • No. 6 – San Francisco International
  • No. 7 – John F. Kennedy International
  • No. 8 – Newark Liberty International
  • No. 9 – Dallas/Fort Worth International
  • No. 10 – Hartsfield-Jackson Atlanta International
---

This article originally appeared on CultureMap.com.

Announcing the winners of the 2026 Houston Innovation Awards

The winners are...

After weeks of anticipation, InnovationMap is proud to unveil the winners of the 2026 Houston Innovation Awards, our sixth-annual program honoring the best and brightest in the local innovation community.

This year, the Houston Innovation Awards recognized more than 40 finalists in 10 categories. They are shaping the future of Houston innovation across a variety of industries — from deep tech and energy to healthcare and education.

Finalists and winners were determined by our esteemed panel of judges, comprised of 2025 award winners, as well as InnovationMap editorial leadership. One winner was determined by the public via an online competition: Startup of the Year.

In the weeks leading up to this announcement, InnovationMap shined a spotlight on all of this year's outstanding finalists in our special editorial series. Learn more about all of them — and their outstanding achievements — here.

Without further ado, here are the 2026 Houston Innovation Awards winners:

Minority-founded Business: HexaSpec

Rice University spinout HEXASpec is working to improve the sustainability and thermal conductivity of semiconductor chips. The company has developed breakthrough inorganic fillers that allow graphic processing units (GPUs) to use less water and electricity and generate less heat. HEXASpec was founded in 2025 by CEO Tianshu Zhai, CTO Jing Zhang, and chief product officer Chen-Yang Lin. It has raised $800,000 in pre-seed funding and another $1.5 million in non-dilutive grants. The startup won the Liu Idea Lab for Innovation and Entrepreneurship's H. Albert Napier Rice Launch Challenge in 2024 and the 2025 Energy Venture Day and Pitch Competition during CERAWeek in the TEX-E student track in 2025. It was awarded a $500,000 National Science Foundation Partnership for Innovation grant last summer.

Female-founded Business: ARIX Technologies

Energytech startup ARIX Technologies has developed a semiautonomous VENUS crawler robot to detect corrosion under insulation before it becomes a failure. The robots climb insulated piping in refineries, chemical plants, and energy facilities to capture inspection data without removing insulation or building scaffolding. ARIX's inspection portal then turns information from the inspection into data a company can act on. ARIX was founded in 2017 by Dianna Liu, who serves as director, and Head of Product Petter Wehlin. Craig Malloy serves as CEO. The company has raised more than $22 million in seed funding and a Series A round.

Health Tech Business: Prana Surgical

Prana Surgical is developing a minimally invasive surgical platform for small, hard-to-reach lung nodules that may be cancerous. The company's Prana System cleared U.S. Food and Drug Administration (FDA) approval earlier this year. Prana Surgical was originally founded as Prana Thoracic in 2022. It has participated in numerous accelerators, including the Texas Medical Center Innovation Accelerator in 2023 and the IGNITE Health accelerator in 2022. It raised $6 million in Series A funding rounds in 2023 and 2024, with a Series B currently ongoing. The company is currently moving into the next stage of clinical validation and revenue generation in the U.S., in addition to preparing its manufacturing and commercial infrastructure for broader use.

Deep Tech Business: Venus Aerospace

Spacetech company Venus Aerospace is developing a high-thrust rotating detonation rocket engine (RDRE) that replaces the subsonic combustion used in conventional rocket engines. The RDRE is a compact, simpler engine that can deliver up to 15 percent greater efficiency for defense and space applications. It completed its first U.S. flight test of the engine last summer. Venus Aerospace was founded in 2020 by CEO Cassie Duggleby and CTO Andrew Duggleby. It raised a $20 million Series A in 2022 and $42 million Series A2 in 2025. It closed a $91 million Series B earlier this year and expanded its leadership team. The company is working toward longer-duration and higher-thrust testing and advancing its flight program.

Energy Transition Business: Hertha Metals

Hertha Metals produces lower-cost, lower-emission steel and high-purity iron. The company has developed a single-step process that uses natural gas as a direct reductant instead of metallurgical coal, which cuts production costs by more than 25 percent and emissions by up to 50 percent, according to the company. The same process produces high-purity iron needed for high-purity steels and rare earth magnets. The company says it aims to "re-industrialize America’s production of critical materials."

Scaleup of the Year: Hertha Metals

Founded by CEO Laureen Meroueh in 2022, Hertha Metals emerged from stealth in 2025 with more than $17 million in venture capital funding. The company closed a $133.65 million Series A in October and also broke ground on its $100M high-purity iron factory known as Chalyx in Conroe.

Incubator/Accelerator of the Year: Activate

Hard tech incubator Activate supports scientists in "the outset of their entrepreneurial journey." The Houston hub was introduced in 2024, and joins others in Boston, New York, and Berkley, California—where Activate is headquartered. It named its third Houston cohort this summer. The two-year program graduated its first class of Houston fellows in 2026 and saw its first alumni IPO from Houston-based Fervo Energy, which previously participated in a Berkley cohort. Nationally, it has supported 346 fellows and 276 companies since 2015. Those companies have raised more than $6 billion in follow-on funding, according to Activate. In Houston, it has supported local startups like Solidec, FlowCellutions and Orbital Arc. Activate Houston is led by managing director Jeremy Pitts, who co-founded Greentown Labs in Boston. It is based out of the Ion.

Startup of the Year (People's Choice): Progress Report

Progress Report is a K-12 learning-intelligence platform designed to go beyond identifying that a student is struggling. It traces performance to learning gaps and prerequisite skills, helping educators understand where a student is struggling and what may be causing it. Progress Report recently released a fully built production platform and launched pilots with 35 educators and 200 students across Texas and Arizona.

Mentor of the Year: Kyle Judah, Liu Idea Lab at Rice University

Kyle Judah is the executive director of Lilie, where he mentors pre-seed student startups. He also mentors through organizations like TEX-E, Greentown Labs and Activate. Some of the startups he's mentored include Helix Earth Technologies, Tierra Climate, Solidec, HexaSpec, SteerBio and many others.

"[Being a mentor] means helping to ensure that the most people possible have the best shot possible at making their company a successful reality," Judah says. "It means, at its root, opening the aperture for what is possible for people, by believing in them before anyone else even understands what their ambitions are. Because belief is the most infectious thing in the world. And before digging into the work in the trenches, most times founders need to kickstart their journey by having someone from the outside believe in them, when there's no real evidence to support that belief. So I guess, mentorship is a pure form of entrepreneurial faith."

2026 Trailblazer Legacy Award: Don Kendall Jr.

This year, the Trailblazer Legacy Award is given posthumously to Don Kendall Jr., who died in September while on a trip to the Republic of the Congo with the Jane Goodall Institute, one of the many organizations he was deeply involved with. Kendall served as general partner of New Climate Ventures, a Houston-based early-stage venture capital firm that invests in next-gen energy, materials and fuel technologies and startups. The firm's portfolio includes Houston-based clean energy companies like Solidec, Syzygy Plasmonics and Rheom Materials.

Outside of the clean energy space, Kendall also served on the boards of the Jane Goodall Institute, Earthwatch International and Ecological Defense Group. He also served as vice chair of Houston Zoo Inc. and chair of its Conservation Committee. "[Don] paired a keen eye for potential with the relentless drive to unlock it. For Mars Materials, his early backing carried us through a critical valley when we needed belief the most, and his presence as a personal mentor is profoundly missed," says Innovation Awards judge Aaron Fitzgerald.