With a SpaceX IPO, Musk could be the world's first trillionaire. Photo via Getty Images

Elon Musk's rocket company SpaceX will make its debut on Wall Street Friday, June 12, and both institutional and retail investors are expected to gobble up the 555.6 million shares going up for sale at $135 apiece. Musk, already the world's richest man, could become its first trillionaire.

SpaceX is likely to become the biggest IPO ever, with proceeds of around $75 billion. SpaceX hopes to become the first company to send people to Mars. In fact, part of Musk’s future compensation depends on SpaceX eventually establishing a colony of at least 1 million people on the red planet.

Why SpaceX is going public now

In a video conference on Musk's social media platform X, he told JPMorgan CEO Jamie Dimon that people have suggested for the last 10 years that he take SpaceX public. He's doing it now because the company plans to put 100,000 next-generation Starlink satellites into orbit. Deploying AI data centers in space is a “massive new growth base and you need capital for that,” he said.

Going public provides access to the capital that SpaceX needs. But it also exposes it to more scrutiny from shareholders and more regulatory oversight. That includes filing quarterly financial reports, which critics say incentivizes short-term thinking over longer-term planning and creates unnecessary costs for a company. Securities regulators are currently soliciting public comment on a proposal to require public companies to file the financial reports only twice every year.

How the IPO impacts the company

Musk will hold the majority of a special class of shares, giving him control over decisions related to company strategy, finances and personnel. On the latter, because of his ownership of most of these Class B shares, the only person who can fire Musk as CEO is Musk.

The company credits Musk with being the “driving force” behind its growth, innovation and success. But what happens if Musk is no longer in the picture? SpaceX warns that the loss of Musk could disrupt its ability to execute its strategy as well as hurt its “reputation and relationships with customers, partners and other stakeholders.”

The company also warns that finding a replacement with the same skills and experience as Musk would be time-consuming, if not nearly impossible. As Wedbush Securities analyst Dan Ives wrote Wednesday, “At the end of the day Musk is SpaceX and SpaceX is Musk.”

What could make or break SpaceX

Currently in the test phase, the gigantic reusable Starship rocket is key to SpaceX realizing Musk's ambitions. Much of the commercial space business hinges on SpaceX developing Starship’s capability to be fully reusable and hearty enough for a quick turnaround between flights. If that doesn't happen, SpaceX warns that putting data centers and satellites in space will take longer and cost more money, meaning it risks customers bailing on the company.

Analysts say that by pioneering reusable rockets, SpaceX has established a clear lead on competitors such as Blue Origin, led by Amazon founder Jeff Bezos. The Starlink satellite business competes with, among others, AST SpaceMobile – which is relying on a SpaceX rocket to send its latest generation of satellites into orbit next week.

The prospectus filed last week says SpaceX’s biggest potential market is the sale of business-oriented artificial intelligence products designed to transform how people get work done. It’s an opportunity SpaceX predicts would be worth $22.7 trillion if it could somehow dominate rivals like Anthropic, OpenAI and Microsoft in a highly competitive industry. But the prospectus shows no clear path to profitability for the xAI business, which merged with SpaceX earlier this year.

Why Wall Street is paying attention

If the SpaceX IPO is as successful, the stock could quickly join the Nasdaq 100, a widely followed index that tracks the 100 largest non-financial companies in the composite. That's important because some popular funds, such as the $460 billion QQQ exchange-traded fund, mimic the index and will automatically buy whatever is listed in the index.

Nasdaq recently changed its rules to allow select companies to enter the Nasdaq 100 after just 15 trading days.

S&P Dow Jones Indices, on the other hand, is sticking to established and more traditional thresholds that will not allow SpaceX or other companies with gargantuan IPOs faster entry into its S&P 500 index. That means even high-profile companies will still need to wait for their stocks to trade a full 12 months before they can enter the index.

Companies want to be in the S&P 500 in particular because it's arguably the most important index on Wall Street, with trillions of dollars either mimicking it exactly or benchmarked against it. Vanguard's VOO fund that tracks the S&P 500 has roughly $950 billion invested in it, for example.
The Texas bureau of the NYSE will open in 2026. Photo by Tomas Eidsvold on Unsplash

New York Stock Exchange Texas announces location for Dallas headquarters

NYSE Texas

A location has been chosen for The New York Stock Exchange Texas, the new Dallas-based offshoot of the The New York Stock Exchange in New York.

According to a release, the NYSE Texas has leased 28,000 square-feet of space at Old Parkland, the hospital-turned office space at 3819 Maple Ave. in Oak Lawn, where it will operate as a fully electronic equities exchange headquartered in Dallas. The property is owned by Dallas billionaire Harlan Crowe, who acquired it in 2006.

The NYSE is part of the Intercontinental Exchange, Inc., a global provider of technology and data. It was previously the NYSE Chicago, which will close once the bureau in Texas debuts.

They’ve also named a president to the Texas branch: Bryan Daniel, former chairman of the Texas Workforce Commission. In his new role over the NYSE Texas, Daniel will report to President of NYSE Group Lynn Martin.

Relocating from Chicago to Texas was a response to Texas' pro-business profile, Martin says in a statement.

“As the state with the largest number of NYSE listings, representing over $3.7 trillion in market value for our community, Texas is a market leader in fostering a pro-business atmosphere,” Martin says. “We are delighted to expand our presence in the Lone Star State, which plays a key role in driving our U.S. economy forward.”'

The move comes five months after the Texas Stock Exchange — AKA TXSE — announced plans to launch in Dallas and begin trading in 2026, pending approval from the U.S. Securities and Exchange Commission. The Texas Stock Exchange is backed by financial giants such as BlackRock, Citadel Securities, and Charles Schwab.

The NYSE expects the Texas location to open in 2026, where it will operate electronically, with stocks trading across multiple venues regardless of where they are first listed, according to the release.

---

This article originally appeared on CultureMap.com.

There's no crystal ball, but this researcher from Rice University is trying to see if some metrics work for economic forecasting. Photo via Getty Images

Houston researcher tries to crack the code on the Fed's data to determine economic outlook

houston voices

Research by Rice Business Professor K. Ramesh shows that the Fed appears to harvest qualitative information from the accounting disclosures that all public companies must file with the Securities and Exchange Commission.

These SEC filings are typically used by creditors, investors and others to make firm-level investing and financing decisions; and while they include business leaders’ sense of economic trends, they are never intended to guide macro-level policy decisions. But in a recent paper (“Externalities of Accounting Disclosures: Evidence from the Federal Reserve”), Ramesh and his colleagues provide persuasive evidence that the Fed nonetheless uses the qualitative information in SEC filings to help forecast the growth of macroeconomic variables like GDP and unemployment.

According to Ramesh, the study was made possible thanks to a decision the SEC made several years ago. The commission stores the reports submitted by public companies in an online database called EDGAR and records the IP address of any party that accesses them. More than a decade ago, the SEC began making partially anonymized forms of those IP addresses available to the public. But researchers eventually figured out how to deanonymize the addresses, which is precisely what Ramesh and his colleagues did in this study.

"We were able to reverse engineer and identify those IP addresses that belonged to Federal Reserve staff," Ramesh says.

The team ultimately assembled a data set containing more than 169,000 filings accessed by Fed staff between 2005 and 2015. They quickly realized that the Fed was interested only in filings submitted by a select group of industry leaders and financial institutions.

But if Ramesh and his colleagues now had a better idea of precisely which bellwether firms the Fed focused on, they still had no way of knowing exactly what Fed staffers had gleaned from the material they accessed. So the team decided to employ a measure called "tone" that captures the overall sentiment of a piece of text – whether positive, negative, or neutral.

Building on previous research that had identified a set of words with negatively toned financial reports, Ramesh and his colleagues examined the tone of all the SEC filings accessed by Fed staff between one meeting of the Federal Open Markets Committee (FOMC) and the next. The FOMC sets interest rates and guides monetary policy, and its meetings provide an opportunity for Fed officials to discuss growth forecasts and announce policy decisions.

The researchers then examined the Fed's growth forecasts to see if there was a relationship between the tone of the documents that Fed staff examined in the period between FOMC meetings and the forecasts they produced in advance of those meetings.

The team found close correlations between the tone of the reports accessed by the Fed and the agency’s forecasts of GDP, unemployment, housing starts and industrial production. The more negative the filings accessed prior to an FOMC meeting, for example, the gloomier the GDP forecast; the more positive the filings, the brighter the unemployment forecast.

Ramesh and his colleagues also compared the Fed's forecasts with those of the Society of Professional Forecasters (SPF), whose members span academia and industry. Intriguingly, the researchers found that while the errors in the SPF's forecasts could be attributed to the absence of the tonal information culled from the SEC filings, the errors in the Fed’s forecasts could not. This suggests both that the Fed was collecting qualitative information that the SPF was not—and that the agency was making remarkably efficient use of it.

"They weren’t leaving anything on the table," Ramesh says.

Having solved one mystery, Ramesh would like to focus on another; namely, how does the Fed identify bellwether firms in the first place?

Unfortunately, the SEC no longer makes IP address data publicly available, which means that Ramesh and his colleagues can no longer study which companies the Fed is most interested in. Nonetheless, Ramesh hopes to use the data they have already collected to build a model that can accurately predict which firms the Fed is most likely to follow. That would allow the team to continue studying the same companies that the Fed does, and, he says, “maybe come up with a way to track those firms in order to understand how the economy is going to move.”

------

This article originally ran on Rice Business Wisdom and was based on research from K. Ramesh is Herbert S. Autrey Professor of Accounting at Jones Graduate School of Business at Rice University.

Equity options can act as an alternative to credit default swaps for detecting a company’s credit risk. Photo via Getty Images

Rice research explains a new way to measure default risk for investors

houston voices

Up until the 2007-2009 financial crisis, credit default swaps (CDS) were a predominant method for predicting the probability of corporate default. CDS function like insurance for loan assets — if an asset defaults, the bank who purchased the CDS would recoup their loss. Higher-risk assets usually have higher premiums, and in this way the price of a CDS indicates the probability of default.

When the housing market crashed in 2007, the CDS market crashed along with it when banks had to pay out more than they had expected. The CDS market is not expected to ever return to its previous high, leaving a void in market-driven estimates for determining an asset’s default probability.

To fill that void, a team of researchers including Rice Business Professor Robert Dittmar created an alternative method for measuring default risk: equity options data. The team found that equity options not only correlate with CDS data in terms of accurate prediction of default but also provide additional insights on what types of assets are more likely to default, and when they will default.

There are two types of options, a call option, which is essentially a bet that a stock’s price will be higher than a contracted value (the strike price) and a put option, which is a bet that a stock’s price will be less than a contracted value.

A put is often viewed as an insurance contract — if you hold a stock, but also a put option on it, you limit your loss on the stock if the stock price falls.

“What we are looking at is essentially how expensive put options get,” says Dittmar. “If the market thinks a company is likely to default, it expects that its stock value will fall (almost to zero). As a result, put options, which represent insurance against this loss become more expensive. We are looking at how these option prices change to see if they inform us about the probabilities of default.”

According to Dittmar and his team, this approach has several advantages. 1) There are more stocks with options than CDS. 2) The CDS market is drying up whereas the option market remains liquid. And 3) Because of the nature of an option contract, and the fact that in principle equity holders have the lowest claim on a company’s assets, this approach may allow investors to predict losses in case of default.

The team looked at CDS quotes on 276 firms between 2002 and 2017, focusing attention on entities that had quote data available on one-year credit default swaps. The 15-year sample enabled the researchers to analyze the money lost through defaults over a longer period of time, including the 2007-2009 financial crisis.

Using equity options data as a predictor of default led to some interesting insights. First, there are two components that investors in corporate bonds think about when weighing default risk — the probability of default and (should there be a default) how much of the bond’s principal they will get back (i.e., recovery rate). “What we see is that credit ratings imply different levels of default thresholds, which may mean that investors believe that there are differences in the amount that debt holders will lose in the case of default,” says Dittmar.

Second, option-implied default probabilities correlate to historical changes in the economy. Default probabilities are higher in bad economic times and for firms with poorer credit ratings and financial positions. Default spikes are more likely during times of economic turbulence, such as the financial crisis of 2007-2009, which correlated with the decline of the CDS market after an onslaught of debt defaults during the recession. Assets are less likely to default during times of economic expansion. Over the period of 2013-2017, forecasted losses through defaults hovered around 15%.

The research sample ends in 2017, and the paper was published in 2020, about a month after the start of the coronavirus pandemic. Since then, there have been unprecedented changes in the economy, and some economists are anticipating another recession in 2023. With such instability in the market, multiple methods of predicting losses should be especially relevant. This research suggests that the equity options market may provide additional ways of finding the probability of these losses.

------

This article originally ran on Rice Business Wisdom and was based on research from Robert Dittmar, professor of finance at the Jones Graduate School of Business at Rice University.

Earnings report delays generally lead to drops in stock prices. Disclosure can soften this market reaction. Photo via Getty Images

Houston research: Is no news always bad news in market reports?

houston voices

Investors eagerly wait for the news in their earnings reports. When these reports don't appear on the expected date, investors worry — and stock prices often fall as a result. But what if managers could present late reports in a way that spared their companies?

Research by K. Ramesh, a professor at Rice Business, shows that managers' approach to late earnings reports can profoundly affect market reaction. When firms put off filing a report, it's up to managers to decide whether to speak up or stay quiet. Those who choose to talk about a postponement then must decide how, what and how much to say.

All earnings delays, whether they're attended by a statement or not, prompt negative market reaction, prior research suggests. But in his research, Ramesh, Herbert S. Autrey Professor of Accounting, wanted to learn more about the exact consequences of these late reports, and how managers can lessen the blowback.

To do this, Ramesh and a team of coauthors first looked at the incidence, timing and contents of a comprehensive sample of press releases announcing an earnings delay. Then they studied what those delays did to market value.

Conventional wisdom in the business press already suggested that investors viewed any announcement of a delayed earnings report as bad news. But finance theorists tell a more complicated story, one in which the market response might be partially shaped by managerial behavior. Subtle factors, they found, such as whether the impending delay is discussed or treated with silence, really can make a difference.

In the view of some theorists, merely announcing a delay can sometimes avert a drop in stock prices. Others argue that this isn’t necessarily the case, especially if the company discloses that the delay stemmed from legal concerns. The better approach: making it clear up front that reports aren't being postponed to hide disastrous information. But what if the information is indeed disastrous?

That may be the one case where disclosure won’t change much, Ramesh and his team found.

“Those companies that are in fact concealing disastrous results will experience no benefits (in the form of higher stock price) from revealing their true situation,” the research team wrote, “because the market will infer the worst from the manager’s decision not to announce the delay.” For this reason, they added, delayed earnings without a stated explanation prompt the most negative market reaction. As in so many areas of public relations, without a narrative, investors will infer a negative one of their own.

To better understand the impact of late reports, Ramesh and his coauthors built a comprehensive sample of 545 delay announcements by using a keyword search of the Dow Jones Factiva database between January 1, 1995, and December 31, 2009.

As conventional wisdom suggested, the study showed that announcements of late earnings reports led to negative market reactions. (Earlier studies have shown smaller firms are hit hardest by this dynamic, perhaps because investors assume large companies have more finely tuned financial reporting systems, so are less worried by their earnings delays).

Consistent with the anecdotal evidence, the average one-day abnormal stock return for the sample was -6.29 percent, while the median return was -2.27 percent. Both figures are economically and statistically significant.

The researchers next classified the announcements according to stated reason, dividing the delays into “Accounting” and “Non-Accounting” categories. “Accounting” explanations were subdivided into “Accounting Issue,” “Accounting Process” and “Rule Change.”

Meanwhile, “Non-Accounting” explanations were divided into “Business,” which linked the delay to some event such as divestitures or regulatory proceedings, and “Other,” which ranged from earthquakes to power outages. Finally, there were delays for no stated reason at all.

About two-thirds of the late announcements, the team found, were linked to accounting. When firms named a specific accounting issue as the cause for delay, the average abnormal return reached a statistically significant -8.15 percent. When managers explained that the accounting process was not complete, the average abnormal return was slightly lower, at -7.04 percent.

After accounting issues, business events drove most earnings delays. In theory, these events could have been either good or bad news. But the average abnormal return for the subsample was a statistically significant -3.74 percent — a reflection of the fact that most business events linked to late earnings reports tend to be negative.

Curiously, the average abnormal return for the grouping classified as “Other” was almost nil — at 0.53 percent. This suggests that the market does not penalize managers for events outside of their control that have little, if any, relevance to firm performance.

“No Reason,” the researchers found, was the most damaging explanation of all. Seven percent of the sample, or 37 out of 545 delays, came without a stated reason. The average abnormal return for these was a significant -10.41 percent, a greater negative number than the returns for any of the other reasons.

So what should managers do when a deadline is going to be busted? Bite the bullet and disclose the reasons, Ramesh suggests. For one thing, it helps limit legal exposure and preserve credibility. When the reason for the late report is innocuous, explaining to investors can also mitigate the market's displeasure. A caveat: While informing investors that a power outage caused earnings delay will calm jitters, disclosure may not make a difference if the company just can’t balance its books.

It's human nature, apparently, to read no news as bad news. Relaying something—anything—about the cause of a late report seems to soothe investors' nerves by preventing them from filling the silence themselves.

------

This article originally ran on Rice Business Wisdom and was based on research from K. Ramesh, Tiago Duarte-Silva, Huijing Fu and Christopher F. Noe. K. Ramesh is the Herbert S. Autrey Professor of Accounting at Jones Graduate School of Business at Rice University.

Research shows that some corporate executives skew earnings to influence the market and inflate share price. Photo via Pexels

Rice University research finds market outliers at risk of misreporting

houston voices

Say a company called CoolConsumerGoodsCo has just released its quarterly earnings report, revealing significantly higher profits than its consumer goods industry counterparts.

That result might spur analysts to slap a buy rating on the stock and investors to snap up shares. In an ideal world, the market wouldn't have to consider the possibility that the numbers aren't legit — but then again, it's not an ideal world. (Enron, anyone?)

Rice Business professors Brian R. Rountree and Shiva Sivaramakrishnan, along with Andrew B. Jackson at UNSW in Australia, studied what makes business leaders more likely to engage in fraudulent earnings reporting. Specifically, they focused on the relationship between this kind of misrepresentation and the degree to which a company's earnings are in line with the rest of its industry — a variable the researchers term "co-movements."

Many people are familiar with a similar variable, calculated using stock returns often referred to as a company's beta. The authors adapted the stock return beta to corporate earnings to see how a company's earnings move with earnings at the industry level.

The researchers hypothesized that the less in sync a company's earnings are with its industry, the higher the chance a company's leaders will manipulate earnings reports. They started with the well-accepted premise that corporations try to skew earnings reports to influence the market. The primary motive is typically to raise the company's stock price, as when an executive tries to "choose a level of bias" that balances potential fallout of getting caught against the benefits of a higher stock price.

To test their prediction, the professors analyzed a sample of enforcement actions taken by the U.S. Securities and Exchange Commission against companies for problematic financial reporting from 1970 to 2011 — although they noted that given the SEC's limited resources, the number of enforcement actions probably underestimates the actual amount of earnings manipulation in the market.

Their analysis revealed that firms with low earnings co-movements (meaning their earnings were out of sync with industry peers) were more likely to be accused by the SEC of reporting misdeeds. They concluded that the degree of earnings co-movement determines the probability of earnings manipulation. Put another way, earnings co-movements are a "causal factor" in the chances of earnings manipulations — and to a significant degree. The researchers found that firms who don't co-move with the market are more than 50 percent more likely to face an SEC enforcement action, compared with firms who are perfectly aligned with the market.

The researchers drilled deeper into the data to study whether the odds changed depending on the industry, since past research has indicated that the amount of competition in an industry works to constrain misreporting. That premise seems to hold true, the researchers concluded. In industries with more competitive markets, the impact of low co-movement on earnings manipulation is moderated.

They also studied whether the age of a firm played a part in the likelihood of earnings manipulation. Newer firms often rely more on stock compensation, which could be a motive for manipulating earnings reporting to drive up share price. Indeed, younger firms were more susceptible to misreporting when their earnings were out of whack with the rest of the marketplace.

Every firm faces some risk of misreporting, however. Even for public companies under analyst scrutiny, low co-movement proved to be a driver of earnings manipulation. But companies known for conservative reporting tend to be less likely to exaggerate their earnings, in general; these firms typically recognize losses in a more timely manner, the professors found.

These findings suggest a number of future lines of research. For example: When do executives underreport earnings? And can analyzing patterns related to cash flow reporting help better isolate earnings manipulation?

In the meantime, if you come across a company like CoolConsumerGoodsCo with an earnings report that's widely out of sync with the rest of its industry, you might think twice before rushing to buy in.

------

This article originally ran on Rice Business Wisdom and is based on research from Brian R. Rountree, an associate professor of accounting at the Jones Graduate School of Business at Rice University, and Shiva Sivaramakrishnan is the Henry Gardiner Symonds Professor of Accounting at Rice Business.

Ad Placement 300x100
Ad Placement 300x600

CultureMap Emails are Awesome

Meet the 40+ finalists for the 2026 Houston Innovation Awards

The Top Startups

Editor's note: We are just days away from unveiling the winners of the 2026 Houston Innovation Awards. Before the big reveal, we've compiled all of the coverage of this year's finalists. Get to know the 40+ finalists for nine awards categories below, then stay tuned to InnovationMap.com, where we'll announce the winners on Wednesday, November 18.

Minority-founded Business Finalists 

Our Minority-founded Businesses category honors innovative Houston startups founded or co-founded by BIPOC or LGBTQ+ representation. Five minority-founded businesses have been named finalists for the 2026 award. The finalists range from an AI edtech startup to a company operating in the floating offshore energy infrastructure sector.

They are: AI Made Fun, Deep Anchor Solutions, HEXASpec, Prana Surgical, and Torres Orbital Mining Inc. Read more.

Female-founded Business Finalists

Houston is home to many standout female founders, making inroads and breakthroughs in every industry. Our Female-founded Business category honors women-led startups that are shaping Houston innovation. Five female-founded businesses have been named finalists for the 2026 award. The finalists range from an AI startup for C-Suite execs to a company developing semi-autonomous crawler robots for corrosion detection.

They are: Adair, ARIX Technologies, Bairitone Health, FlowCellutions, and ParaDocs Health. Read more.

Health Tech Business Finalists

Houston has been driving medical innovation for decades and the local healthcare ecosystem continues to improve how patients are diagnosed, treated and cared for. The Health Tech Business category in our 2026 Houston Innovation Awards honors innovative startups within the health and medical technology sectors. Four forward-thinking businesses have been named finalists for the 2026 award. This year's finalists range from a startup developing miniaturized medical technologies for space to a company using AI to help develop cancer treatment plans.

They are: Bairitone Health, InformAI Inc., Prana Surgical, and Skybound MedTech. Read more.

Deep Tech Business Finalists

Houston has long been at the forefront of innovation, from NASA’s Johnson Space Center to its startup ecosystem using technology to disrupt industries. Our Deep Tech Business category honors innovative startups providing technology solutions based on substantial scientific or engineering challenges, including those in the AI, robotics and space sectors. Five deep tech companies have been named finalists for the 2026 award.

They are: Casimir, FocisAI, Machine Saver Inc., Square Robot, and Venus Aerospace. Read more.

Energy Transition Business Finalists

Houston is home to a growing number of startups reshaping what it means to be called the "Energy Capital of the World." Our Energy Transition Business category honors those innovative startups that are providing solutions within renewables, climatetech, clean energy, alternative materials, circular economy, and more. Five clean energy startups have been named finalists for the 2026 award. The finalists range from a lower-emission steel producer to a diagnostics platform developer working to support batteries used in data centers.

They are: Capwell Services, FlowCellutions, Hertha Metals, Mars Materials, and Solidec. Read more.

Scaleup of the Year Finalists

From IPOs to groundbreakings, some of Houston's most innovative companies reached major milestones this year. Our Scaleup of the Year category honors innovative later-stage startups that have recently reached a significant milestone in company growth. Three scaleups have been named finalists for the 2026 award.

They are: Erock, Hertha Metals, and Venus Aerospace. Read more.

Incubator/Accelerator of the Year Finalists

It takes a village to launch a business. That's where Houston's network of incubators and accelerators can step in, providing the resources, mentorship and community needed to push a fledgling company forward. Our Incubator/Accelerator of the Year category honors local organizations that are championing and fueling the growth of Houston startups. Three incubators and accelerators have been named finalists for the 2026 award. They support startups ranging from hard-tech companies to food and youth concepts.

They are: Activate, Impact Hub Houston, and MarMo Innovation. Read more.

Startup of the Year Finalists

Seven exceptional finalists are in the running for the title of Startup of the Year, which is our people's choice award in the annual Houston Innovation Awards. From innovative platforms benefiting the education, commerce, health, investment and IT sectors to next-gen memory technology and improvements for robotic supply chains, these startups are making an impact in Houston and beyond.

The finalists are: Fluxworks, IronLattice, Lumino, Progress Report, Rosarium Health, TokenRoster, and Thread. Read more.

Mentor of the Year Finalists

Houston’s thriving startup ecosystem is supported by a network of experienced leaders who work behind the scenes, investing their time and knowledge to help the next generation of entrepreneurs succeed. Our Mentor of the Year category honors those who dedicate their time and expertise to guide and support budding entrepreneurs. Six individuals have been named finalists for the 2026 award. They support promising startups in the medical tech, digital health, clean energy, hardware sectors and more.

They are: Al Danto, Rice University; Eric Rubenstein, New Climate Ventures; Jeremy Pitts, Activate; Joe Alapat, Liongard; Kyle Judah, Rice University's Liu Idea Lab for Innovation & Entrepreneurship; Rachel Bickham, Bickham Services Unlimited LLC. Read more.

Houston's new state-of-the-art academy FLAMA breaks ground at historic site

Groundbreaking Education

Houston’s newest school for arts and music broke ground in October in the city’s historic East End. The Frank Liu Jr. Academy for Music and Arts (FLAMA), a tuition-free charter school, will welcome students in pre-K through 8th grade next August.

Members of the Liu family, the school’s founding board members, elected officials, and East End community partners gathered at Buffalo Bayou Partnership’s historic Turkey Bend development for the official groundbreaking ceremony on October 8, which kicked off with a performance by the Kinder High School for the Performing and Visual Arts’ Mariachi group.

The new school is on a portion of the former Folgers Coffee Plant, located at 235 N. Norwood St. OMA, an international architectural firm known for its approach to urbanism, cultural projects, and adaptive reuse, is transforming the 1930s plant into a state-of-the-art educational facility.

“We’re excited to celebrate this milestone for FLAMA and look forward to seeing the transformation of the historic Folgers plant into a new home for music and arts education,” said Jason Long, one of the firm’s partners. “Like fine-tuning an instrument, our design recalibrates the existing industrial structure into an open, connected, and expressive environment for learning. FLAMA will be a new learning environment that builds on the character of the existing building while giving it new life for the community.”

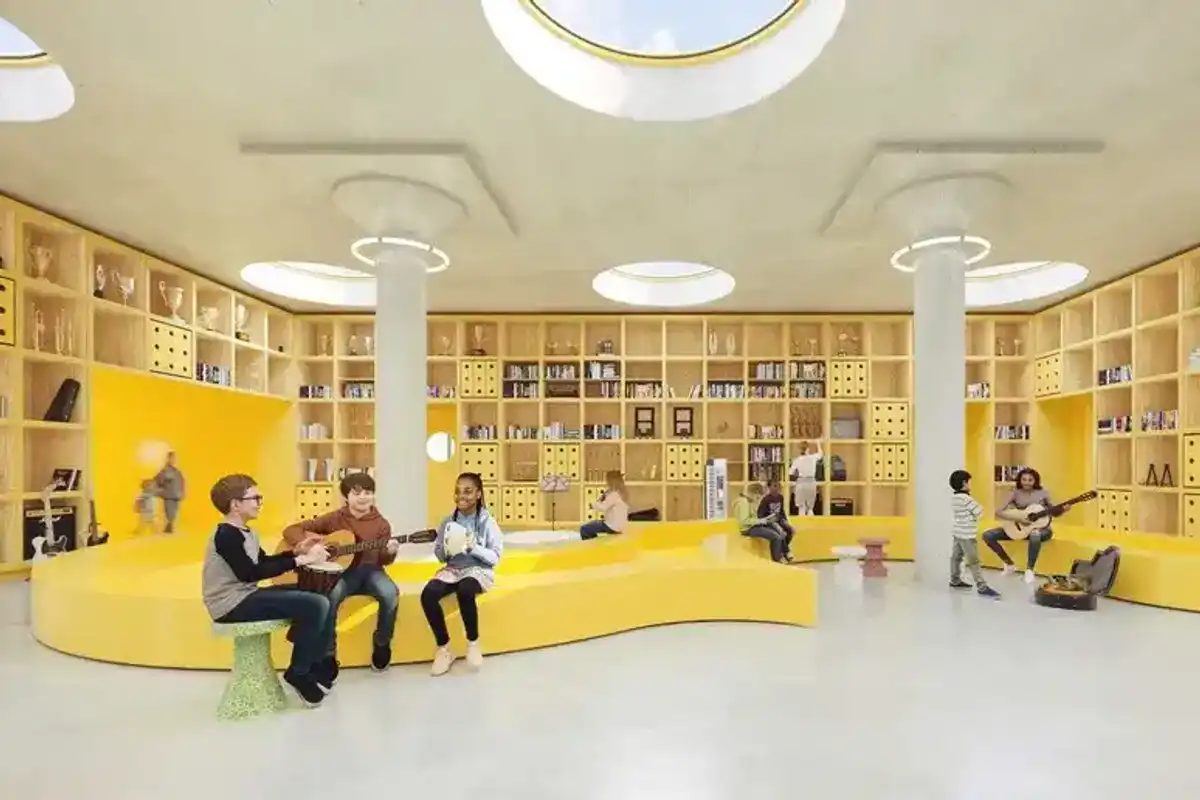
Flama academy Courtesy rendering

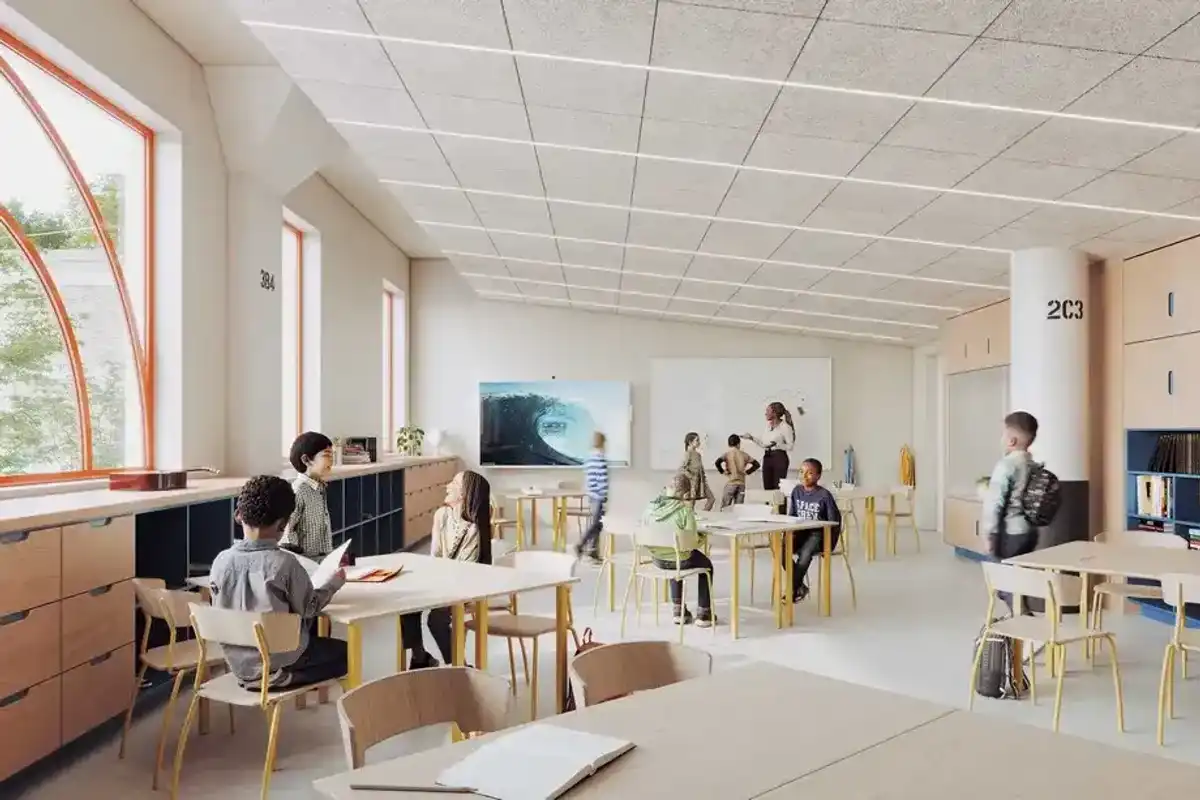
Unfolding across three stories, the school draws inspiration from Montessori education principles, which prioritize openness, independence, and collective learning through shared “neighborhoods.”

It all begins when students, families and guests enter through a private courtyard. The welcoming space will change the building’s original industrial facade into a brightly colored, kid-friendly spot, complete with yellow and green blocks spelling out the school’s name. The original windows will be restored to preserve the building’s historic character and upgraded to meet contemporary energy standards. Similarly, all of the school’s classrooms are located around the building’s perimeter, providing an abundance of natural light.

Inside, FLAMA’s three stories are divided so that younger students will find their classrooms at the school’s base, and they will move upward through the school as they progress through grade levels. The ground level has a common area for younger kids that could host drum circles, movement classes, or “breakout play.”

Children in first and second grade have their own larger open space, with an eye-catching staircase, that's inspired by the curve of a French horn. The space lends itself to everything from small gatherings to performances by the school’s early musicians.

As students progress through third grade and up, they’ll find FLAMA’s upper floors created to meet their growing artistic and intellectual needs. One example is the open library, a shared spot for students in third through fifth grades. It has flexible furniture that can transform the space into a place for group study and project work, as well as one that can host after-school activities. Directly above this library is a second common room for middle schoolers where students in sixth, seventh, and eighth grades can study.

FLAMA academy Courtesy rendering

These two libraries are connected by an F-shaped floor opening that references both the F-hole of a string instrument and the forte symbol. Musicians know this curly f as a note indicating them to play a passage with strength. That could easily be a metaphor for the school itself, which will combine high-quality education with rigorous academics. This visual cue emphasizes FLAMA’s desire for music and art instruction to amplify learning across reading, writing, math, and science.

“This will be a place where children can discover their talents, families can find opportunities close to home, and music and art can open the doors to a stronger education,” said Congresswoman Sylvia Garcia, who attended the groundbreaking. “I know how much it matters when someone brings opportunity within the reach of a child.”

Dr. R. Scott Allen, FLAMA’s founding superintendent and former principal of Kinder HSPVA, spoke about the school’s vision to pair a rigorous, engaging academic opportunity with deep immersion in music and visual arts.

Congressman Christian Menefee, State Senator Carol Alvarado, and Houston City Councilmember Mario Castillo also delivered remarks at the ceremony, speaking about the school’s power to not only transform Houston’s Second, Third, and Fifth Ward communities, but also bring incredible education opportunities to students. Former Mayor Annise Parker, former State Board of Education Member Staci Childs, State Representative Christina Morales, and Houston City Councilmembers Joaquin Martinez and Sallie Alcorn also attended the event.

“In this city, known for our undeniable contributions to music and arts, the gap has never been ability or talent; it has always been opportunity, and opportunity can be built,” said Kirby Liu, who spoke at the groundbreaking, memorializing his late brother’s vision of arts education for the youngest Houstonians. “When it comes to opportunity being foreclosed on our children, we will try like hell to bust those damned doors down.”

The Frank Liu Jr. Foundation has pledged $20 million in financial support during FLAMA’s first years of operation. Applications are now open for kindergarten and first grade for the 2027-2028 school year.

---

This article first appeared on CultureMap.com.

New manufacturing facility breaks ground at NASA’s Johnson Space Center

making space

HITT Contracting has broken ground on NASA’s Applied Spaceflight Fabrication Facility (ASFF) at Johnson Space Center, the Washington, D.C.-based construction firm announced late last month.

The project, known as Building 70, will house a high-bay machine shop to support component production for future NASA space missions, according to HITT. The 37,625-square-foot building is the first part of a larger goal to create an engineering complex that unites assembly space, lab capabilities and manufacturing at JSC. It will consolidate machining equipment and operations that are currently spread across multiple campus buildings into one location.

The project broke ground in October at JSC’s Historic District. The Houston Business Journal reports construction is expected to wrap in August of 2028.

“This project will modernize facilities that support America’s space missions,” PJ Ross, chief financial officer at HITT, said in a LinkedIn post. “Proud of our team and partners as we begin construction that will advance aerospace testing and innovation.”

HITT Contracting is one of seven companies awarded infrastructure contracts by NASA earlier this year for work at JSC. According to NASA, the construction contracts “[support] up to $300 million in upgrades to mission‑support facilities, utilities, and equipment across the NASA Johnson campus.”

Construction Drive reports that HITT will also renovate Building 13 South on the JSC campus as part of the $300 million initiative.

“Building for precision manufacturing starts with understanding how the space needs to perform,” Todd Hudson, vice president at HITT Contracting, added in the release. “Our team brings the technical expertise and collaborative approach to deliver a facility that meets the Johnson Space Center’s needs today and supports the next generation of spaceflight innovation. We’re proud to continue our partnership with NASA.”

NASA also recently announced awards as part of its expanded Moon Base exploration, science and infrastructure capabilities. Houston-based Intuitive Machines and seven other spacetech companies, including SpaceX, Blue Origin and Firefly Aerospace, were selected to receive funding.

The awards are part of the next phase of NASA’s CLPS (Commercial Lunar Payload Services) initiative, which will grant the companies a combined total of up to $10 billion over 10 years.

Intuitive Machines and Webster-based MEI Technologies were also awarded contracts this past summer from NASA to develop robots for exploring the surface of Mars. Read more here.