New research reveals that companies often “opinion shop” to shape their financial reality. Photo via rice.edu

Firms often have to estimate the “fair value” of their investments, meaning they have to declare what an asset is worth on the market. To avoid the potential for bias and manipulation, companies will use third-party services to provide an objective estimate of their assets’ fair value.

But nothing prevents a company from seeking multiple third-party estimates and choosing whichever one suits their purpose.

In a recent study, Shiva Sivaramakrishnan (Rice Business) and co-authors Minjae Koo (The Chinese University of Hong Kong) and Yuping Zhao (University of Houston) examine two motives for switching third-party evaluators: “opinion shopping” and “objective valuation.”

Firms that opinion shop are looking for a third-party source to make their investments look better on paper. For example, if Service A says an asset is worth $80 — and that means the company would have to take an accounting loss — the company might switch to Service B, which says the asset is worth $90. By using the higher estimate from Service B, the company avoids a loss.

Opinion shopping can be a dangerous practice, both on a macro level and for the specific firms that engage in it. Not only does it reduce the quality of fair value estimates for everyone, it means some company assets are potentially overvalued. And if those assets ever decline in value for real, the company will eventually take a loss.

Moreover, opinion shopping opens the door to managerial opportunism. If assets are valued more highly, managers are likely to receive credit and potentially use that perceived accomplishment to advance their careers.

There are reasons for companies to go the other way. In the hypothetical scenario above, our company might switch from Service B ($90) to Service A ($80) to receive a more accurate and objective estimate. The “objective valuation” motive helps companies meet regulatory requirements and ensure estimates reflect true market value. What’s more, the objective valuation motive helps curb managerial buccaneering.

The study looks at when and why life insurance companies will switch their third-party review service. The team finds that both motives — opinion shopping and objective valuation — are common. Sometimes companies want to better align their fair value estimates with what similar assets are trading for in the market. Other times, they want assets to look better on paper.

Of the two motives, opinion shopping is the more dominant, particularly when they are in conflict with each other. On the whole, evidence suggests that companies switch price sources strategically to inflate estimates and avoid losses, rather than to get more accurate estimates.

The study has implications for investors, regulators and researchers. “Opinion shopping” could be prevalent in non-financial industries, as well — especially public firms with capital market incentives. More disclosure around price sources could improve estimate reliability.

Future research could examine asset valuation practices and motives in other sectors such as banking, real estate and equity investments. Are some industries more prone to opinion shopping than others? What factors make opinion shopping or objective valuation more likely? Are there certain signals or patterns that indicate when a company is opinion shopping versus seeking objectivity?

Answers to these questions could help discern acceptable from unacceptable third-party source switching. And understanding if certain types of companies are more at risk could help regulators and auditors focus their efforts.

The bottom line:

Accurate accounting matters. While external sources are better for measuring the fair value of any given asset, companies can distort the very concept of fair value estimates by changing their source. More rigor, transparency and auditing around price sources could curb manipulation and improve estimate reliability.

------

This article originally ran on Rice Business Wisdom and was based on research from Shiva Sivaramakrishnan, the Henry Gardiner Symonds Professor of Accounting at Rice Business.
Research shows that some corporate executives skew earnings to influence the market and inflate share price. Photo via Pexels

Rice University research finds market outliers at risk of misreporting

houston voices

Say a company called CoolConsumerGoodsCo has just released its quarterly earnings report, revealing significantly higher profits than its consumer goods industry counterparts.

That result might spur analysts to slap a buy rating on the stock and investors to snap up shares. In an ideal world, the market wouldn't have to consider the possibility that the numbers aren't legit — but then again, it's not an ideal world. (Enron, anyone?)

Rice Business professors Brian R. Rountree and Shiva Sivaramakrishnan, along with Andrew B. Jackson at UNSW in Australia, studied what makes business leaders more likely to engage in fraudulent earnings reporting. Specifically, they focused on the relationship between this kind of misrepresentation and the degree to which a company's earnings are in line with the rest of its industry — a variable the researchers term "co-movements."

Many people are familiar with a similar variable, calculated using stock returns often referred to as a company's beta. The authors adapted the stock return beta to corporate earnings to see how a company's earnings move with earnings at the industry level.

The researchers hypothesized that the less in sync a company's earnings are with its industry, the higher the chance a company's leaders will manipulate earnings reports. They started with the well-accepted premise that corporations try to skew earnings reports to influence the market. The primary motive is typically to raise the company's stock price, as when an executive tries to "choose a level of bias" that balances potential fallout of getting caught against the benefits of a higher stock price.

To test their prediction, the professors analyzed a sample of enforcement actions taken by the U.S. Securities and Exchange Commission against companies for problematic financial reporting from 1970 to 2011 — although they noted that given the SEC's limited resources, the number of enforcement actions probably underestimates the actual amount of earnings manipulation in the market.

Their analysis revealed that firms with low earnings co-movements (meaning their earnings were out of sync with industry peers) were more likely to be accused by the SEC of reporting misdeeds. They concluded that the degree of earnings co-movement determines the probability of earnings manipulation. Put another way, earnings co-movements are a "causal factor" in the chances of earnings manipulations — and to a significant degree. The researchers found that firms who don't co-move with the market are more than 50 percent more likely to face an SEC enforcement action, compared with firms who are perfectly aligned with the market.

The researchers drilled deeper into the data to study whether the odds changed depending on the industry, since past research has indicated that the amount of competition in an industry works to constrain misreporting. That premise seems to hold true, the researchers concluded. In industries with more competitive markets, the impact of low co-movement on earnings manipulation is moderated.

They also studied whether the age of a firm played a part in the likelihood of earnings manipulation. Newer firms often rely more on stock compensation, which could be a motive for manipulating earnings reporting to drive up share price. Indeed, younger firms were more susceptible to misreporting when their earnings were out of whack with the rest of the marketplace.

Every firm faces some risk of misreporting, however. Even for public companies under analyst scrutiny, low co-movement proved to be a driver of earnings manipulation. But companies known for conservative reporting tend to be less likely to exaggerate their earnings, in general; these firms typically recognize losses in a more timely manner, the professors found.

These findings suggest a number of future lines of research. For example: When do executives underreport earnings? And can analyzing patterns related to cash flow reporting help better isolate earnings manipulation?

In the meantime, if you come across a company like CoolConsumerGoodsCo with an earnings report that's widely out of sync with the rest of its industry, you might think twice before rushing to buy in.

------

This article originally ran on Rice Business Wisdom and is based on research from Brian R. Rountree, an associate professor of accounting at the Jones Graduate School of Business at Rice University, and Shiva Sivaramakrishnan is the Henry Gardiner Symonds Professor of Accounting at Rice Business.
In a recent study, a Rice Business professor found that board members actually need incentives — both short- and long-term — to act in stakeholders' best interests. Getty Images

Rice University research finds executive board members are driven by incentives

Houston voices

If you're a stockholder, you may envision your investment helmed by a benevolent, all-knowing board of directors, sitting around a long finely-grained wooden table, drinking coffee, their heads buried in PowerPoint charts as they labor to plot the best course for the company. Too often, however, you can't take for granted that a company's board will steer it wisely.

Companies choose directors because they offer rich and varied experience in the business world. Many who serve on boards, moreover, are CEOs of other corporations, or have headed big companies in the past. As of October 2018, for example, six of the 11 directors on Walmart's board and eight of 13 on AT&T's board hold CEO or CFO positions in other firms. So it's easy to assume that board members will act in the best interests of stockholders.

But in a recent study, Rice Business professor Shiva Sivaramakrishnan found that board members actually need incentives — both short- and long-term — to act in stakeholders' best interests.

Corporations usually compensate board members with stock options, grants, equity stakes, meeting fees, and cash retainers. How important is such compensation, and what sort of incentives do board members need to perform in the very best interests of a company? Sivaramakrishnan joined co-author George Drymiotes to trace how compensation impacts various aspects of board performance.

Recent literature in corporate governance has already stressed the need to give boards of directors explicit incentives in order to safeguard shareholder welfare. Some observers have even proposed requiring outside board members to hold substantial equity interests. The National Association of Corporate Directors, for example, recommended that boards pay their directors solely with cash or stock, with equity representing a substantial portion of the total, up to 100 percent.

To the extent that directors hold stock in a company, their actions are likely influenced by a variety of long-and short-term incentives. And while the literature has focused mainly on the useful long-term impact of equity awards, the consequences of short-term incentives haven't been as clear. Moreover, according to surveys, most directors view advising as their primary role. But this role also has received little attention.

To scrutinize these issues, the scholars used a simple model, which assumes the board of directors perform three roles: contracting, monitoring and consulting. The board contracts with management to provide productive input that improves a firm's performance. By monitoring management, the board improves the quality of the information conveyed to managers. By serving in a consulting role, the board makes managers more productive, which, in turn, means higher expected firm output.

This model allowed the scholars to better understand the relationship between the board of directors and the company's managers, as well as with shareholders. The former was particularly important to take into account, because conflict between a board and managers is typically unobservable and can be costly.

The results were surprising. Without short-term incentives, the researchers found, boards did not effectively fulfill their multiple roles. Long-term inducements could make a difference, they found, but only in some aspects of board performance.

While board members were better advisors when given long-term motivations, short-term incentives were better motivators for performing well in their other corporate governance roles, according to the research, which tied specific aspects of board compensation to particular board functions.

Restricted equity awards provided the necessary long-term incentives to improve the efficacy of the board's advisory role, the scholars found, but only the short-term incentives, awarding an unrestricted share or a bonus based on short-term performance, motivated conscientious monitoring.

The scholars also examined managerial misconduct. Board monitoring, they concluded, lowered the cost of preventing such wrongdoing — but only if the board had strong short-term incentives in place.

Even at the highest rungs of the corporate ladder, in other words, short-term self-interest is the greatest motivator. Maybe it's not surprising. In the corporate world, acting for one's own benefit is a given — so stockholders need to look more closely at those at the very top. Like everyone else, board directors need occasional brass rings within easy reach to do their best.

------

This story originally ran on Rice Business Wisdom.

Shiva Sivaramakrishnan is the Henry Gardiner Symonds Professor in Accounting at the Jesse H. Jones Graduate School of Business at Rice University.

Ad Placement 300x100
Ad Placement 300x600

CultureMap Emails are Awesome

UTHealth Houston officially opens new tower in TMC's Helix Park

open for innovation

UTHealth Houston School of Public Health recently opened its new state-of-the-art tower in the Texas Medical Center’s Helix Park.

The 350,000-square-foot, 10-story campus at 1930 Old Spanish Trail was celebrated with an official ribbon-cutting ceremony on Oct. 28. The $229 million project will consolidate all UTHealth Houston School of Public Health operations into one facility. It will also connect students who are at the Austin, Brownsville, Dallas, El Paso and San Antonio campuses with peers and faculty through digital and distance learning.

Disciplines taught in the new tower will include epidemiology, genetics, nutrition, health policy, data science and health promotion, UTHealth shared when the building first broke ground in 2023.

Architects Kirksey Architecture and Smith Group designed the building, and Vaughn Construction served as general contractor. The facility features labs for studying human disease, classrooms and spaces to support interdisciplinary and community-based research, a broadcast studio and a teaching kitchen. A skybridge over Old Spanish Trail connects the new tower with a plaza that's shared with MD Anderson.

“This new facility reflects the kind of forward-looking investment that will serve Texans for generations,” Janiece Longoria, vice chairman of the UT System Board of Regents, said in a news release. “By creating an environment where talented people can learn, collaborate, and pursue new ideas, UTHealth Houston is building capacity to meet the challenges of tomorrow while strengthening its impact across our state.”

UTHealth says the system aims for the new campus to expand on collaborative research efforts and continue graduate education, as enrollment at the School of Public Health has increased by 27 percent over the last five years.

“This new building, with its state-of-the-art education technology and learning environment, will strengthen and advance the school’s mission to educate and train the next generation of experts who will advance scientific discovery, shape evidence-based health policy, and lead innovative solutions to the complex health challenges in communities throughout Texas and across the nation,” Kevin Morano, senior vice president, provost and chief academic officer of UTHealth Houston, added in a news release.

Attending the ceremony were Dr. Melina R. Kibbe, UTHealth Houston president and Alkek Williams Distinguished Chair; Eric Boerwinkle, dean, M. David Low Chair in Public Health and Kozmetsky Family Chair in Human Genetics at the School of Public Health; Texas State Representative Lauren Ashley Simmons, Texas House District 146; representatives of the offices of Senator John Cornyn and Harris County Commissioner Rodney Ellis; and Dr. Theresa Tran, director of the Houston Health Department.

"This building represents far more than a home for our school,” Boerwinkle added in the release. “It represents the people who make our mission possible: the faculty, staff, and students who fill each laboratory and classroom with curiosity, discovery, and purpose to improve the population’s quality of life.”

Rice University breaks ground on new innovation hub, The Arc

breaking ground

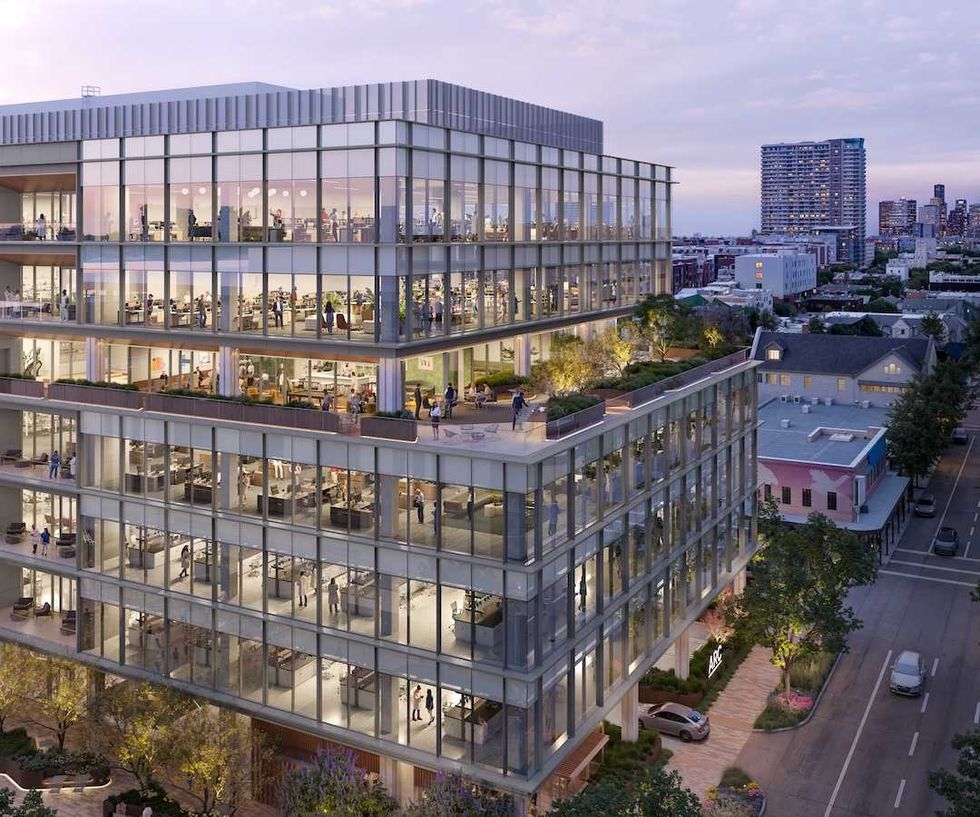
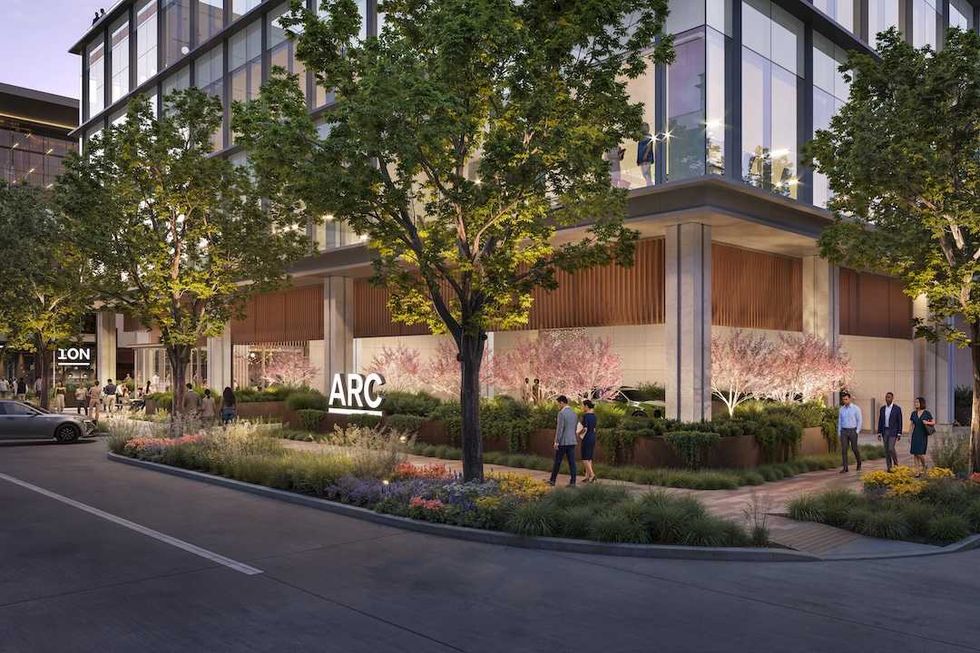
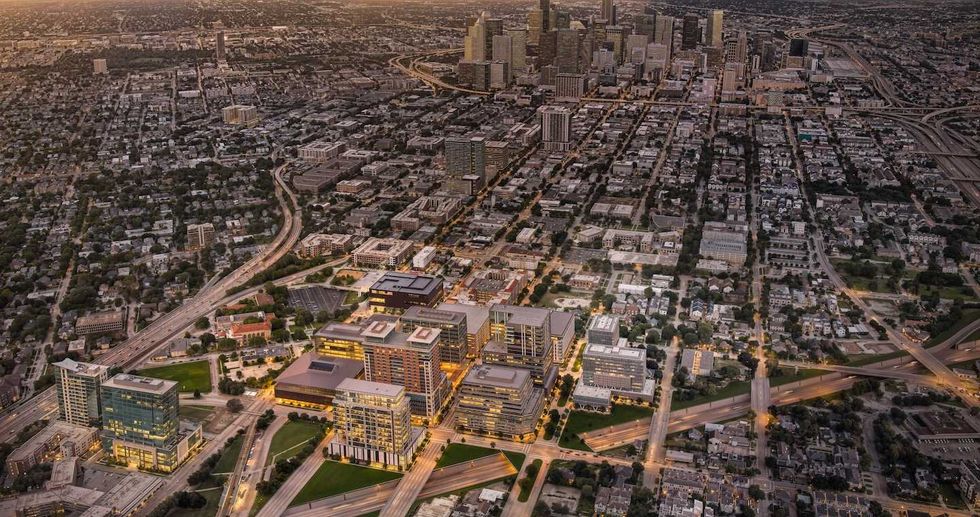
Construction is officially underway on Rice University's The Arc in Houston’s Ion District.

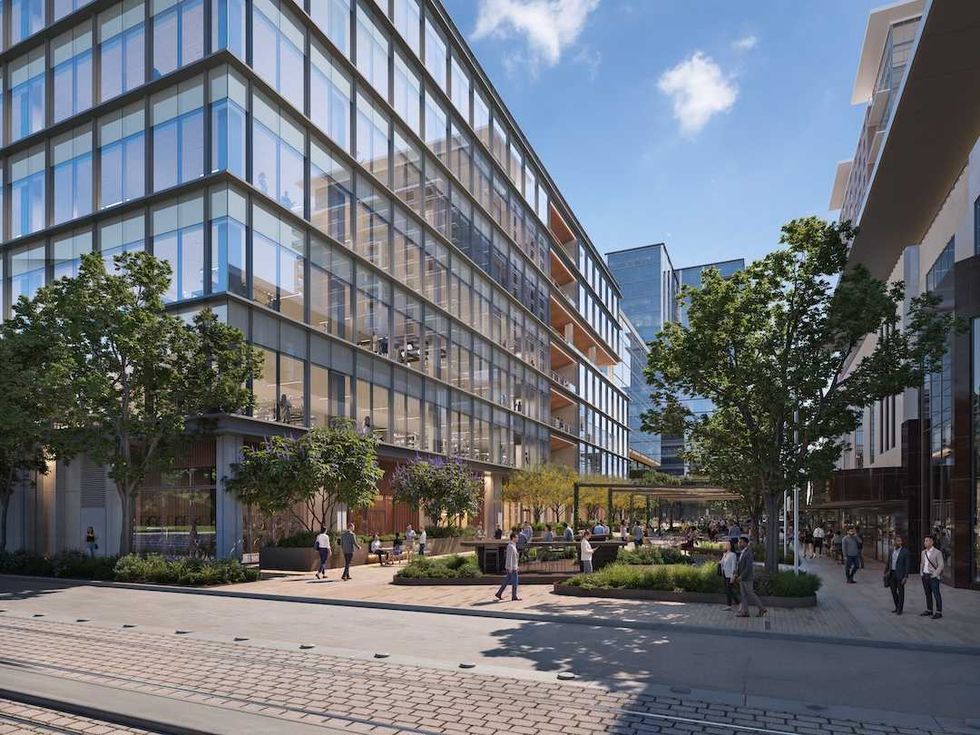
The university broke ground on the 200,000-square-foot research, corporate innovation and office building on Nov. 4. The facility will share a plaza with the existing Ion building, fostering collaboration within the innovation space, according to Rice.

“The Arc will bring Rice’s extraordinary research and talent and Houston’s impactful innovation ecosystem into even closer connection with the industries and innovators working to solve some of the world’s most consequential challenges,” Rice President Reginald DesRoches said in an announcement. “That constant exchange of ideas and expertise will help move discoveries more rapidly from the laboratory to real-world impact.”

Construction is scheduled to be completed by Q2 2028. Rice Real Estate Co. is developing the project, and Rice University will occupy about 80,000 square feet in the building (about 40 percent). Preleasing has begun, with floor plans ranging from 28,000 to 31,000 square feet.

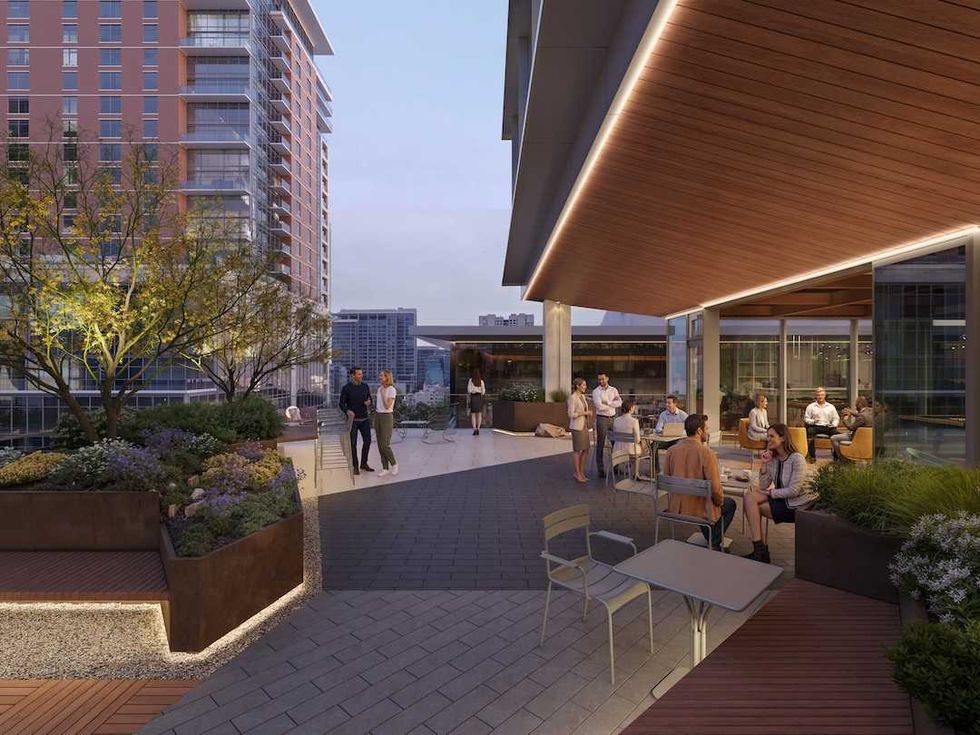
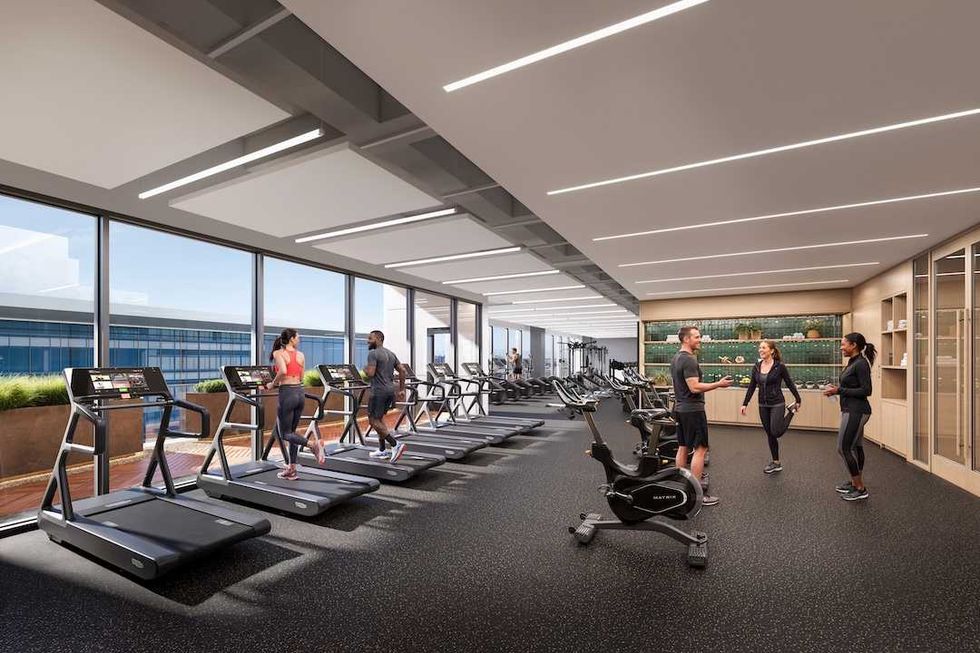
The Arc will feature conference and meeting spaces, an amenity lounge, fitness center, outdoor plazas, underground parking, and on-site retail and dining, according to the release.

It aims to host tenants focused on artificial intelligence and machine learning, data science, robotics, quantum science and engineering and energy, including Rice's new AI Foundry.

Rice says the AI Foundry will be a space where university experts and partners can support organizations with AI challenges. Rice recently committed to hiring 75 new AI-focused faculty and announced plans to launch a new Master of Artificial Intelligence (MAI) next fall.

“The AI Foundry is exactly the kind of collaboration the Arc is designed to enable,” Amy Dittmar, the Howard R. Hughes Provost and executive vice president for academic affairs at Rice, added in the release. “By bringing Rice researchers together with industry partners in a shared environment, we can accelerate the movement of ideas from research into practical applications while helping organizations build the capabilities they need to succeed as AI continues to evolve.

Developers of The Arc are targeting LEED Gold certification by incorporating smart building automation and energy-saving features into the project's design. Rice first announced the project in September 2025.

Rendering courtesy Bogza

Houston battery tech startup FlowCellutions acquired by Katy energy co.

M&A

Katy-based TerraFlow Energy, an energy storage and infrastructure company, has acquired Houston-based battery technology startup FlowCellutions. Financial terms weren’t disclosed.

FlowCellutions still operates under its established name, but with the tagline “A TerraFlow Energy Company.” Becca Segel, founder and CEO of FlowCellutions, now runs the business as its president.

FlowCellutions specializes in electrochemical sensing, diagnostics, analytics, and testing that offer insights into battery chemistry, charging capabilities, and system performance.

“FlowCellutions has always been focused on developing better ways to understand what is happening inside a flow battery and using that information to improve how these systems perform,” Segal said in a press release. “Joining TerraFlow gives us the opportunity to apply that work at a much larger scale while continuing to build the capabilities and expertise that make FlowCellutions unique.”

The FlowCellutions platform supports data centers and other heavy users of power. It’s designed to help reduce operating costs, prevent failures and costly downtime, and extend battery lifetime from about seven years to more than 30 years.

Segel founded the company in 2022. A member of Greentown Labs, the company raised more than $2 million in non-dilutive funding and received $1.5 million in National Science Foundation funding earlier this year.

FlowCellutions is one of five finalists in the Energy Transition Business category of InnovationMap’s 2026 Houston Innovation Awards.

“FlowCellutions brings a depth of scientific and technical expertise that fits naturally with where TerraFlow is going,” Jon Parrella, CEO of TerraFlow, said in the release.

“As we move from developing these systems to deploying them at commercial scale, understanding performance at a deeper level matters,” he said. “Bringing FlowCellutions into TerraFlow strengthens that capability and gives both teams more opportunity to advance the technology.”TerraFlow, founded in 2024, develops long-duration energy storage and power infrastructure for data centers, industrial facilities, utilities and other large power consumers.

---

This article originally appeared on EnergyCapitalHTX.com.