Here's what this wealth management adviser wants you to know before you start your business. Photo via Getty Images

May is Small Business Appreciation month and as a Houstonian, small business owner and wealth management advisor, I understand firsthand the questions, considerations and challenges involved with navigating the nuanced world of small business ventures.

In 2005, I started RSF Wealth Management with my business partner. RSF Wealth Management is a Houston-based firm of Northwestern Mutual focused on comprehensive, collaborative and educational financial planning.

Understanding that every startup is different, I believe there are a few key strategies to keep in mind when starting a business.

1. Create a comprehensive business plan

Any lucrative, viable business has to start with a good plan that outlines what you will need to grow revenue and thrive long-term. Creating this strategic business outline will serve as a roadmap for your beginning years as well as a marketing tool when finding investors. The business plan should highlight what your outlook is for the next five years, how you will leverage your product to make profit, and how much money you will need to achieve and maintain financial success—no matter what scenario may come your way.

2. Establish a solid financial foundation

As most startup businesses take up to five years to turn over profit, it is important to receive funding or set aside extra cash, even if it’s a small amount. My advice to small business owners is to make sure you have at least six months to a years’ worth of liquidity before starting a business venture. Emergency savings funds and other cash reserves can help to cover the operational and overhead costs to startups. If you don’t have enough in your personal savings or cash reserves, there are loan options for small businesses, including the paycheck protection program loan, economic injury disaster loan, traditional SBA 7(A) loan and SBA express bridge loan.

3. Verify everything is documented

Documenting everything is crucial when building the foundation of your business for both legal and tax purposes. Not only will this help if something goes wrong with your business, but it will also keep formal structure between you and your business partner. All startups should complete a buy-sell agreement, which details how your partners’ share will be obtained by the remaining partners in case of their death or leave. I also recommend filing a morality clause contract, which requires all employees to comply to behavioral standards during the life of their contract.

4. Review your insurance and tax options

Small business owners should be regularly reviewing their tax and insurance options to ensure they are updated to reflect changing business needs. For instance, the SECURE Act 2.0 tax credit is a new incentive designed to make it easy and affordable for small businesses to offer employer-sponsored retirement plans. The new legislation allows increased tax credits to small businesses to encourage plan sponsorship and improve retirement readiness.

Additionally, business insurance for startups can help cover costs associated with property damage or liability claims. For example, disability overhead expense insurance provides your business with money to pay for everyday operational expenses in the event you’re unable to work due to an illness or injury. Generally, if you provide coverage for employees and cover the premium, you will be able to deduct those costs as a business expense.

Despite the difficulties of making the jump from employee to entrepreneur, 5 million new businesses were created in 2022 according to a study by the US Census Bureau. New businesses are being created every day and with the excitement of starting a new business also comes the complexities and challenges associated with a new business venture.

Financial advisors and industry experts can help you create a plan, understand what loan option is right for you and how much you will need to have in cash reserves to ensure you can securely and stably run your new business. No matter the size or operation of your business, financial advisors can help document your finances and connect you with the right attorney or accountant to set you up for long-term success.

------

Keith Rollins is a wealth management advisor with Northwestern Mutual and a founding partner of RSF Wealth Management.
Ad Placement 300x100
Ad Placement 300x600

CultureMap Emails are Awesome

Eli Lilly breaks ground on $6.5B pharmaceutical factory in Houston

lilly lands

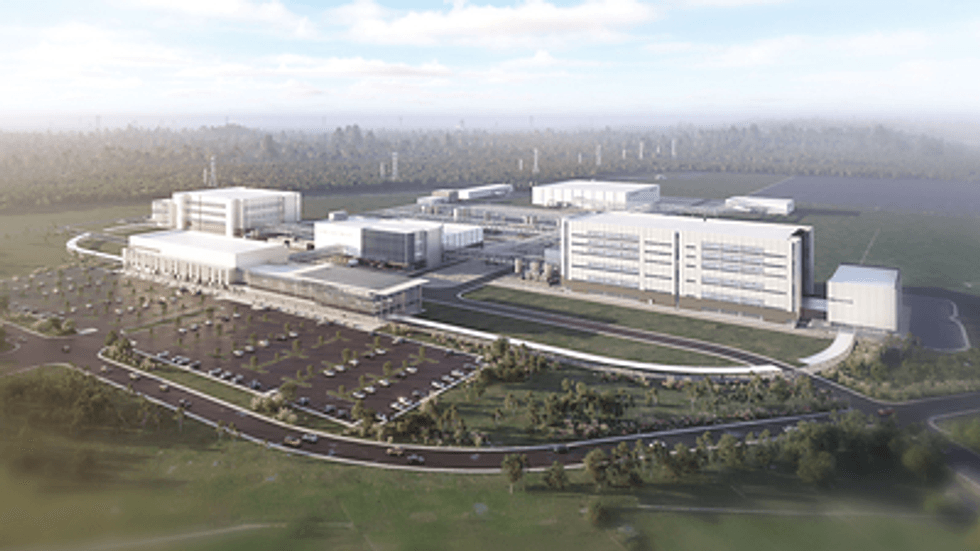
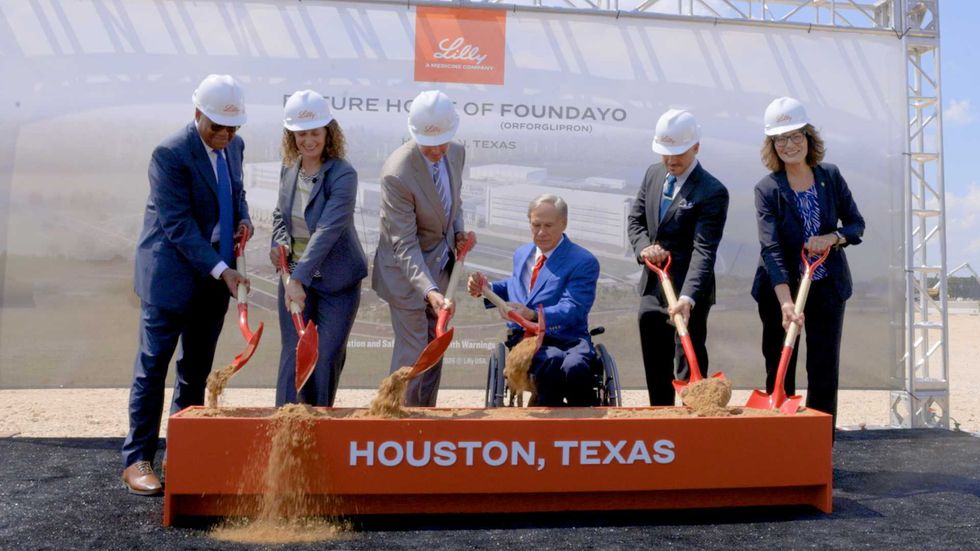
Leading pharmaceutical company Eli Lilly broke ground today, Sept. 21, on its $6.5 billion manufacturing site at Houston's Generation Park.

The 236-acre, state-of-the art factory is expected to come online in 2030 and will manufacture Foundayo, the company's first synthetic oral GLP-1 medication, as well as other advanced therapeutics.

"We are thrilled to break ground on our latest ‘medicines made in America’ site in the great state of Texas," David Ricks, Lilly chair and CEO, said in a prepared statement. "This $6.5 billion investment will help change the game for tens of millions of people suffering from overweight, obesity and its consequences like diabetes. We will make and ship Lilly’s latest products from Texas to people here at home and around the world.”

Houston was up against more than 300 locations in the U.S. for the factory, as part of Lilly’s $50 billion investment in domestic medicine production that has launched 10 manufacturing sites since 2020. Lilly first announced Houston had been selected for the site last September.

Photo via gov.texas.gov

As Abbott mentioned, the site is expected to create hundreds of jobs, and will hire engineers, scientists, operations personnel and lab technicians once up and running. It will create 4,000 construction jobs while being built.

In an effort to support workforce development, Lilly also announced a $12.5 million commitment to Houston's San Jacinto College in addition to a $2.5 million charitable donation to the San Jacinto College Foundation. The funding will go toward hands-on training, equipment and facilities to support future technicians, operators, maintenance professionals, and other manufacturing talent, according to Lilly. The charitable donation will fund scholarships for students.

"This relationship will build a strong, sustainable talent pipeline for Lilly while creating meaningful, high-demand career opportunities across our region,” Brenda Hellyer, chancellor of San Jacinto College, said in the release.

"When you invest in a place like Houston, you invest in its people first," Edgardo Hernandez, executive vice president and president of Lilly Manufacturing Operations, added. "This facility will run on the talent of this community, powered by our relationship with San Jacinto College. We're hiring across the greater Houston area to help residents build careers close to home."

Rendering courtesy Eli Lilly

Lilly previously said it chose Generation Park, a 4,300-acre, master-planned commercial district near Lake Houston, because of factors such as financial incentives, access to utilities and transportation and the region’s business-friendly environment. Generation Park is home to campuses for San Jacinto College and Lone Star College.

Since Lilly first announced plans for the site, another fellow pharma giant has made plans to move into Generation Park. Bristol Myers Squibb Co. announced last month that it would build a $2.3 billion factory in the district. The site is expected to manufacture small molecule, biologic and antibody-drug conjugates and will also come online around 2030. Read more here.

UH Health names leader of new digital health institute

new exec

Recently launched UH Health has named the first-ever executive director of its new Institute for Digital Healthcare Transformation at the University of Houston.

Beto López has been tapped to lead the new initiative that aims to help develop and commercialize health care technologies centered around university research.

Launched in August, the Institute for Digital Healthcare Transformation leans on experts from UH’s engineering, medicine, business, law and other departments and will connect with industry partners. It will initially focus on mobile health applications, sensors, wearables and artificial intelligence, according to UH.

“Most digital health initiatives and commercialization efforts start with the technology and hope adoption follows. But the translation gap isn't a science problem — it’s a scaffolding problem between researchers, the community and the market,” López said in a news release. “I've spent the past 10 years building that scaffolding in places that weren’t wired for it, and I'm looking forward to building it here at UH to help ensure new health care technologies reach the people and communities that can benefit from them most.”

López previously spent 10 years at San Francisco-based innovation consultancy company IDEO, where he led over 100 projects for Fortune 500 companies and public agencies. He co-founded and served as managing director of the Design Institute for Health at UT Austin’s Dell Medical School; and also co-founded a social venture studio/venture capital fund focused on health care innovation. He worked alongside Houston’s Legacy Community Health during the COVID-19 pandemic.

“Beto understands that breakthrough technology alone doesn't transform health care — it has to be designed around the needs of patients, providers and communities and have a clear path into practice,” Jonathan McCullers, vice president for health affairs at UH, added in the news release. “His experience spanning academic health care and venture capital equips him to bring together researchers, health care organizations, entrepreneurs and investors. This makes him uniquely suited to lead this institute and help turn the university's innovation into solutions that improve people's lives.”

The University of Houston launched UH Health, its new cross-disciplinary academic venture, in July. It aims to bring together the university's health-related education, research and community impact under one umbrella.

ExxonMobil gets approval for $5B Texas Gulf Coast carbon capture project

CCS Expansion

Spring-based ExxonMobil has won approval from the Texas Railroad Commission for a $5 billion carbon capture and storage project in East Texas.

Dominic Genetti, senior vice president of CCS at ExxonMobil, told The Financial Times, which broke the news, that the Railroad Commission’s action is a “major milestone” that lets the company keep expanding along the Gulf Coast. In a 2-1 vote, commissioners authorized a carbon sequestration permit for the project.

“The Railroad Commission clearly recognizes the important role carbon capture and storage can play in meeting growing global demand for lower-carbon products while supporting new jobs and economic growth,” Genetti said.

The U.S. Environmental Protection Agency (EPA) approved ExxonMobil’s Rose CCS project last year.

The project will enable the company to inject about 53 metric tons of industrial customers’ carbon emissions into three underground wells it drilled in the Beaumont-Port Arthur area. Over a 13-year period, ExxonMobil plans to inject about 4 million metric tons per year into the Fleming and Upper Frio rock formations, according to Carbon Herald.

ExxonMobil says it owns the world’s first and largest CCS system, comprising 1,300 miles of CO2 pipeline and secure storage sites. Seventy percent of the pipelines are along the Gulf Coast.

The company ramped up its CCS business in 2023 with the $4.9 billion purchase of Denbury, which owned about 1,000 miles of CO2 pipelines.

“Our expertise, combined with Denbury’s talent and CO2 pipeline network, expands our low-carbon leadership and best positions us to meet the decarbonization needs of industrial customers while also reducing emissions in our own operations,” ExxonMobil Chairman and CEO Darren Woods said when the deal closed.

In January, Genetti wrote in a post on ExxonMobil’s website that the company is committed to CCS “for the long haul.”

“CCS is not new technology, but it’s flown relatively under the radar compared with the attention that production of hydrocarbons commands,” he wrote. “Now, as the world becomes more aware of the need to reduce emissions, CCS finally has a brighter spotlight and a broader runway to scale up.”

The company also announced this week that it has begun CCS operations at a direct reduced iron facility in Convent, Louisiana. The project will capture, transport and store up to 800,000 metric tons of CO2 per year, according to the company.

---

This article first appeared on EnergyCapitalHTX.com.