Tim Latimer, CEO and co-founder of Fervo Energy. Photo courtesy of Fervo Energy

Houston geothermal unicorn Fervo Energy has closed $421 million in non-recourse debt financing for the first phase of its flagship Cape Station project in Beaver County, Utah.

Fervo believes Cape Station can meet the needs of surging power demand from data centers, domestic manufacturing and an energy market aiming to use clean and reliable power. According to the company, Cape Station will begin delivering its first power to the grid this year and is expected to reach approximately 100 megwatts of operating capacity by early 2027. Fervo added that it plans to scale to 500 megawatts.

The $421 million financing package includes a $309 million construction-to-term loan, a $61 million tax credit bridge loan, and a $51 million letter of credit facility. The facilities will fund the remaining construction costs for the first phase of Cape Station, and will also support the project’s counterparty credit support requirements.

Coordinating lead arrangers include Barclays, BBVA, HSBC, MUFG, RBC and Société Générale, with additional participation from Bank of America, J.P. Morgan and Sumitomo Mitsui Trust Bank, Limited, New York Branch.

“As demand for firm, clean, affordable power accelerates, EGS (Enhanced Geothermal Systems) is set to become a core energy asset class for infrastructure lenders,” Sean Pollock, managing director, project Finance at RBC Capital Markets, said in a news release. “Fervo is pioneering this step change with Cape Station, a vital contribution to American energy security that RBC is proud to support.”

The oversubscribed financing marks Cape Station’s shift from early-stage and bridge funding to a long-term, non-recourse capital structure, according to the news release.

“Non-recourse financing has historically been considered out of reach for first-of-a-kind projects,” David Ulrey, CFO of Fervo Energy, said in a news release. “Cape Station disrupts that narrative. With proven oil and gas technology paired with AI-enabled drilling and exploration, robust commercial offtake, operational consistency, and an unrelenting focus on health and safety, we have shown that EGS is a highly bankable asset class.”

Fervo continues to be one of the top-funded startups in the Houston area. The company has raised about $1.5 billion prior to the latest $421 million. It also closed a $462 million Series E in December.

According to Axios Pro, Fervo filed for an IPO that would value the company between $2 billion and $3 billion in January.

---

This article first appeared on EnergyCapitalHTX.com.
Cart.com announced a $25 million series C extension round and $105 million in debt refinancing from investment manager BlackRock. Photo courtesy of Cart.com

Houston e-commerce unicorn secures $130M in financing

scaling up

Houston-based Cart.com, which operates a multichannel commerce platform, has secured $105 million in debt refinancing from investment manager BlackRock.

The debt refinancing follows a recent $25 million series C extension round, bringing Cart.com’s series C total to $85 million. The scaleup’s valuation now stands at $1.2 billion, making it one of the few $1 billion-plus “unicorns” in the Houston area.

“Scaleup” refers to a startup that has achieved tremendous growth and has maintained a stable workforce, among other positive milestones. Airbnb, Peloton, and Uber are prime examples of businesses that evolved from startup to scaleup.

Cart.com says the new term loan facility from BlackRock consolidates its venture debt into one package “at competitive terms.” Those terms weren’t disclosed.

The company says the refinancing will enable it to expand into new markets and improve its technology, including its Constellation OMS order management system.

“Cart.com is one of the fastest-growing providers of commerce and logistics solutions today, and I’m excited to partner with BlackRock as we continue to aggressively invest to help our customers operate more efficiently,” Omair Tariq, the company’s founder and CEO, says in a news release.

Through a network of 14 fulfillment centers, Cart.com supports over 6,000 customers and 75 million orders per year.

"BlackRock is pleased to support Cart.com as it advances its mission to unify digital and physical commerce infrastructure," says Keon Reed, a director at BlackRock. “This latest facility underscores our confidence in the company’s differentiated product offerings and financial strategy as it enters its next stage of growth.”

Exectras says the money will go toward beefing up its merchant portfolios, developing infrastructure, and carrying out organic growth. Photo by Hero Images

Houston small biz services co. secures $30M in financing from Austin firm

support smbs

Missouri City-based Exectras, a provider of services for small and midsize businesses, has secured debt financing of up to $30 million from Austin-based investment manager Tacora Capital.

Exectras says the money will go toward beefing up its merchant portfolios, developing infrastructure, and carrying out organic growth.

Founded in 2007, Exectras offers an array of discounted business services to small and midsize businesses, including merchant services, payroll, health insurance, and workers’ compensation insurance. In addition, Exectras originates and acquires credit card residuals and merchant portfolios representing billions of dollars in annual processing volume.

“We are grateful to have a partner in Tacora that understands our business and is committed to our growth. As entrepreneurs themselves, they understand how valuable our services can be. We look forward to an extended partnership,” Joseph Cherry, president and CEO of Exectras, says in a news release.

Denver-based SFT Capital arranged the deal.

Last year, Tacora launched its inaugural debt fund, which contains $350 million. Peter Thiel, a billionaire venture from Silicon Valley, is the fund’s main investor. He poured $250 million into the investment vehicle.

Formation of the Tacora fund comes amid a surge in private debt financing. Asset management giant BlackRock forecasts that the global market for private debt will soar to $3.5 trillion by 2028.

P97 Networks, a Houston-based mobile payments company, has fresh funds to scale its operations. Photo via Getty Images

Houston-based mobile commerce startup secures $40M to scale its SaaS business

money moves

A Houston company that has created a mobile commerce platform for the convenience retail, fuels marketing, and automotive industries has fresh funding to support its growth.

P97 Networks has raised $40 million of venture debt financing from an affiliate of Peak Rock Capital, a leading middle-market private investment firm, according to a news release from the company.

“We will use this new capital to fund P97’s high growth initiatives, which include accelerating user adoption across our Consumer Engagement platform, Energy Transition programs for our clients, and our Mobility Services platform,” said Donald Frieden, president and CEO of P97, in the release.

Frieden says that over the past 18 months, the company has doubled the number of sites on its platform, which includes five largest energy brands in the world, and over 60,000 convenience retail sites in North America.

“With this new capital, we will continue to grow our install base and strategic partnerships," Frieden continues. "We look forward to working with Peak Rock to bring our company to its next stage of growth and further establish our position as the leading provider of mobile commerce technology in the convenience & fuel retailing industry.”

P97's last raise was a series B round in 2019 that saw contribution from Accenture. The startup's series A closed in 2014 and was led by Emerald Technology Ventures.

The company's platform operates as a payments platform as well as a digital marketing solution that prioritizes payment security and customer customization.

“P97 has become the industry standard in the convenience retail and fuel marketing industry, and we are very pleased to help the company reach its next level of scale and growth,” says Nick Basso, managing director at Peak Rock Capital. “We are excited by the compelling opportunities ahead for P97 as the market for mobile payment solutions continues to expand and gain broad adoption by consumers.”

Last year, P97 announced a partnership with Chevron that meant implementing the digital platform into more than 7,800 Chevron and Texaco retail stations across the country.

“Chevron is dedicated to providing products and services for people on the go and continuing to address their needs in the retail of the future,” says Harry Hazen, Chevron senior manager of Americas Marketing, in a 2021 press release. “Our collaboration with P97 strengthens that commitment – delivering a premium consumer experience at Chevron and Texaco locations by enabling our offerings with consistency, speed, consumer value, and security.”

Ad Placement 300x100
Ad Placement 300x600

CultureMap Emails are Awesome

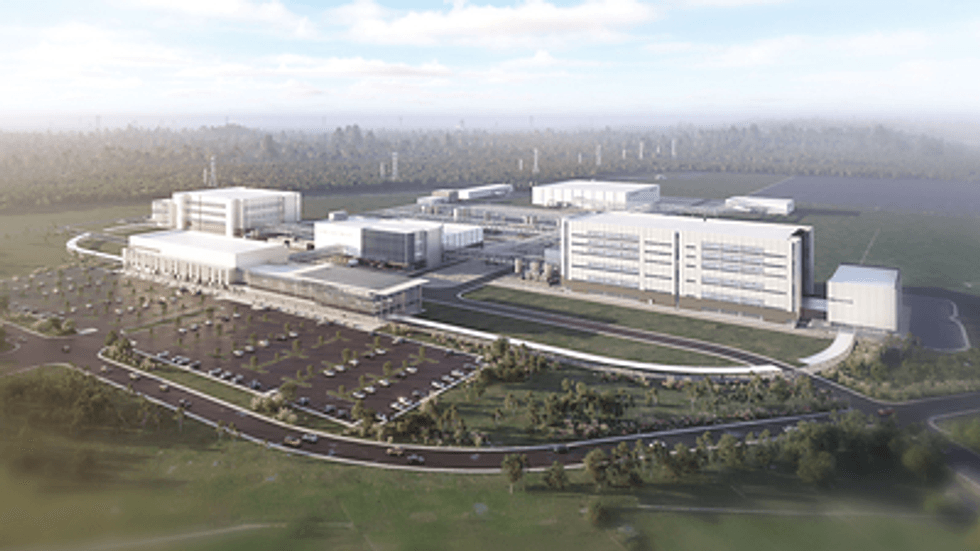
Eli Lilly breaks ground on $6.5B pharmaceutical factory in Houston

lilly lands

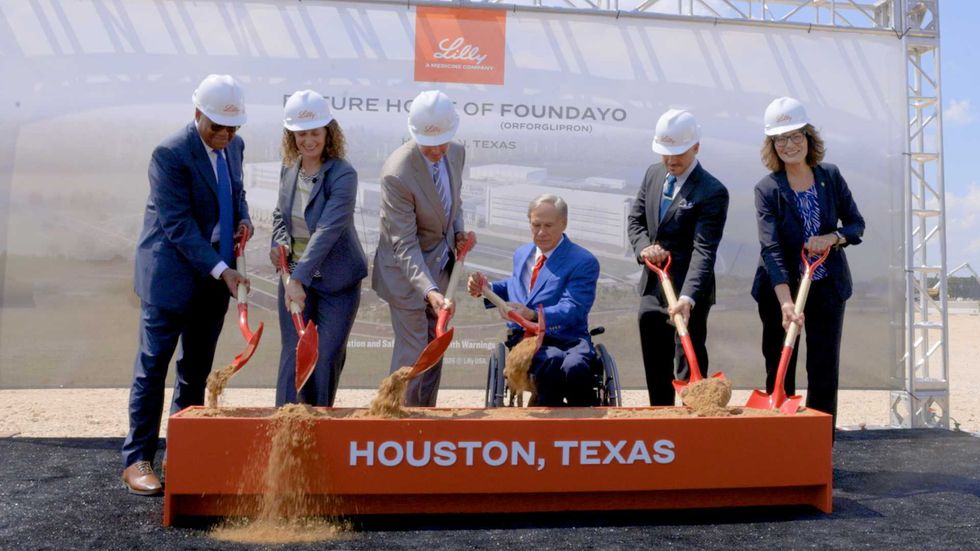
Leading pharmaceutical company Eli Lilly broke ground today, Sept. 21, on its $6.5 billion manufacturing site at Houston's Generation Park.

The 236-acre, state-of-the art factory is expected to come online in 2030 and will manufacture Foundayo, the company's first synthetic oral GLP-1 medication, as well as other advanced therapeutics.

"We are thrilled to break ground on our latest ‘medicines made in America’ site in the great state of Texas," David Ricks, Lilly chair and CEO, said in a prepared statement. "This $6.5 billion investment will help change the game for tens of millions of people suffering from overweight, obesity and its consequences like diabetes. We will make and ship Lilly’s latest products from Texas to people here at home and around the world.”

Houston was up against more than 300 locations in the U.S. for the factory, as part of Lilly’s $50 billion investment in domestic medicine production that has launched 10 manufacturing sites since 2020. Lilly first announced Houston had been selected for the site last September.

Photo via gov.texas.gov

As Abbott mentioned, the site is expected to create hundreds of jobs, and will hire engineers, scientists, operations personnel and lab technicians once up and running. It will create 4,000 construction jobs while being built.

In an effort to support workforce development, Lilly also announced a $12.5 million commitment to Houston's San Jacinto College in addition to a $2.5 million charitable donation to the San Jacinto College Foundation. The funding will go toward hands-on training, equipment and facilities to support future technicians, operators, maintenance professionals, and other manufacturing talent, according to Lilly. The charitable donation will fund scholarships for students.

"This relationship will build a strong, sustainable talent pipeline for Lilly while creating meaningful, high-demand career opportunities across our region,” Brenda Hellyer, chancellor of San Jacinto College, said in the release.

"When you invest in a place like Houston, you invest in its people first," Edgardo Hernandez, executive vice president and president of Lilly Manufacturing Operations, added. "This facility will run on the talent of this community, powered by our relationship with San Jacinto College. We're hiring across the greater Houston area to help residents build careers close to home."

Rendering courtesy Eli Lilly

Lilly previously said it chose Generation Park, a 4,300-acre, master-planned commercial district near Lake Houston, because of factors such as financial incentives, access to utilities and transportation and the region’s business-friendly environment. Generation Park is home to campuses for San Jacinto College and Lone Star College.

Since Lilly first announced plans for the site, another fellow pharma giant has made plans to move into Generation Park. Bristol Myers Squibb Co. announced last month that it would build a $2.3 billion factory in the district. The site is expected to manufacture small molecule, biologic and antibody-drug conjugates and will also come online around 2030. Read more here.

UH Health names leader of new digital health institute

new exec

Recently launched UH Health has named the first-ever executive director of its new Institute for Digital Healthcare Transformation at the University of Houston.

Beto López has been tapped to lead the new initiative that aims to help develop and commercialize health care technologies centered around university research.

Launched in August, the Institute for Digital Healthcare Transformation leans on experts from UH’s engineering, medicine, business, law and other departments and will connect with industry partners. It will initially focus on mobile health applications, sensors, wearables and artificial intelligence, according to UH.

“Most digital health initiatives and commercialization efforts start with the technology and hope adoption follows. But the translation gap isn't a science problem — it’s a scaffolding problem between researchers, the community and the market,” López said in a news release. “I've spent the past 10 years building that scaffolding in places that weren’t wired for it, and I'm looking forward to building it here at UH to help ensure new health care technologies reach the people and communities that can benefit from them most.”

López previously spent 10 years at San Francisco-based innovation consultancy company IDEO, where he led over 100 projects for Fortune 500 companies and public agencies. He co-founded and served as managing director of the Design Institute for Health at UT Austin’s Dell Medical School; and also co-founded a social venture studio/venture capital fund focused on health care innovation. He worked alongside Houston’s Legacy Community Health during the COVID-19 pandemic.

“Beto understands that breakthrough technology alone doesn't transform health care — it has to be designed around the needs of patients, providers and communities and have a clear path into practice,” Jonathan McCullers, vice president for health affairs at UH, added in the news release. “His experience spanning academic health care and venture capital equips him to bring together researchers, health care organizations, entrepreneurs and investors. This makes him uniquely suited to lead this institute and help turn the university's innovation into solutions that improve people's lives.”

The University of Houston launched UH Health, its new cross-disciplinary academic venture, in July. It aims to bring together the university's health-related education, research and community impact under one umbrella.

ExxonMobil gets approval for $5B Texas Gulf Coast carbon capture project

CCS Expansion

Spring-based ExxonMobil has won approval from the Texas Railroad Commission for a $5 billion carbon capture and storage project in East Texas.

Dominic Genetti, senior vice president of CCS at ExxonMobil, told The Financial Times, which broke the news, that the Railroad Commission’s action is a “major milestone” that lets the company keep expanding along the Gulf Coast. In a 2-1 vote, commissioners authorized a carbon sequestration permit for the project.

“The Railroad Commission clearly recognizes the important role carbon capture and storage can play in meeting growing global demand for lower-carbon products while supporting new jobs and economic growth,” Genetti said.

The U.S. Environmental Protection Agency (EPA) approved ExxonMobil’s Rose CCS project last year.

The project will enable the company to inject about 53 metric tons of industrial customers’ carbon emissions into three underground wells it drilled in the Beaumont-Port Arthur area. Over a 13-year period, ExxonMobil plans to inject about 4 million metric tons per year into the Fleming and Upper Frio rock formations, according to Carbon Herald.

ExxonMobil says it owns the world’s first and largest CCS system, comprising 1,300 miles of CO2 pipeline and secure storage sites. Seventy percent of the pipelines are along the Gulf Coast.

The company ramped up its CCS business in 2023 with the $4.9 billion purchase of Denbury, which owned about 1,000 miles of CO2 pipelines.

“Our expertise, combined with Denbury’s talent and CO2 pipeline network, expands our low-carbon leadership and best positions us to meet the decarbonization needs of industrial customers while also reducing emissions in our own operations,” ExxonMobil Chairman and CEO Darren Woods said when the deal closed.

In January, Genetti wrote in a post on ExxonMobil’s website that the company is committed to CCS “for the long haul.”

“CCS is not new technology, but it’s flown relatively under the radar compared with the attention that production of hydrocarbons commands,” he wrote. “Now, as the world becomes more aware of the need to reduce emissions, CCS finally has a brighter spotlight and a broader runway to scale up.”

The company also announced this week that it has begun CCS operations at a direct reduced iron facility in Convent, Louisiana. The project will capture, transport and store up to 800,000 metric tons of CO2 per year, according to the company.

---

This article first appeared on EnergyCapitalHTX.com.