This week's roundup of Houston innovators includes Tim Crain of Intuitive Machines, Chelsea Williams of Northwestern Mutual, and Nicolaus Radford of Nauticus Robotics. Photos courtesy

Editor's note: In this week's roundup of Houston innovators to know, I'm introducing you to three local innovators across industries — from space tech to robotics — recently making headlines in Houston innovation.

Tim Crain, co-founder and CTO of Intuitive Machines
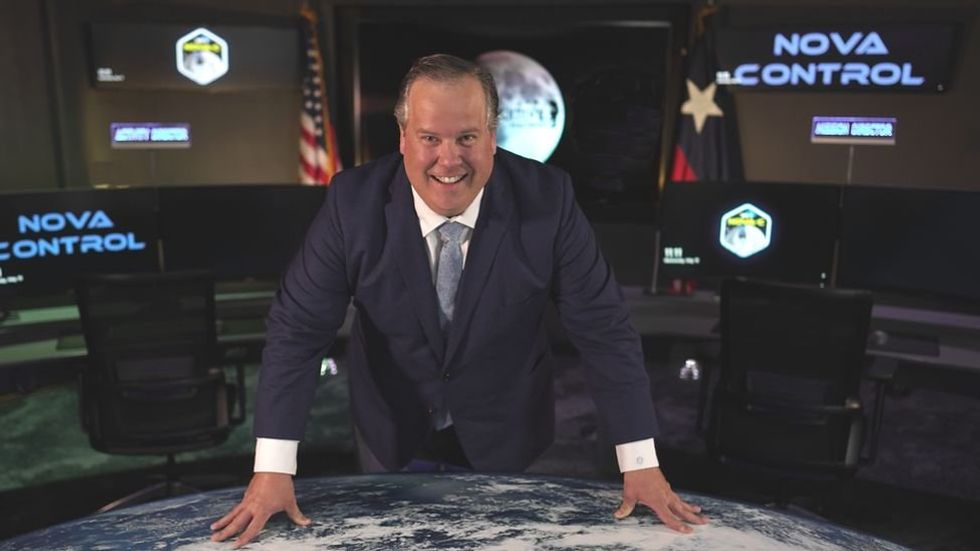
Tim Crain joins the Houston Innovators Podcast. Photo via intuitivemachines.com

It might surprise many to learn that publicly traded, NASA-backed Intuitive Machines, which has emerged as a commercial leader within lunar access technology development, had several pivots before finding its niche within space innovation.

In fact, as Co-Founder and CTO Tim Crain explains on this week's episode of the Houston Innovators Podcast, the company was founded as a space-focused think tank. Crain, along with his co-founders CEO Steve Altemus and Chairman Kamal Ghaffarian, came together in 2013 to start Intuitive Machines, which recently moved into a $40 million headquarters in the Houston Spaceport.

"At the time, our thought was, 'let's take the best of human space flight engineering processes, disciplines, and know how, and look at how we might commercially deploy that for biomedical, energy, big data, and aerospace,'" Crain says on the show. "We wanted to look at how we use great engineering for some of the hard problems outside of NASA's aerospace sphere." Read more.

Chelsea Williams, financial adviser at Northwestern Mutual
Houston-based financial adviser Chelsea Williams helps clients overcome their unique generational financial uncertainties by equipping them with tips and resources to get them on the path to financial wellness. Photo courtesy

In a guest column for InnovationMap, Chelsea Williams, financial adviser at Northwestern Mutual, shared tips on overcoming financial uncertainty across different generations.

"While the types of financial stressors might vary across generations and cities, the most important step to managing financial uncertainty is initiating a conversation with an adviser," she writes in her column. "Just like going to the doctor regularly, routine financial check-ups are incredibly important to catch financial headaches early on and stay ahead of long-term financial health." Read more.

Nicolaus Radford, founder and CEO of Nauticus Robotics
Houston-based Nauticus Robotics founder, Nicolaus Radford, celebrated an acquisition for his company. Image via LinkedIn

A Houston company that harnesses the power of robotics hardware and programing for underwater use has made an acquisition.

Nauticus Robotics Inc. (NASDAQ: KITT) announced it has acquired 3D at Depth Inc., a Colorado-based company with a subsea light detection and range, LiDAR, technology for inspection and data services. The deal closed for approximately $34 million in stock, before certain purchase price adjustments and the assumption of debt, per the news release.

“The future of subsea services lies in autonomy, data gathering, and analytics,” Nicolaus Radford, Nauticus’ founder and CEO, says in the release. “LiDAR has long since been core to terrestrial autonomy and by adding 3D’s capabilities to the Nauticus Fleet, we enhance autonomous vehicles in the offshore market. This acquisition increases the value of Nauticus’ fleet services and positions the Company to capitalize on data acquisition and analytics for subsea operations.” Read more.
Houstonians in particular expressed more stress than other communities in terms of household finances and physical and mental health. Photo via Getty Images

Houston expert on tips on overcoming financial uncertainty across different generations

guest column

Whether you’re a millennial or baby boomer, financial uncertainty is not limited by age, with new data from Northwestern Mutual’s 2023 Planning & Progress Study revealing that most Americans are losing sleep at night because of it. Houstonians in particular expressed more stress than other communities in terms of household finances and physical and mental health, according to a recent survey.

While the types of financial stressors might vary across generations and cities, the most important step to managing financial uncertainty is initiating a conversation with an adviser. Just like going to the doctor regularly, routine financial check-ups are incredibly important to catch financial headaches early on and stay ahead of long-term financial health.

As a Houston-based financial adviser, I help my clients overcome their unique generational financial uncertainties by equipping them with tips and resources to get them on the path to financial wellness.

Understanding where financial uncertainty comes from generationally

  • Gen Z: Studies have shown that even while Gen Z is the most confident that they’ll be prepared for retirement when the time comes, they still struggle with feelings of uncertainty on how to achieve their specific financial goals. In my experience, I have found that uncertainty among this age group often stems from a lack of financial literacy surrounding their finances. A recent financial literacy study revealed that Gen Z respondents averaged the lowest at 43 percent in answering finance-related questions correctly.
  • Millennials: Millennials equally suffer from feelings of anxiety about money, with 54 percent of millennial respondents in the P&P study indicating that financial anxiety causes them to feel depressed compared to just 20 percent of baby boomers. Millennials have lived through a pandemic, The Great Recession and slow economic growth, making their mental health and financial wellness a top priority.
  • Gen X: Even while financial uncertainty typically starts to recede later in life at this age, Gen X is facing a turning point as they get closer and closer to retirement. Studies have shown that most Americans believe they will need about $1.27 million to retire comfortably and yet, I see many individuals only recognizing the importance of retirement planning between the ages of 40 and 50. With Gen X holding about six times more debt than their parents did at that age, it’s important for this age group to consider some proactive debt and retirement strategies.
  • Baby boomers: This group has the lowest amount of financial uncertainty, but that doesn’t mean it is nonexistent. I hear a lot of baby boomers state that they wish they had started investing sooner or they wish they had conversations about their finances sooner. As such, this group is typically the most concerned about managing their existing assets and living comfortably for the rest of their lives.

Overcoming financial uncertainty

  • Increase financial literacy: Both millennials and Gen Z grew up in the digital age and expect their financial experiences to be reflective of that. For employers with Gen Z employees, working with a Northwestern Mutual financial adviser on resources to increase financial literacy can be a helpful first step. This could include on-demand webinars, digital toolkits and interactive online portals to access and view their finances.
  • Ensure every dollar has a job: Across all generations, it’s important to ensure no dollar is wasted. In other words, understanding how much of your income should be allocated toward expenses, retirement, savings, etc. is crucial. I typically recommend a budgeting rule that no more than half of an individual’s income goes toward expenses.
  • Initiate financial planning discussions early on: While it may seem daunting, results from the P&P study show that an average of 76 percent of individuals who work with a financial adviser have an overall boost to confidence. With Gen Z often heavily relying on family members for money management, it is important that family members from older generations encourage them to start saving or to consult with a financial adviser at a young age.
  • Take proactive steps toward your finances: No matter what age you are, there are always active steps you can be taking with your finances. Consider increasing the contribution amount to your 401(k) savings plan or working with a financial adviser to diversify your existing investments – or talk to your financial adviser about refinancing opportunities or debt strategies that tackle higher interest loans you may have.

Whether you’re in your 20s or your 50s, financial advisers are uniquely prepared to help you at any stage of your life – and overcome whatever uncertainties you may be facing.


------

Chelsea Williams is a financial adviser at Northwestern Mutual. She's based in Houston and has clients across the country.

Ad Placement 300x100
Ad Placement 300x600

CultureMap Emails are Awesome

Eli Lilly breaks ground on $6.5B pharmaceutical factory in Houston

lilly lands

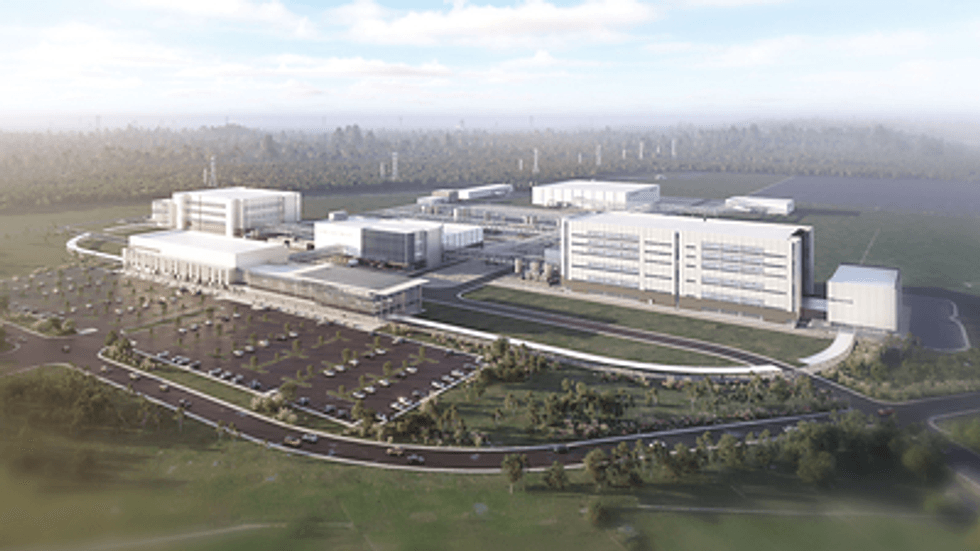
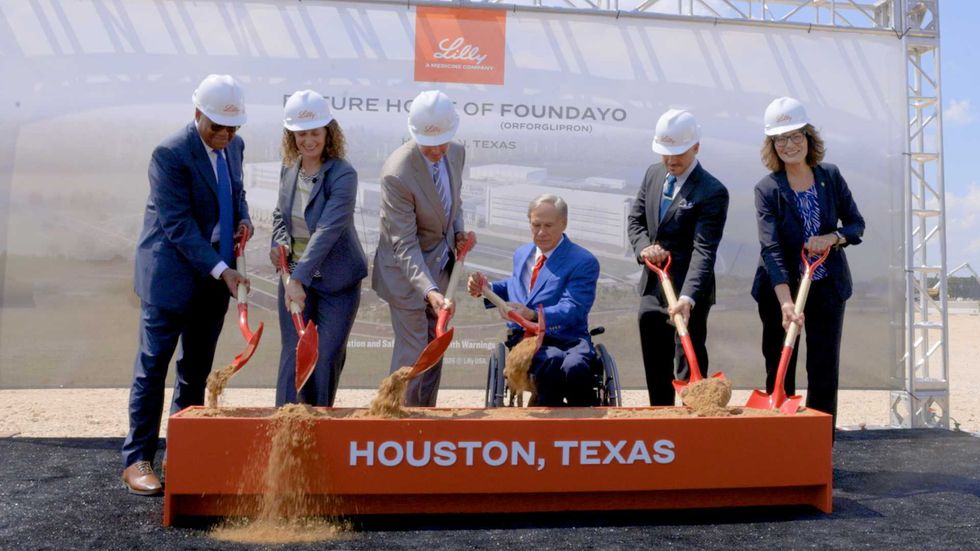
Leading pharmaceutical company Eli Lilly broke ground today, Sept. 21, on its $6.5 billion manufacturing site at Houston's Generation Park.

The 236-acre, state-of-the art factory is expected to come online in 2030 and will manufacture Foundayo, the company's first synthetic oral GLP-1 medication, as well as other advanced therapeutics.

"We are thrilled to break ground on our latest ‘medicines made in America’ site in the great state of Texas," David Ricks, Lilly chair and CEO, said in a prepared statement. "This $6.5 billion investment will help change the game for tens of millions of people suffering from overweight, obesity and its consequences like diabetes. We will make and ship Lilly’s latest products from Texas to people here at home and around the world.”

Houston was up against more than 300 locations in the U.S. for the factory, as part of Lilly’s $50 billion investment in domestic medicine production that has launched 10 manufacturing sites since 2020. Lilly first announced Houston had been selected for the site last September.

Photo via gov.texas.gov

As Abbott mentioned, the site is expected to create hundreds of jobs, and will hire engineers, scientists, operations personnel and lab technicians once up and running. It will create 4,000 construction jobs while being built.

In an effort to support workforce development, Lilly also announced a $12.5 million commitment to Houston's San Jacinto College in addition to a $2.5 million charitable donation to the San Jacinto College Foundation. The funding will go toward hands-on training, equipment and facilities to support future technicians, operators, maintenance professionals, and other manufacturing talent, according to Lilly. The charitable donation will fund scholarships for students.

"This relationship will build a strong, sustainable talent pipeline for Lilly while creating meaningful, high-demand career opportunities across our region,” Brenda Hellyer, chancellor of San Jacinto College, said in the release.

"When you invest in a place like Houston, you invest in its people first," Edgardo Hernandez, executive vice president and president of Lilly Manufacturing Operations, added. "This facility will run on the talent of this community, powered by our relationship with San Jacinto College. We're hiring across the greater Houston area to help residents build careers close to home."

Rendering courtesy Eli Lilly

Lilly previously said it chose Generation Park, a 4,300-acre, master-planned commercial district near Lake Houston, because of factors such as financial incentives, access to utilities and transportation and the region’s business-friendly environment. Generation Park is home to campuses for San Jacinto College and Lone Star College.

Since Lilly first announced plans for the site, another fellow pharma giant has made plans to move into Generation Park. Bristol Myers Squibb Co. announced last month that it would build a $2.3 billion factory in the district. The site is expected to manufacture small molecule, biologic and antibody-drug conjugates and will also come online around 2030. Read more here.

UH Health names leader of new digital health institute

new exec

Recently launched UH Health has named the first-ever executive director of its new Institute for Digital Healthcare Transformation at the University of Houston.

Beto López has been tapped to lead the new initiative that aims to help develop and commercialize health care technologies centered around university research.

Launched in August, the Institute for Digital Healthcare Transformation leans on experts from UH’s engineering, medicine, business, law and other departments and will connect with industry partners. It will initially focus on mobile health applications, sensors, wearables and artificial intelligence, according to UH.

“Most digital health initiatives and commercialization efforts start with the technology and hope adoption follows. But the translation gap isn't a science problem — it’s a scaffolding problem between researchers, the community and the market,” López said in a news release. “I've spent the past 10 years building that scaffolding in places that weren’t wired for it, and I'm looking forward to building it here at UH to help ensure new health care technologies reach the people and communities that can benefit from them most.”

López previously spent 10 years at San Francisco-based innovation consultancy company IDEO, where he led over 100 projects for Fortune 500 companies and public agencies. He co-founded and served as managing director of the Design Institute for Health at UT Austin’s Dell Medical School; and also co-founded a social venture studio/venture capital fund focused on health care innovation. He worked alongside Houston’s Legacy Community Health during the COVID-19 pandemic.

“Beto understands that breakthrough technology alone doesn't transform health care — it has to be designed around the needs of patients, providers and communities and have a clear path into practice,” Jonathan McCullers, vice president for health affairs at UH, added in the news release. “His experience spanning academic health care and venture capital equips him to bring together researchers, health care organizations, entrepreneurs and investors. This makes him uniquely suited to lead this institute and help turn the university's innovation into solutions that improve people's lives.”

The University of Houston launched UH Health, its new cross-disciplinary academic venture, in July. It aims to bring together the university's health-related education, research and community impact under one umbrella.

ExxonMobil gets approval for $5B Texas Gulf Coast carbon capture project

CCS Expansion

Spring-based ExxonMobil has won approval from the Texas Railroad Commission for a $5 billion carbon capture and storage project in East Texas.

Dominic Genetti, senior vice president of CCS at ExxonMobil, told The Financial Times, which broke the news, that the Railroad Commission’s action is a “major milestone” that lets the company keep expanding along the Gulf Coast. In a 2-1 vote, commissioners authorized a carbon sequestration permit for the project.

“The Railroad Commission clearly recognizes the important role carbon capture and storage can play in meeting growing global demand for lower-carbon products while supporting new jobs and economic growth,” Genetti said.

The U.S. Environmental Protection Agency (EPA) approved ExxonMobil’s Rose CCS project last year.

The project will enable the company to inject about 53 metric tons of industrial customers’ carbon emissions into three underground wells it drilled in the Beaumont-Port Arthur area. Over a 13-year period, ExxonMobil plans to inject about 4 million metric tons per year into the Fleming and Upper Frio rock formations, according to Carbon Herald.

ExxonMobil says it owns the world’s first and largest CCS system, comprising 1,300 miles of CO2 pipeline and secure storage sites. Seventy percent of the pipelines are along the Gulf Coast.

The company ramped up its CCS business in 2023 with the $4.9 billion purchase of Denbury, which owned about 1,000 miles of CO2 pipelines.

“Our expertise, combined with Denbury’s talent and CO2 pipeline network, expands our low-carbon leadership and best positions us to meet the decarbonization needs of industrial customers while also reducing emissions in our own operations,” ExxonMobil Chairman and CEO Darren Woods said when the deal closed.

In January, Genetti wrote in a post on ExxonMobil’s website that the company is committed to CCS “for the long haul.”

“CCS is not new technology, but it’s flown relatively under the radar compared with the attention that production of hydrocarbons commands,” he wrote. “Now, as the world becomes more aware of the need to reduce emissions, CCS finally has a brighter spotlight and a broader runway to scale up.”

The company also announced this week that it has begun CCS operations at a direct reduced iron facility in Convent, Louisiana. The project will capture, transport and store up to 800,000 metric tons of CO2 per year, according to the company.

---

This article first appeared on EnergyCapitalHTX.com.